


Recruit Holdings (TSE:6098) put fresh numbers on the table with its half year earnings on 11 November, reporting higher profit along with an interim dividend of ¥13 per share and an ongoing share buyback.
The fresh results landed against a sharp pullback in Recruit Holdings' share price over the past week, with the stock down 6.7% on a 7 day basis and 5.1% on the day of the release, even as the year to date share price return sits at 86.4% and the 1 year total shareholder return is 105.1%. This points to strong longer term momentum despite the recent cool off.
Spot opportunities riding similar momentum by scanning our hand picked 73 high quality undiscovered gems alongside Recruit Holdings after this earnings and capital returns update.After that surge in earnings and the pullback in Recruit Holdings’ share price, the spread between today’s ¥16,810 level and the various value estimates is hard to ignore. Where does fair value really land now?
Most Popular Narrative: 9.6% Undervalued
On the analyst consensus Narrative on Simply Wall St, Recruit Holdings screens as undervalued, with a fair value of ¥18,587.50 against the latest ¥16,810 close. This puts the current pullback in a different light.
Earlier views leaned on broad revenue growth from automation, digitalization and international expansion. The focus now is on Recruit Holdings driving earnings per share through AI hiring tools, ARPJ growth, GMV linked pricing and capital returns, even if revenue growth is more muted.
See why 7 investors see Recruit Holdings as 10% undervalued.
Result: Fair Value of ¥18,587.50 (UNDERVALUED)
Still, the narrative around Recruit Holdings can easily crack if U.S. job postings on Indeed stay weak, or if the Japan Fair Trade Commission probe leads to costly penalties.
Find out about the key risks to this Recruit Holdings narrative.
Another View: What Recruit Holdings’ P/E Is Saying
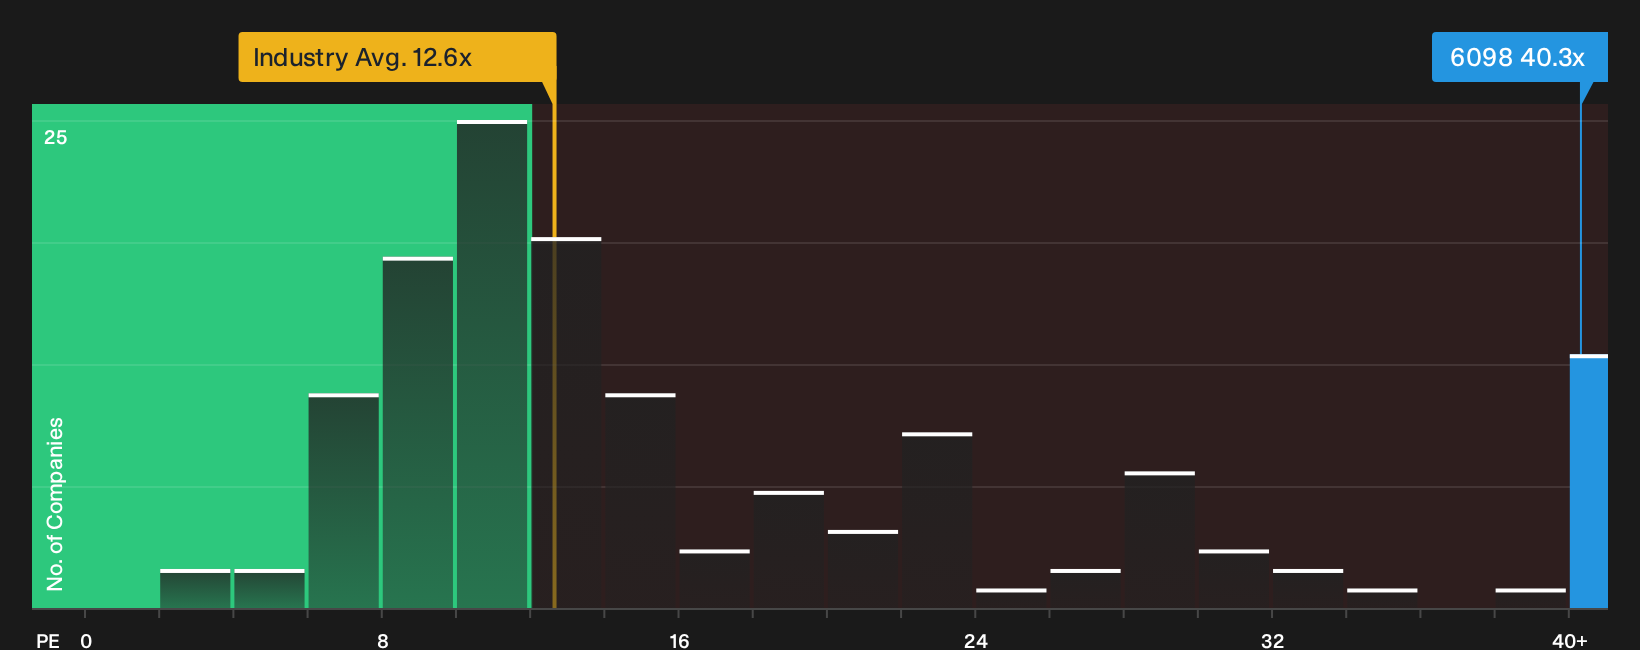
There is a very different message coming from plain P/E math. Recruit Holdings trades on 40.3x earnings, above both its own fair ratio of 37.9x and the JP Professional Services average of 12.6x, as well as the 18x peer group level. That rich gap points to valuation risk more than clear upside, so it raises the question of how much of the bullish narrative is already in the price.
For a closer look at how this earnings based yardstick lines up with the story on margins, growth and risks, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed signals on Recruit Holdings so far. Consider reviewing the details while they are current and pressure test the story for yourself by weighing 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Recruit Holdings?
Recruit Holdings gives useful context, but your portfolio benefits when you line up a few different sources of potential return and risk control.
- Target resilient performers by reviewing a 19 resilient stocks with low risk scores that aims to keep big portfolio drawdowns in check while still leaving room for upside.
- Grow your income stream by scanning 26 dividend fortresses that focus on higher yields alongside balance sheets that can support ongoing payouts.
- Hunt for quality at a reasonable price through 20 high quality undervalued stocks before other investors start paying closer attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com