


Austin, Texas-based Flex Ltd. (FLEX) provides technology innovation, supply chain, and manufacturing solutions to data center, communications, enterprise, consumer, automotive, healthcare, industrial, and power industries. With a market cap of $29.2 billion, the company designs and develops original design manufacturing (ODM) products.
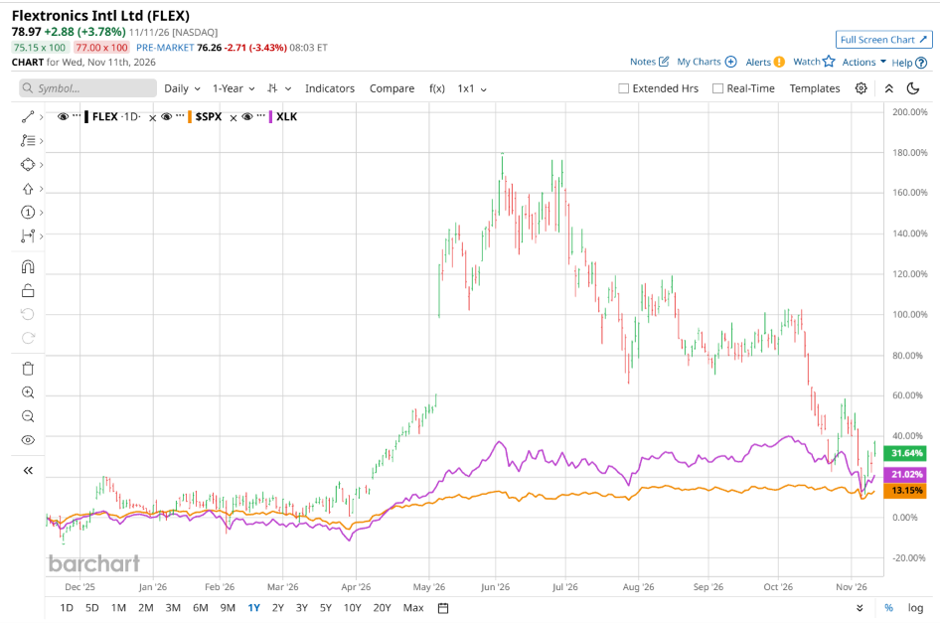
Shares of this electronics manufacturing services company have outperformed the broader market over the past year. FLEX has gained 28.4% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 11.3%. In 2026, FLEX stock is up 30.7%, surpassing the SPX’s 11.3% rise on a YTD basis.
Zooming in further, FLEX’s outperformance is also apparent compared State Street Technology Select Sector SPDR ETF (XLK). The exchange-traded fund has gained about 19% over the past year. Moreover, the stock’s returns on a YTD basis outshine the ETF’s 21.1% gains over the same time frame.
FLEX delivered strong results driven by accelerated growth across all segments, led by a 54% surge in Cloud and Power Infrastructure and solid performance in Regulated Manufacturing Solutions and Integrated Technology Solutions. Management highlighted margin expansion, particularly a rise to roughly 16% in the Power segment, bolstered by volume growth, productivity gains, and the integration of EPC Power. Looking ahead, the company is focused on high-growth compute, power, and cooling solutions, proactive supply chain management, and preparations for the upcoming spin-off of its Cloud and Power Infrastructure business as Axiom.
For the current fiscal year, ending in March 2027, analysts expect FLEX’s EPS to grow 51.2% to $4.52 on a diluted basis. The company’s earnings surprise history is impressive. It beat or matched the consensus estimate in each of the last four quarters.
Among the 12 analysts covering FLEX stock, the consensus is a “Strong Buy.” That’s based on 11 “Strong Buy” ratings, and one “Moderate Buy.”
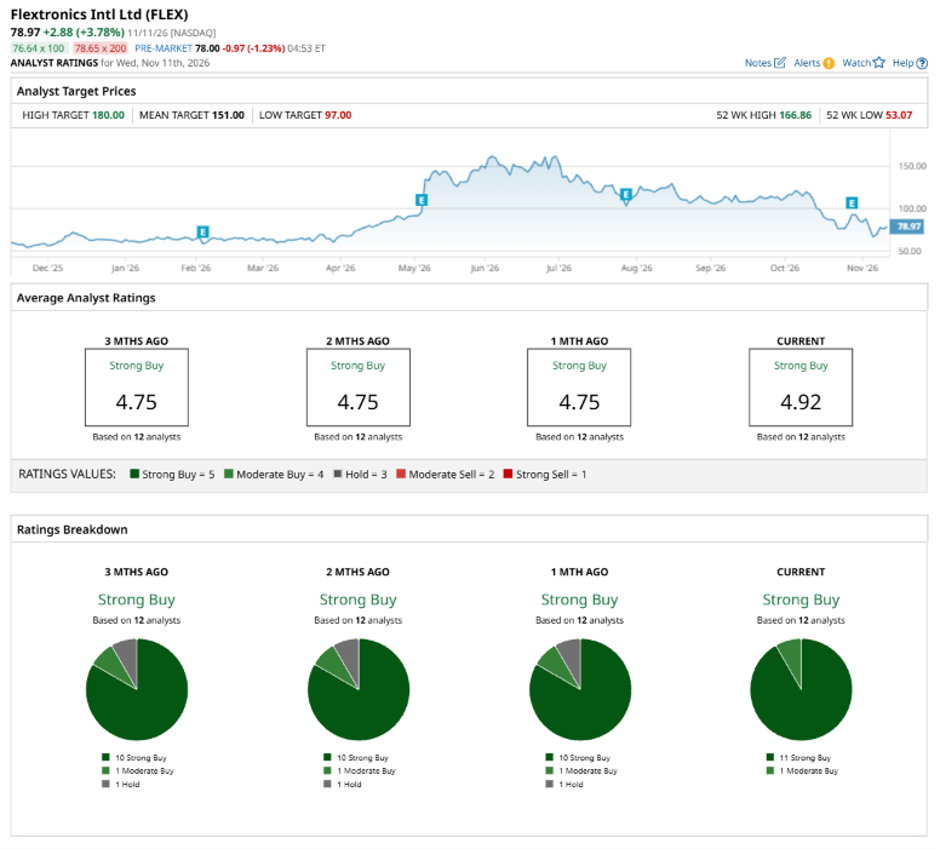
This configuration is more bullish than a month ago, with 10 analysts suggesting a “Strong Buy.”
On Nov. 11, Tim Long from Barclays PLC (BCS) maintained a “Buy” rating on FLEX, with a price target of $128, implying a potential upside of 62.1% from current levels.
The mean price target of $151 represents a 91.2% premium to FLEX’s current price levels. The Street-high price target of $180 suggests an ambitious upside potential of 127.9%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.