


Moog has delivered a powerful run in recent years, and the latest share price around US$347.95 puts a lot of weight on what its earnings can support. With that backdrop, the key issue for investors is whether the recent gains leave the stock fairly aligned with its profit power or leaning ahead of it.
- Moog has returned 353.1% over the past 5 years, which raises the question of how much of that rise is anchored in sustainable earnings versus higher expectations baked into the P/E.
- The business model is closely tied to complex motion control and aerospace systems, so long project cycles and capital intensive programs can shape how consistently earnings convert into cash that can justify the current multiple.
- There is a second opinion on Moog worth weighing. See what analysts think Moog's shares could be worth.
The stock's next move may depend on whether Moog's current earnings level and trajectory are strong enough to back up the valuation investors are paying today.
If you are questioning whether Moog's earnings fully support this price, it can help to compare that same earnings lens across 32 high quality undervalued stocks.
Does Moog Look Pricey on Earnings?
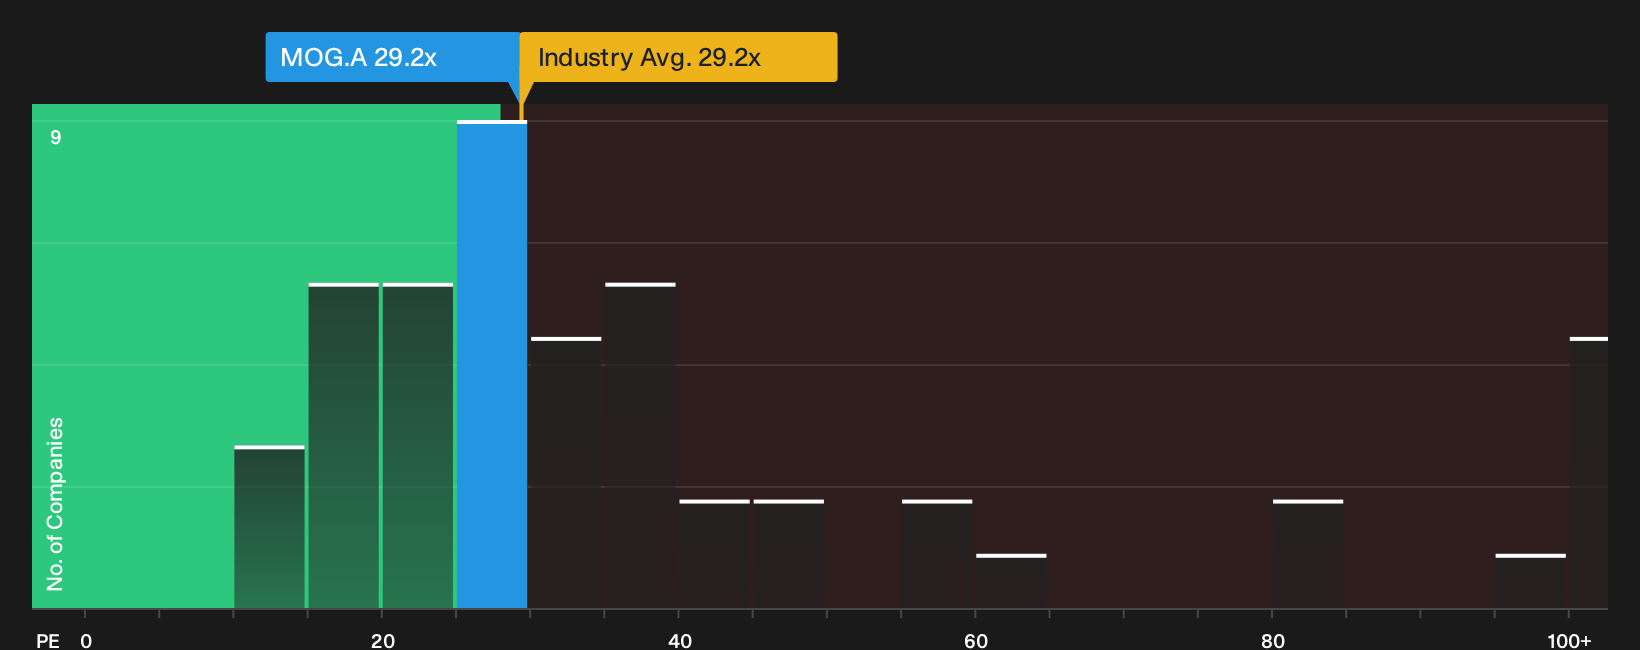
The P/E ratio suits Moog because earnings sit at the center of how investors are framing the story today. The stock trades on a P/E of 29.2x, which is higher than the peer average of about 25.2x and roughly in line with the wider aerospace and defense group at about 29.2x. That means buyers are currently paying a premium to similar companies for each dollar of Moog's profit.
The fair P/E that would typically be expected for Moog, after factoring in things like its margins, risk profile and scale, screens lower than where the shares trade now, so on this lens the stock looks overvalued. For a holder or prospective buyer, the key question is whether Moog's earnings quality, project portfolio and balance of aerospace and industrial exposure justify paying above that modelled level. Explore the numbers behind Moog's P/E valuation.
The Moog Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take Moog's valuation puzzle and turn it into a set of explicit future assumptions so you can see what kind of growth, margins and earnings profile would need to play out for the stock to be worth materially more or less than today, and they sit on the Community page. Where a single ratio or model throws up one number, Narratives lay out the future path that number relies on so you can judge over time whether reality still lines up with it.
One of the top narratives on Moog: 28% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"Record quarterly sales of US$1.1b and a 12 month backlog that is 23% higher, together with 16.4% adjusted operating margin and free cash flow of US$133 million…"
Discover why this Narrative puts Moog at 28% undervalued.
Before acting on Moog's valuation, look at who is steering the ship
Moog's price tag rests on choices made in boardrooms, so it pays to understand who holds that wheel, how they are rewarded and whether those pay plans truly line up with your interests. See who runs Moog and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com