


NCR Atleos (NATL) has just paired stronger profitability with a fresh product launch. Recent quarterly results showed higher net income and earnings per share, while the new AllTM retail ATM solution targets broader in-store financial activity.
This mix of stronger earnings and the AllTM launch has arrived after a solid run in the shares, with a year to date share price return of 29.47% and a 3 year total shareholder return of 94.35%. This suggests momentum has been building as the market reassesses NCR Atleos’ potential and risks.
Scan beyond NCR Atleos and compare this profitability plus product-launch profile with 19 high quality undiscovered gems that are also pairing fresh offerings with solid fundamentals.
NCR Atleos has already put a near 30% YTD gain on the board, off the back of sharper earnings and the AllTM launch. Is that run your entry point now or a reason to wait for a cheaper shot?
Most Popular Narrative: 4% Undervalued
NCR Atleos last closed at $48.20, which sits a little below the analyst consensus Narrative fair value of about $50.27. That view, captured in the analyst consensus Narrative on Simply Wall St, leans heavily on recurring cash flows and ATM as a Service momentum.
High recurring revenue mix (over 70% in Q2), significant productivity gains through AI-driven service optimization, and a rapidly scaling backlog are driving strong margin expansion and robust free cash flow, underpinning announced share buybacks and sustained EPS growth, suggesting current valuation does not reflect enhanced long-term earnings power.
See why 6 investors see NCR Atleos as 4% undervalued.
On those assumptions, the gap between the roughly $50 fair value and the $48.20 share price points to a modest undervaluation rather than a deep discount. The discount rate used in that Narrative is 8.68%, so the fair value estimate is built on a relatively standard required return for a listed financial technology business.
The Narrative also bakes in revenue growth expectations of about 3.9% a year and a profit margin profile of roughly 11.2%. This is a clear step up from the most recent 6.1% net margin reported in the statements data. That creates a simple test for you as an investor. Decide whether those higher margin and earnings forecasts line up with your own view of NCR Atleos’ ATM as a Service rollout, its hardware refresh cycle, and the risks from digital banking, fintech rivals, and regulation that the Narrative itself flags.
Analysts currently have a price target around $50.27, only about 4% above the last close, so the market is not pricing in an extreme scenario either way. The spread is narrow enough that small changes in inputs like the discount rate or long term profitability could swing the Narrative fair value closer to, or above, today’s market level.
Result: Fair Value of $50.27 (UNDERVALUED)
Still, this narrative leans on assumptions that could crack if digital banking adoption cuts ATM usage faster than expected or if rising regulation pushes NCR Atleos’ compliance costs higher.
Find out about the key risks to this NCR Atleos narrative.
Another View On NCR Atleos’ Value
The analyst Narrative leans toward a modest undervaluation, but our DCF model tells a very different story. On those cash flow assumptions, NCR Atleos screens as overvalued, with the $48.20 share price sitting well above an estimated future cash flow value of $24.87.
This kind of gap does not automatically make either model right or wrong. It does signal that your view on long term cash generation and reinvestment needs to be very clear before treating a 4% “undervaluation” as meaningful.
Look into how the SWS DCF model arrives at its fair value.
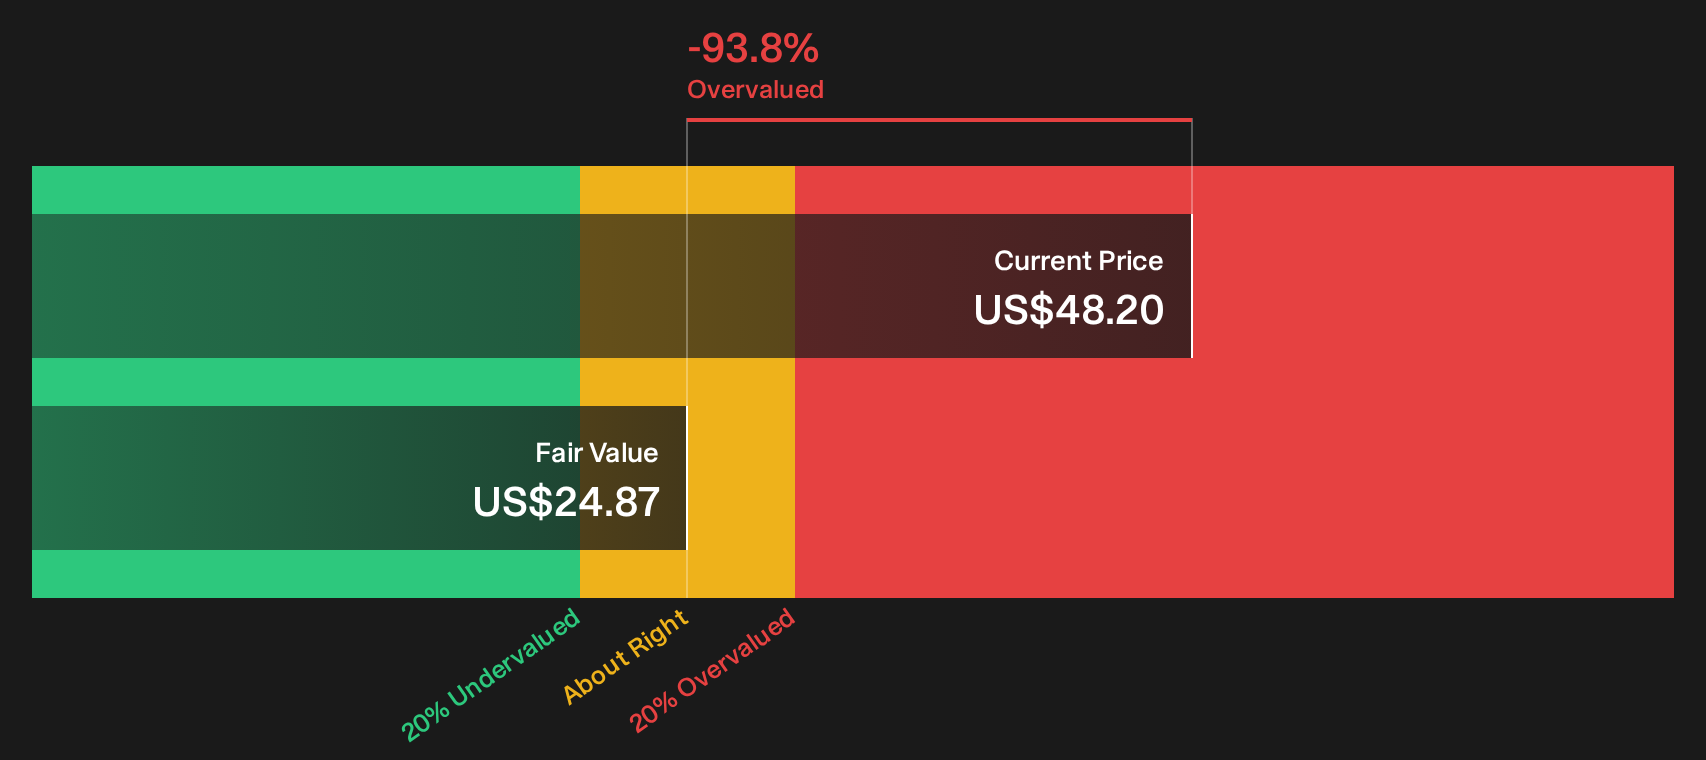
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NCR Atleos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on value, strong opinions on both risk and reward, and a stock that has already moved this far all put the focus back on your own homework. If you want a quick snapshot of both sides before deciding where you land on NCR Atleos, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond NCR Atleos?
If NCR Atleos has sharpened your focus on quality and pricing, do not stop here. The next opportunity you rate highly could already be on Simply Wall Street’s radar.
- Spot potential bargains early by scanning companies that still look attractively priced on both quality and valuation using our 32 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses that pair sturdy balance sheets with solid fundamentals through the list of solid balance sheet and fundamentals (23 results).
- Target reliable cash returns by focusing on companies built around strong payout profiles and consistent income using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com