


Magnolia Oil & Gas (MGY) just posted its third quarter and nine month 2026 results, with revenue and net income both higher than a year earlier, drawing fresh attention to the stock.
The latest earnings release landed alongside a 3.53% 1 day share price return to US$23.78, although the stock is still down 8.04% over the past 90 days on a share price basis. Despite that softer recent momentum, Magnolia Oil & Gas has delivered a 7.45% 1 year total shareholder return and a 35.69% total shareholder return over five years, which points to long term holders being rewarded even as near term sentiment adjusts to changing expectations around growth and risk.
Scan how Magnolia Oil & Gas compares with other cash generative operators in the sector by reviewing our hand picked list of 32 high quality undervalued stocks.
Magnolia Oil & Gas now trades at a sizeable discount to both analyst targets and estimated fair value, even after the latest earnings lift. Is that a mispricing, or a clear signal that caution still rules?
Most Popular Narrative: 27% Undervalued
On the analyst consensus Narrative on Simply Wall St, Magnolia Oil & Gas screens as undervalued, with a fair value of $32.75 against the latest $23.78 close and a 7.24% discount rate anchoring that view.
The WildFire Energy acquisition, which brings the pro forma Giddings position to nearly 1.3 million net acres and materially increases proved developed reserves, gives Magnolia Oil & Gas a longer high quality resource base that can underpin future earnings and cash flow.
See why 13 investors see Magnolia Oil & Gas as 27% undervalued.
Result: Fair Value of $32.75 (UNDERVALUED)
Still, Magnolia Oil & Gas carries clear pressure points, including higher interest costs and share dilution from WildFire, as well as recent EBITDA margin compression that investors are watching closely.
Find out about the key risks to this Magnolia Oil & Gas narrative.
Another View: What Multiples Say About Magnolia Oil & Gas
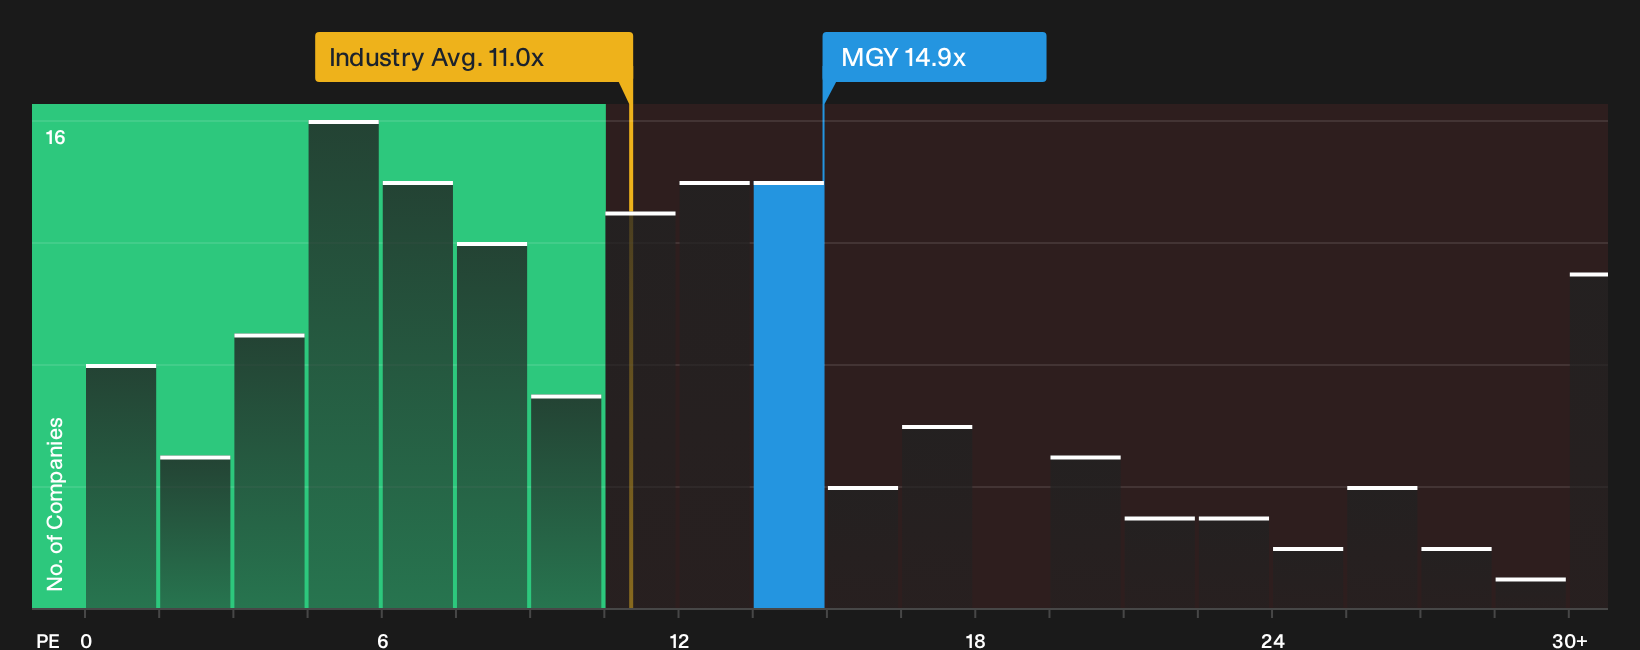
The DCF workup points to Magnolia Oil & Gas trading at a steep discount to future cash flow, yet the simple P/E check tells a different story. At 14.9x earnings, the stock is pricier than the US Oil and Gas sector on 11x and the peer group on 9.1x, even though the fair ratio sits higher at 18.2x. That mix of discount to fair ratio but premium to industry and peers raises a practical question for investors: Is the current price more about quality, or about paying up for expectations that still need to be earned in the numbers?
For a closer look at how that P/E gap could close over time, and what it might mean for upside or downside risk, see the fuller valuation breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages in the data or a clear setup for Magnolia Oil & Gas? Take a closer look at both sides of the ledger by weighing up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Magnolia Oil & Gas?
Magnolia Oil & Gas offers one angle on energy, but your portfolio benefits when you regularly scan fresh opportunities across sectors, sizes, and balance sheet profiles.
- Target higher potential upside by reviewing a focused set of 19 high quality undiscovered gems that many investors have not priced carefully yet.
- Prioritise resilience and capital preservation by screening for 30 resilient stocks with low risk scores that may better match a steadier investing style.
- Strengthen your defensive holdings by filtering for a list of solid balance sheet and fundamentals (23 results) that can better handle tougher operating conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com