


PHINIA (PHIN) just paired a strong third quarter with a higher full year 2026 outlook, as management lifted ranges for both net sales and net earnings, drawing fresh attention to the stock.
PHINIA’s recent guidance update and third quarter release have arrived alongside a sharp pick up in the share price, with a 27.73% 1 month share price return lifting the stock to US$72.08, while the 1 year total shareholder return of 33.49% and very large 3 year total shareholder return of about 3x indicate that momentum has been building over a longer stretch.
Scan beyond PHINIA’s momentum and compare it with a curated 32 high quality undervalued stocks that also pairs solid cash generation with disciplined balance sheets.
The jump in PHINIA’s share price after stronger guidance and earnings can look like a clean read on business quality, or like traders chasing a hot chart. The valuation work now shows which story fits.
Most Popular Narrative: 15% Undervalued
PHINIA’s analyst consensus Narrative on Simply Wall St points to a fair value of $84.40, set against the latest close at $72.08. This frames the stock as modestly undervalued based on analyst cash flow and earnings assumptions that use a 9.66% discount rate.
Disciplined cash generation and capital allocation, including raised 2026 free cash flow guidance to a range of US$210 million to US$250 million, capex held below the 4% of sales target and sizeable buybacks since the spin, creates scope for further per share earnings impact and potential re rating of PHINIA’s cash flow profile.
See why 10 investors see PHINIA as 15% undervalued.
Result: Fair Value of $84.40 (UNDERVALUED)
Still, the PHINIA story leans heavily on internal combustion exposure and tariff or currency benefits, so a faster EV shift or a reversal in those supports could challenge this undervalued narrative.
Find out about the key risks to this PHINIA narrative.
Another View: PHINIA Looks Pricy On Earnings
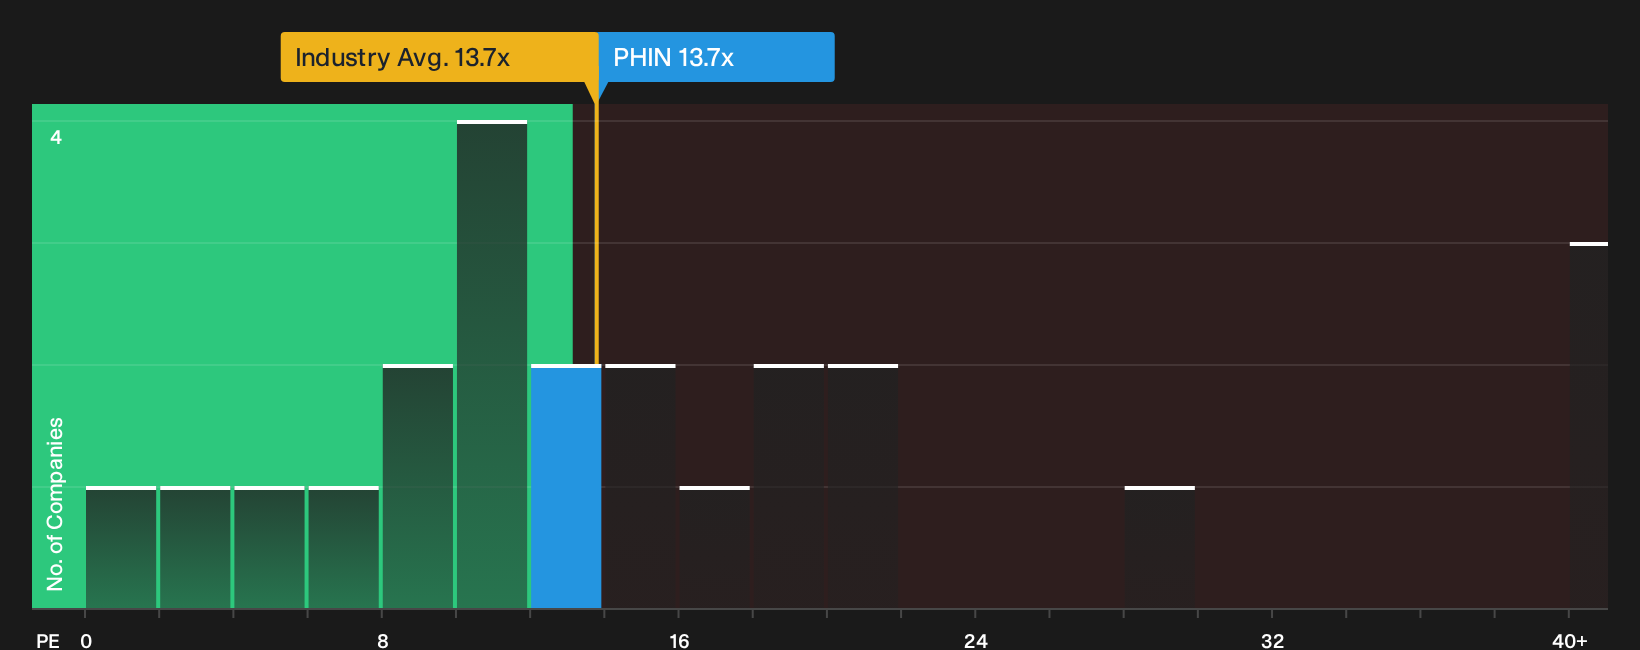
On cash flows, PHINIA screens as undervalued. On earnings, the story is different. The current P/E is 13.7x, above both the fair ratio of 12.7x and the peer average of 12.4x. This points to less room for error if growth or margins soften. Which signal do you trust more?
For investors weighing this earnings based view against the cash flow work, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on PHINIA so far, with both concerns and bright spots in the story, mean your own read on the risk reward trade off matters. To weigh the downside against the upside using the same toolkit as other investors, start by reviewing the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond PHINIA?
If PHINIA has sharpened your focus on valuation and quality, widen the lens and let a few targeted screeners surface opportunities you may otherwise miss.
- Target resilient balance sheets by working through a curated list of solid balance sheet and fundamentals (23 results) that filters for financial strength and fundamental support.
- Spot potential mispricing by scanning a focused 32 high quality undervalued stocks designed to highlight quality businesses that trade below their assessed worth.
- Hunt for under-the-radar potential with a 19 high quality undiscovered gems that surfaces lesser known companies backed by strong fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com