


Comfort Systems USA has had a striking run over the past few years, and even with a recent pullback the question now is whether the current price is still supported by the earnings the business is generating. With the stock caught between powerful AI data center enthusiasm and fresh political headlines, investors are asking if the recent share moves line up with what shows up on the income statement.
- Over the past 5 years the stock has delivered a very large total return of about 11x, which puts a lot of pressure on current earnings to justify where the valuation has moved to.
- Recent news around AI driven data center work, political changes and potential restrictions in Texas can reshape how durable Comfort Systems USA's recent revenue and profit growth looks and how investors think about its future earnings base.
- There is a second opinion on Comfort Systems USA worth weighing. See what analysts think Comfort Systems USA's shares could be worth.
The issue now is whether Comfort Systems USA's current share price is appropriately aligned with the earnings it is producing today and what those profits imply for the stock's valuation.
If you want to pressure test this same earnings based question beyond Comfort Systems USA, run the numbers across a wider field of 53 AI infrastructure stocks.
Does Comfort Systems USA Look Undervalued on Earnings?
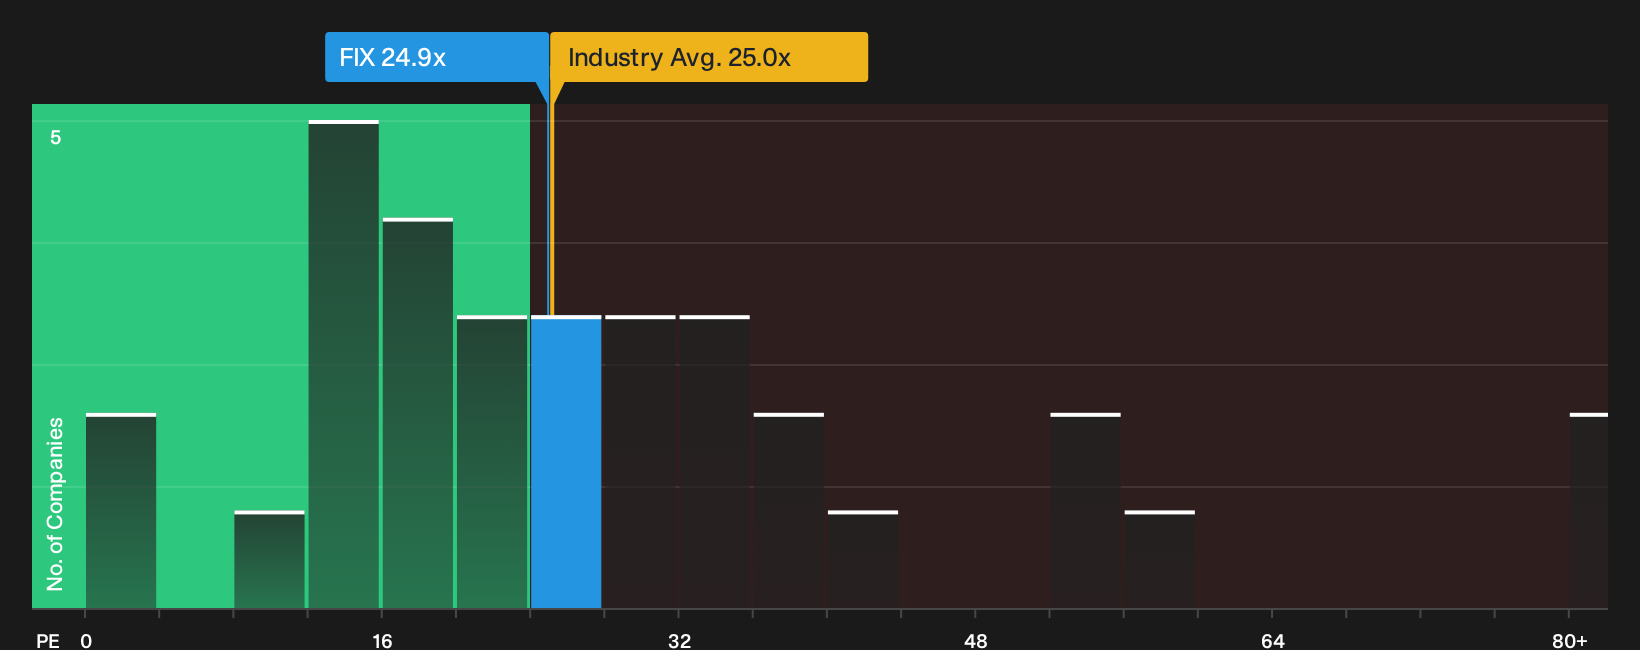
The P/E ratio suits Comfort Systems USA because recent earnings give you a clear anchor for what you are paying today. On this measure, the stock trades at about 24.9x earnings, almost identical to the wider Construction sector on roughly 25.0x. Against more specialised peers that average about 30.3x, the multiple looks lower.
Because of the surge in AI data center headlines and the sharp sell off after the recent political shifts in Texas, that discount to similar contractors matters. The current P/E sits below the level suggested by a fair value model that blends Comfort Systems USA's growth profile, profitability and risk. That model points to the shares pricing in a more cautious earnings path than that framework implies. For an investor weighing the recent revenue and EPS numbers against these political questions, the P/E gap flags a stock that screens as undervalued on earnings compared with what that tailored benchmark would suggest. Explore the numbers behind Comfort Systems USA's P/E valuation.
The Comfort Systems USA Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Comfort Systems USA pick up where the P/E discussion leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the stock to look meaningfully stronger or weaker than today. Each Narrative links its number to a clear view on how Comfort Systems USA's growth profile, profitability and risk could evolve, which you can revisit as fresh information reaches the market through the Community page.
One of the top narratives on Comfort Systems USA: 36% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Record backlog of US$14.1b, up strongly year over year and sequentially, points to continued conversion of contracted work into future revenue and earnings…"
Discover why this Narrative puts Comfort Systems USA at 36% undervalued.
Before acting on Comfort Systems USA's valuation, look at who is steering the ship
Numbers only tell part of the story, because the people setting priorities, controlling capital allocation and deciding how they get rewarded can tilt outcomes in ways price multiples never show. See who runs Comfort Systems USA and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com