


Boeing shares have fallen sharply this year, and the setback raises a simple question for investors who care about valuation. Is the current price tag on Boeing stock still in line with what the business is earning today and what those earnings might reasonably support over time?
- The share price is down 23.4% year to date, which puts fresh focus on whether that drop now roughly matches the underlying earnings power of the business or has moved ahead of it.
- Planned cuts of about 5% in the commercial airplane workforce and ongoing production challenges point to a period in which margins and cash generation may be more heavily influenced by execution risk and cost control than by headline order wins.
- Your read on Boeing is one view; the desks covering it have another. See what analysts think Boeing's shares could be worth.
For investors, the debate is whether Boeing's current share price can be explained by its earnings profile once the recent setbacks and contract wins are weighed together.
If you are weighing whether Boeing's slump lines up with its earnings, it can help to compare that question across 32 high quality undervalued stocks.
Is Boeing Still Cheap on Earnings?
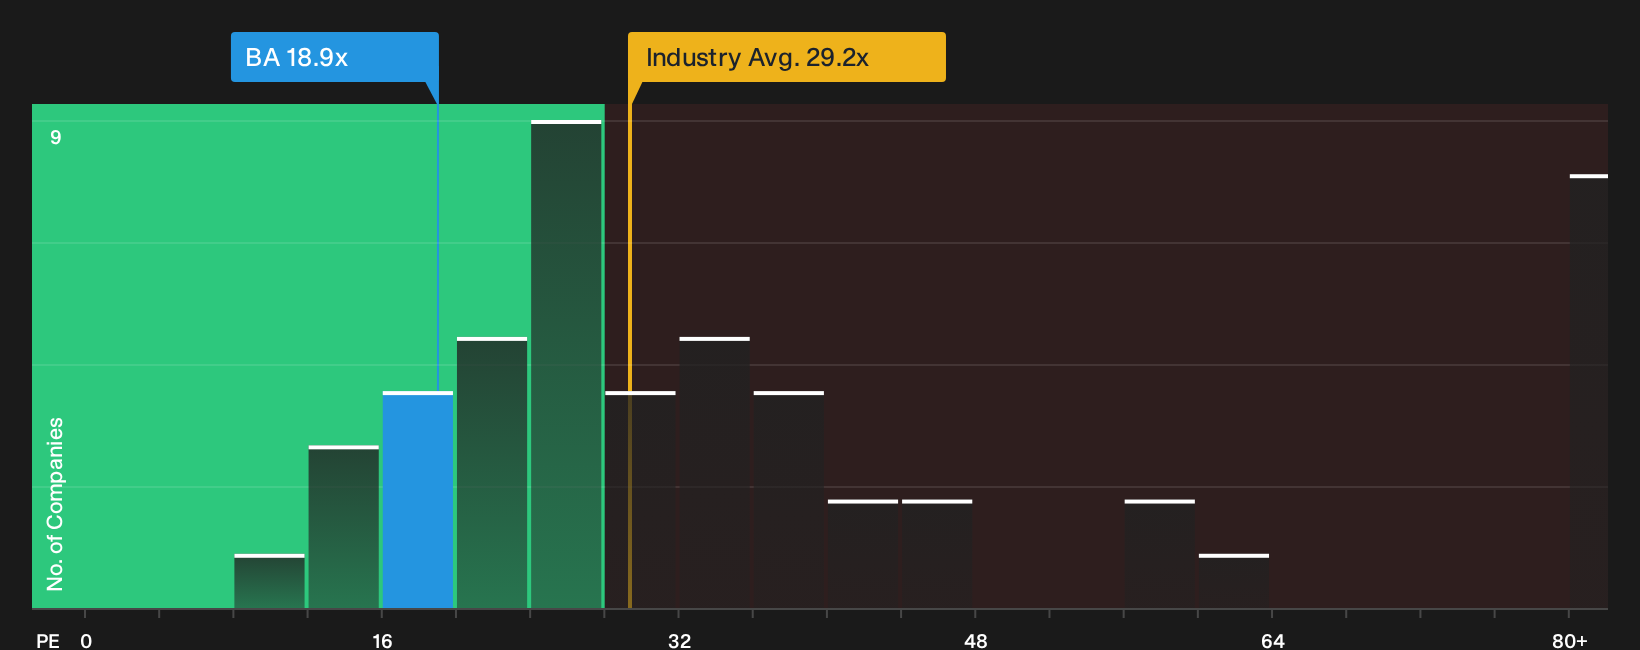
The P/E ratio suits Boeing because earnings are the main yardstick investors watch for this kind of mature industrial group. On that measure, Boeing trades on about 18.9x earnings, while the wider Aerospace & Defense industry averages roughly 29.2x and the peer group comes in near 29.7x. So the stock changes hands at a lower earnings multiple than both sector and direct competitors, even before you factor in its specific contract profile and balance sheet.
The fair P/E the model would expect for Boeing, after accounting for its growth outlook, profitability, size and risk profile, sits above the current multiple. As a result, the shares screen as undervalued on this framework rather than expensive. Because the recent 5% workforce reduction highlights how much execution and cost control are under the microscope, that lower than modelled P/E suggests the market is still applying a safety discount even while earnings are returning as the main driver of the story. Explore the numbers behind Boeing's P/E valuation.
The Boeing Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Boeing pick up where the valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today's level on the numbers. Each scenario ties a grounded fair value estimate to a particular mix of potential catalysts and risks for Boeing, so you can track over time which version of the story seems to be unfolding on the Community page.
Boeing attracts sharply different views, with one camp focused on the backlog and another on what today’s price already assumes.
Bull case: 41% undervalued
According to the bullish analyst Narrative on Simply Wall St, the positive view leans heavily on Boeing's contracted work and backlog quality.
"Boeing's record commercial and defense backlog, including over 6,200 airplanes and a total of US$715b in contracted work, gives management room to prioritize higher margin delivery slots and contract renegotiations that could gradually lift pricing mix..."
Discover why this Narrative puts Boeing at 41% undervalued.
Bear case: 9% overvalued
rcb9, a Simply Wall St Community investor who wrote the Narrative, argues that Boeing already reflects much of the recovery story.
"At the same 10% discount, justifying $230.63 needs roughly 9.3% revenue growth, a 10% net margin, and a 25x exit multiple..."
Explore why this Narrative puts Boeing at 9% overvalued.
The missing piece in Boeing's story
Price tags and backlogs only tell part of the story for Boeing, because the people steering the business and how they are rewarded can quietly tilt outcomes for years. See who runs Boeing and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com