


Spectrum Brands Holdings has logged a sharp share price run, and that raises a simple question for you as an investor. Is the current valuation still grounded in the earnings power of the business, or has the price moved ahead of what the income statement can reasonably support?
- The stock has gained 70.2% over the past year, which puts fresh pressure on the earnings profile to support a much higher equity value.
- The group relies on consumer brands that tend to convert a meaningful share of revenue into cash, so the durability and quality of those earnings can heavily influence how much investors are willing to pay today.
- There is a second opinion on Spectrum Brands Holdings worth weighing. See what analysts think Spectrum Brands Holdings's shares could be worth.
The issue now is whether Spectrum Brands Holdings' current share price is justified by the earnings it is generating today and is expected to produce over time.
If you want to pressure test Spectrum Brands Holdings' recent run against other opportunities framed around valuation, compare it alongside 32 high quality undervalued stocks.
Does Spectrum Brands Holdings Look Pricey on Earnings?
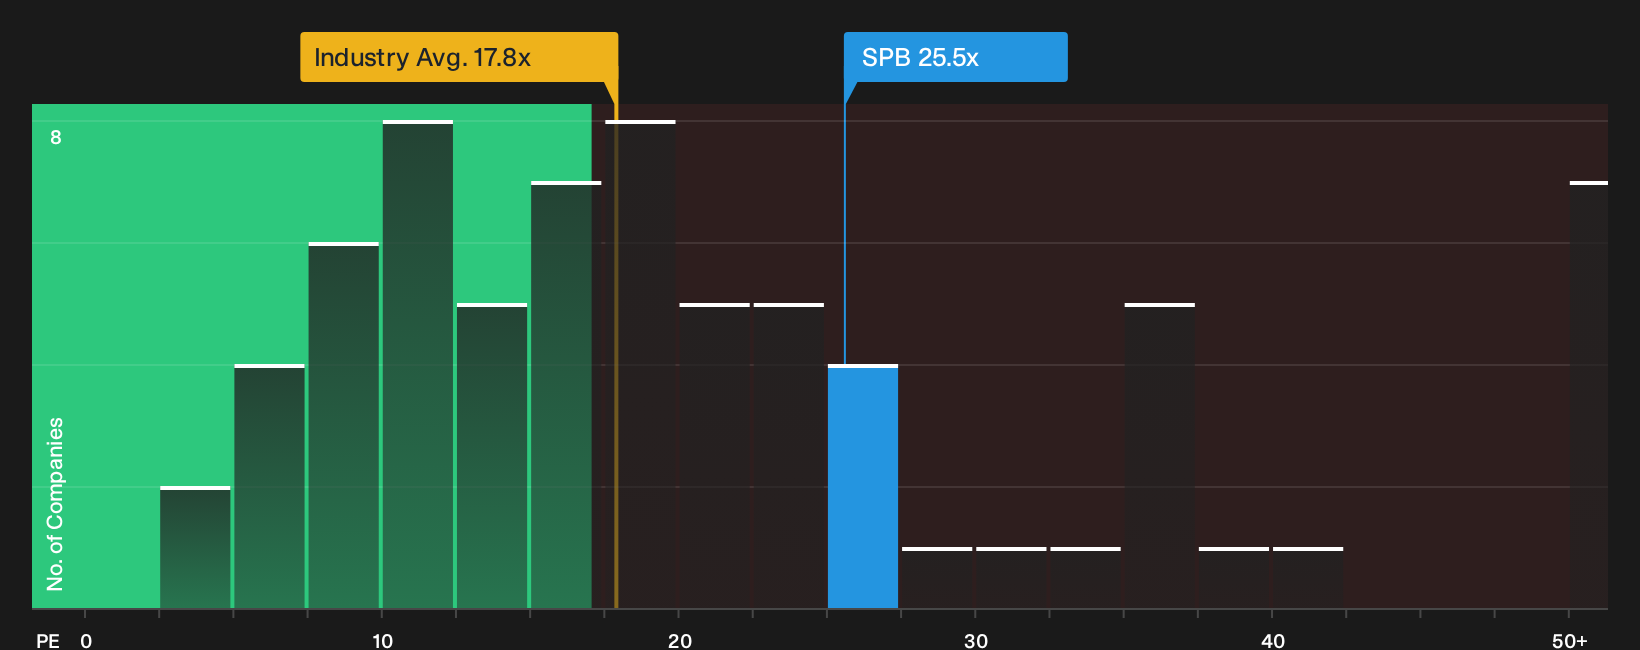
The P/E ratio is a useful fit for Spectrum Brands Holdings because profit remains the main anchor for how this household products group is being priced. The stock trades on a P/E of about 25.5x, which is higher than the Household Products industry average of roughly 17.8x and also above the peer group reading of about 23.4x.
The tailored fair P/E implied by the valuation work comes in below the current multiple. On this basis, the shares screen as overvalued relative to the earnings power that model incorporates. For you as a shareholder or potential buyer, that gap indicates the market is already paying up for the existing profitability profile and risk level rather than leaving obvious room for error. Explore the numbers behind Spectrum Brands Holdings's P/E valuation.
The Spectrum Brands Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives give you a structured way to connect Spectrum Brands Holdings' higher P/E with the specific earnings path that would need to play out for the current share price to look cheap or expensive. Each storyline ties its number to a concrete view on how growth, profitability and business risk might shift from here, which you can revisit as quarterly results and fresh information arrive on the Community page.
One of the top narratives on Spectrum Brands Holdings: 20% undervalued
This Narrative is the bullish analyst Narrative on Simply Wall St, built on the most optimistic analyst price target and forecasts, not one person's view.
"The current valuation and balance sheet position of Spectrum Brands Holdings indicate that the share price reflects limited credit for ongoing EBITDA growth, cash generation, and the potential value of a future Home & Personal Care exit..."
Discover why this Narrative puts Spectrum Brands Holdings at 20% undervalued.
One more Spectrum Brands Holdings factor worth checking before you move on
Price tags and earnings only tell part of the story. The people steering Spectrum Brands Holdings, and the way their incentives line up with your interests, can shift the whole risk and reward profile. See who runs Spectrum Brands Holdings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com