


Butterfly Network (BFLY) just posted third quarter results that paired higher revenue with a smaller net loss year over year, and management lifted full year revenue guidance, which is sharpening the focus on this ultrasound technology stock.
Recent trading shows how quickly sentiment around Butterfly Network can swing. The share price has climbed 9.7% in the last day and 5.5% over the past week. However, it is still down 16.5% over 30 days and 19.4% over 90 days. At the same time, the year-to-date share price return of 90.4% and a one-year total shareholder return of 215.9% point to stronger longer term momentum as investors reassess both growth potential and risk after the upgraded outlook and recent conference appearance.
Spot 37 healthcare AI stocks that, like Butterfly Network, are trying to turn medical imaging advances and AI tools into stronger revenue trends and renewed investor attention.Bulls point to Butterfly Network’s faster top line and shrinking losses. Bears flag the continuing cash burn and volatility. The current share price move puts both views to the test as valuation comes into focus.
Most Popular Narrative: 36% Undervalued
On the analyst consensus Narrative on Simply Wall St, Butterfly Network’s fair value of $11.17 sits above the last close at $7.14. This frames the current debate around whether the stock’s embedded licensing and software potential is fully recognised.
Butterfly Network''s semiconductor-based ultrasound platform is being licensed into a growing set of Embedded partnerships, including a five-year agreement with Midjourney Medical worth up to US$74m and new brain computer interface collaborations. This could support higher margin revenue and improved earnings quality as chip and license income scales.
See why 40 investors see Butterfly Network as 36% undervalued.
Result: Fair Value of $11.17 (UNDERVALUED)
Still, the narrative around Butterfly Network can quickly fray if core POCUS and international trends stay weak, or if future equity issuance heavily dilutes existing holders.
Find out about the key risks to this Butterfly Network narrative.
Another View: Butterfly Network on Revenue Multiples
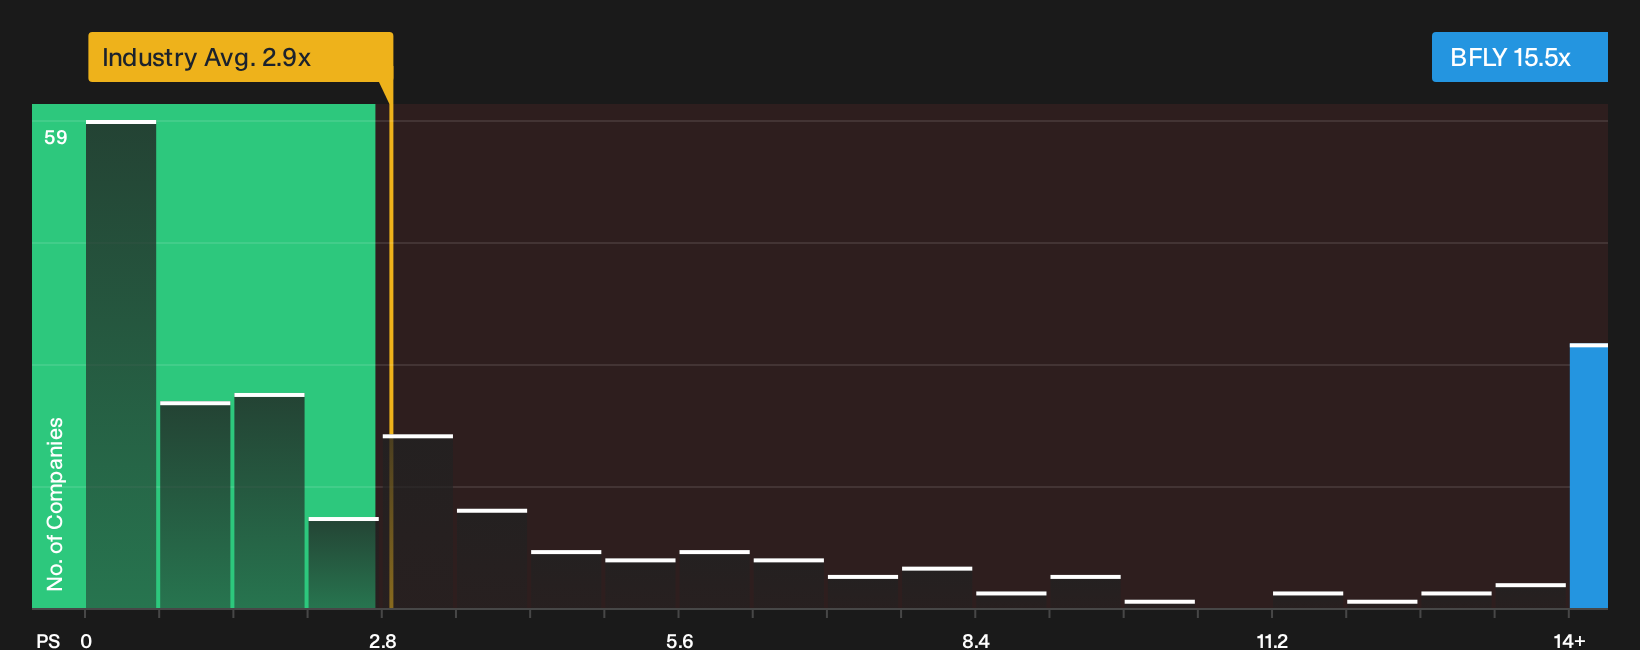
That fair value story paints Butterfly Network as undervalued on future cash flows. On current sales though, the picture flips. The stock trades on a P/S of 15.5x, compared with 2.9x for the wider US Medical Equipment group and 1.5x for peers, while the fair ratio is 3.6x.
This gap means investors are paying several times the revenue multiple that the fair ratio suggests the market could move toward. That raises the bar for execution and leaves less room if growth or sentiment cools. The question is whether you believe Butterfly Network has earned that kind of premium yet or not, and what happens if expectations reset. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Butterfly Network's valuation and risk profile can make the story feel messy, which is exactly why the underlying data matters more than any single take. Move quickly from headline impressions to your own judgment by weighing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Butterfly Network?
If Butterfly Network has your attention, do not stop here. Use targeted stock lists to spot fresh opportunities and pressure test your portfolio thinking.
- Target higher potential in overlooked corners of the market by scanning 19 high quality undiscovered gems before others pay attention.
- Strengthen your core holdings by reviewing the list of solid balance sheet and fundamentals (23 results) and focusing on companies with sturdier financial footing.
- Dial down portfolio stress by checking the 30 resilient stocks with low risk scores and concentrating on businesses with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com