


Environmental engineering firm Tetra Tech (NASDAQ:TTEK) reported calendar Q3 2026 [fiscal Q4 2026] results beating Wall Street’s revenue expectations, with revenue up 15% year on year to $1.34 billion. Revenue guidance for the full year exceeded analysts’ consensus estimates, but next quarter’s guidance of $1.06 billion was less impressive, coming in 1% below expectations. Its GAAP profit of $0.51 per share was 12.1% above analysts’ consensus estimates.
For more on Tetra Tech, read our free full research report.
Tetra Tech Q3 CY2026 highlights:
- Revenue $1.34 billion vs S&P analysts' consensus estimates of $1.14 billion (15% year-on-year growth, 17% beat)
- EPS (GAAP) $0.51 vs analysts' consensus estimates of $0.46 (12.1% beat)
- Adjusted EBITDA $194.5 million vs analysts' consensus estimates of $189.6 million (14.5% margin, 2.6% beat)
- Revenue guidance $1.06 billion at the midpoint for Q4 CY2026, below analysts' consensus estimates of $1.07 billion
- GAAP EPS guidance $0.37 at the midpoint for Q4 CY2026, in line with analysts' consensus estimates
- Operating margin 14.1%, down from 15.6% in the same quarter last year
- Free cash flow margin 3.7%, down from 8.2% in the same quarter last year
- Backlog $4.67 billion at quarter end
- Market capitalization $9.63 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Tetra Tech’s 12.2% annualized revenue growth over the last five years was impressive. Its growth beat the average business services company and shows its offerings resonate with customers.
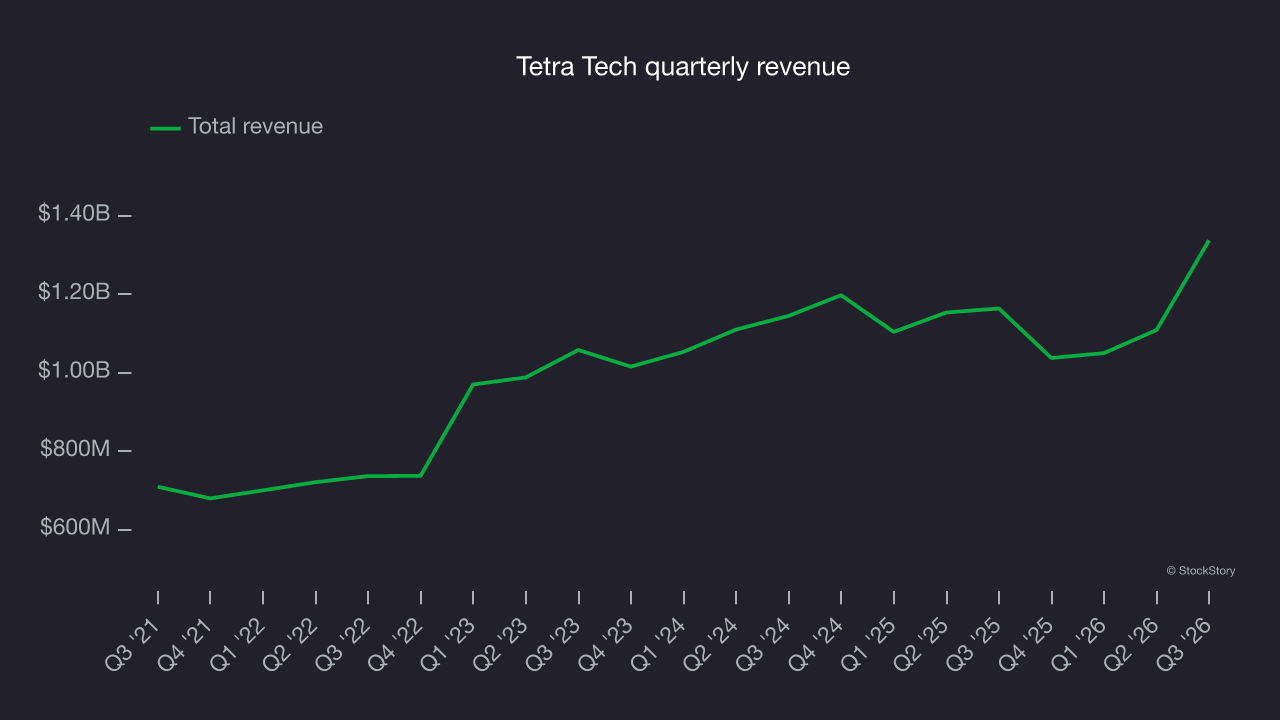
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. Tetra Tech’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 2.4% over the last two years was well below its five-year trend.
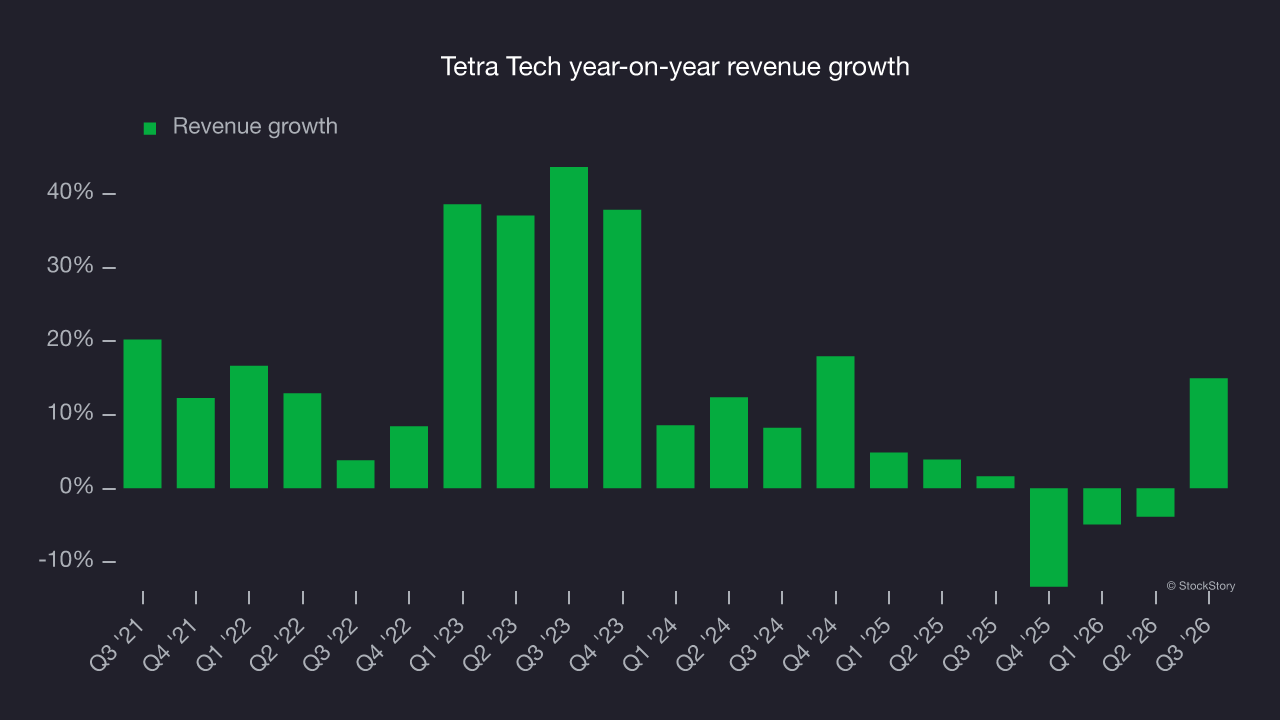
This quarter, Tetra Tech reported year-on-year revenue growth of 15%, and its $1.34 billion in revenue exceeded Wall Street’s consensus estimates by 17%. Management is guiding for a 2.2% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 1.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This underwhelming projection implies its products and services will face some demand challenges.
Adjusted operating margin
Adjusted operating margin is a key measure of profitability. Think of it as net income (the bottom line) excluding the impact of non-recurring expenses, taxes and interest on debt – items less connected to business fundamentals.
Tetra Tech has managed its cost base well over the last five years. It demonstrated healthy profitability for a business services company, producing an average adjusted operating margin of 12.4%.
Looking at the trend in its profitability, Tetra Tech’s adjusted operating margin rose by 1.7 percentage points over the last five years, as its revenue growth gave it operating leverage.
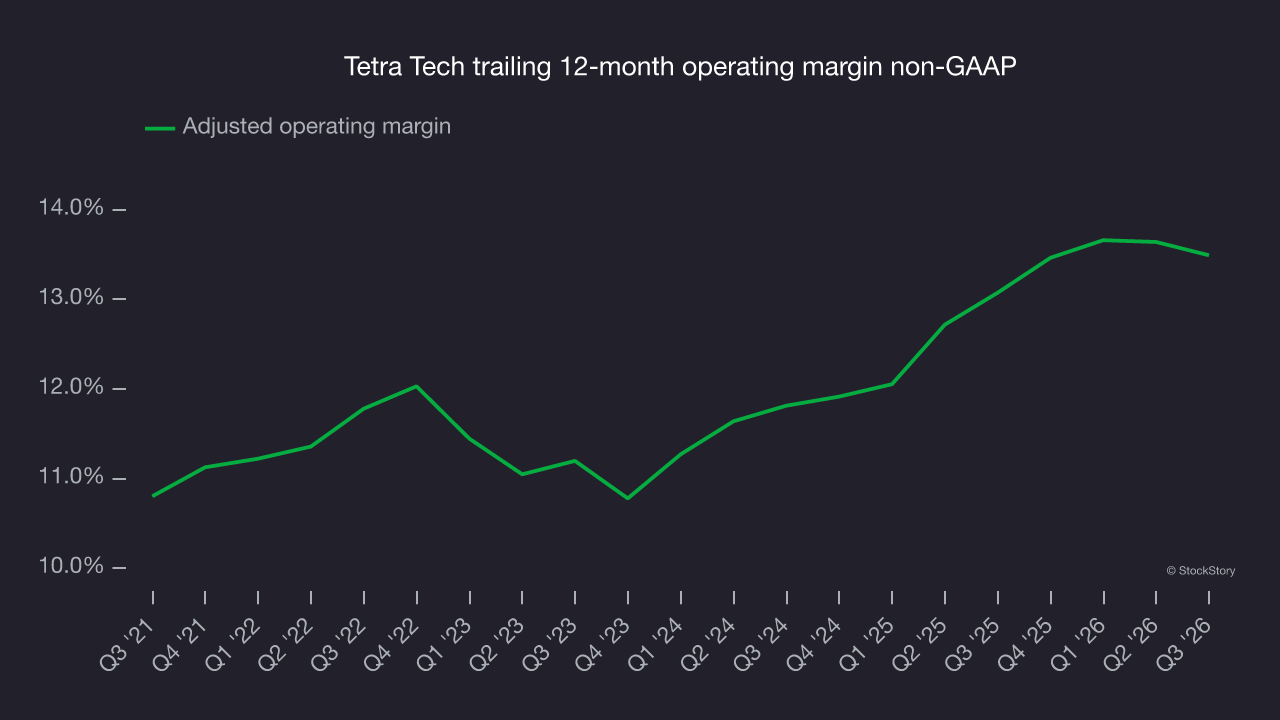
This quarter, Tetra Tech generated an adjusted operating profit margin of 14.1%, in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Tetra Tech’s EPS grew at a 14.7% compounded annual growth rate over the last five years, higher than its 12.2% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
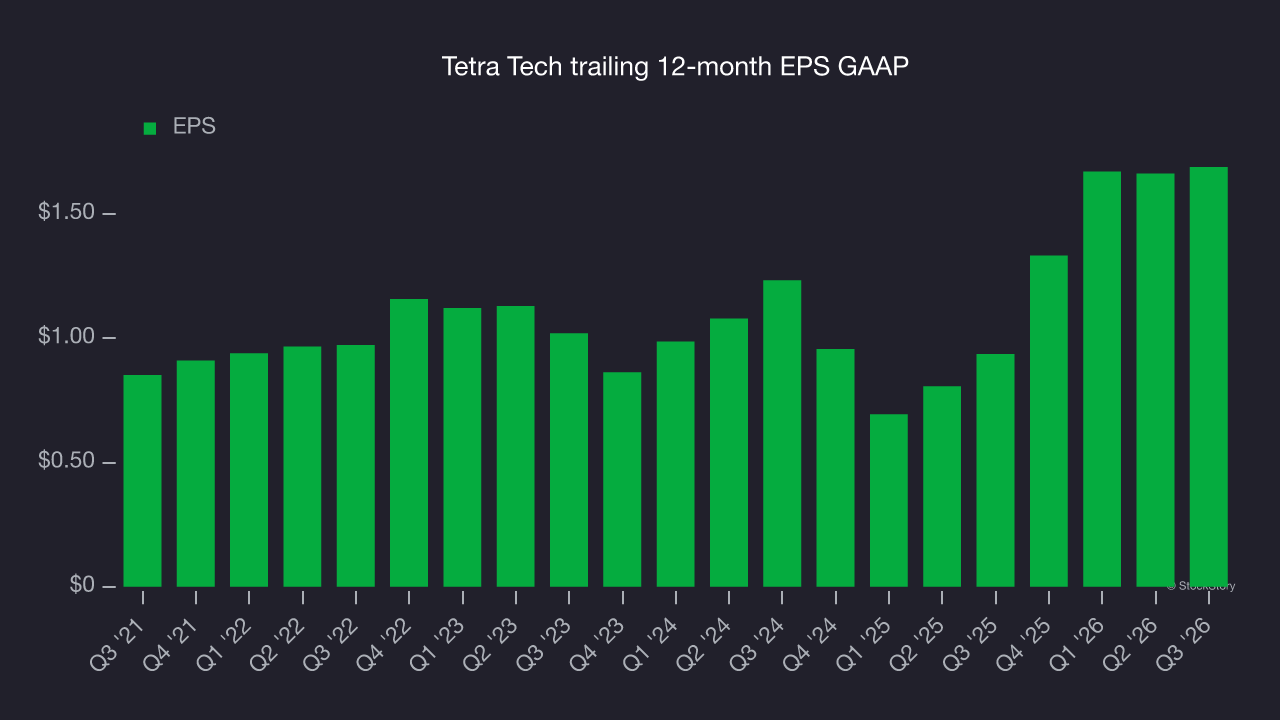
A closer look at Tetra Tech’s earnings helps explain its performance. As noted earlier, Tetra Tech’s adjusted operating margin was flat this quarter but expanded by 1.7 percentage points over the last five years. On top of that, its share count shrank by 6%. These are positive signs for shareholders because improving profitability and share buybacks boost EPS growth relative to revenue growth.
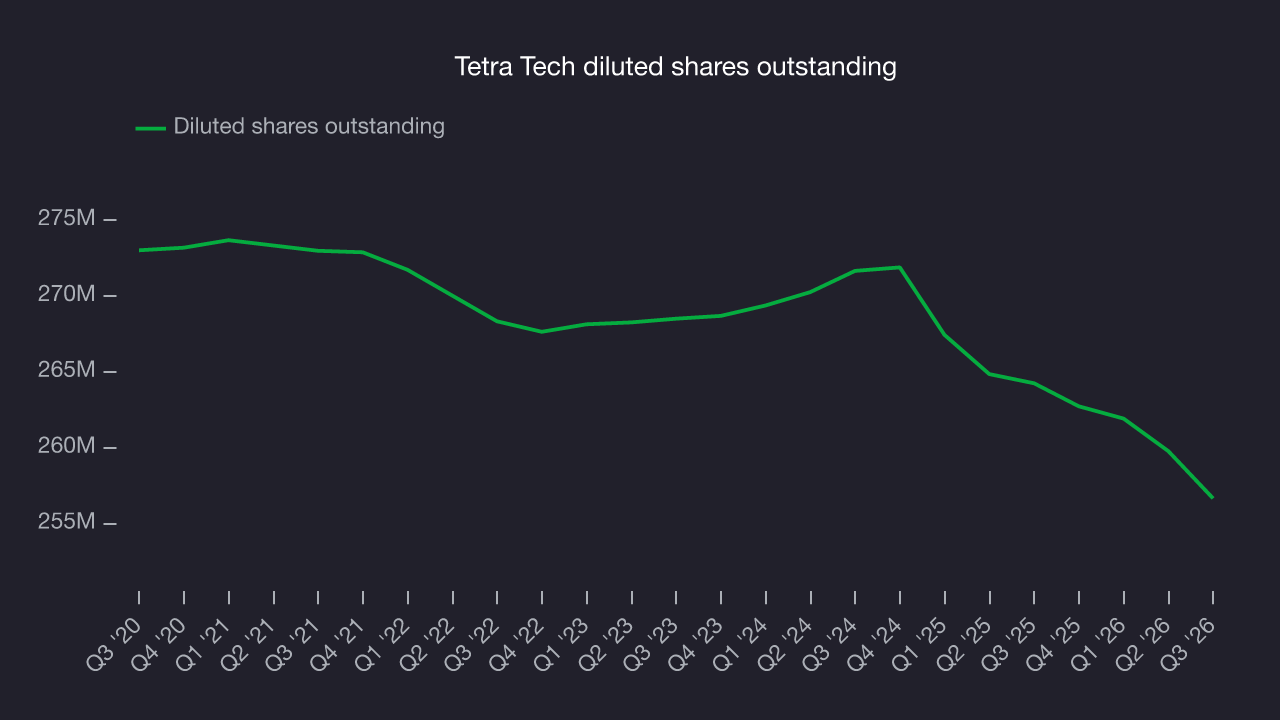
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Tetra Tech, its two-year annual EPS growth of 17% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, Tetra Tech reported EPS of $0.51, up from $0.48 in the same quarter last year. This easily cleared analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Tetra Tech’s full-year EPS to grow 1.4% from $1.69 to $1.71, according to S&P.
Key takeaways from Tetra Tech’s Q3 results
Tetra Tech’s outlook met Wall Street’s expectations, with next-quarter EPS guidance in line with consensus estimates but revenue guidance was slightly below. The quarter itself had key positives: revenue came in well ahead of analysts’ consensus estimates, and EPS also topped expectations. That made for a solid report overall. Shares soared 11.8% to $41.93 immediately after the results.
Assessing Tetra Tech at its current price means looking beyond the latest quarter to its longer-term business quality. Quality, combined with valuation, can help determine whether the stock is a buy. Read the full research report here (it’s free).