


Galaxy Digital has been through a wild few years on the market, yet the stock still comes back to a simple question for investors who care about fundamentals: Is the current US$15.97 share price adequately grounded in what the business is generating from its sales?
- Over the past 3 years the stock has returned about 170.2%, which puts a lot of weight on whether the revenue base can carry that kind of market value.
- News that Formation Securities plans to list tokenized shares of Galaxy Digital on a Solana based venue from 2027 may support expectations for how easily the company’s equity can trade and how investors think about the scalability of its fee and trading related sales.
- The analysts covering Galaxy Digital have run their own numbers. See what analysts think Galaxy Digital's shares could be worth.
The stock’s next move may depend on whether Galaxy Digital’s current price looks aligned with what its sales performance can justify.
If you want to stress test this kind of sales based valuation story beyond Galaxy Digital, it can help to compare it with a wider group of 23 cryptocurrency and blockchain stocks.
Does Galaxy Digital Look Undervalued on Sales?
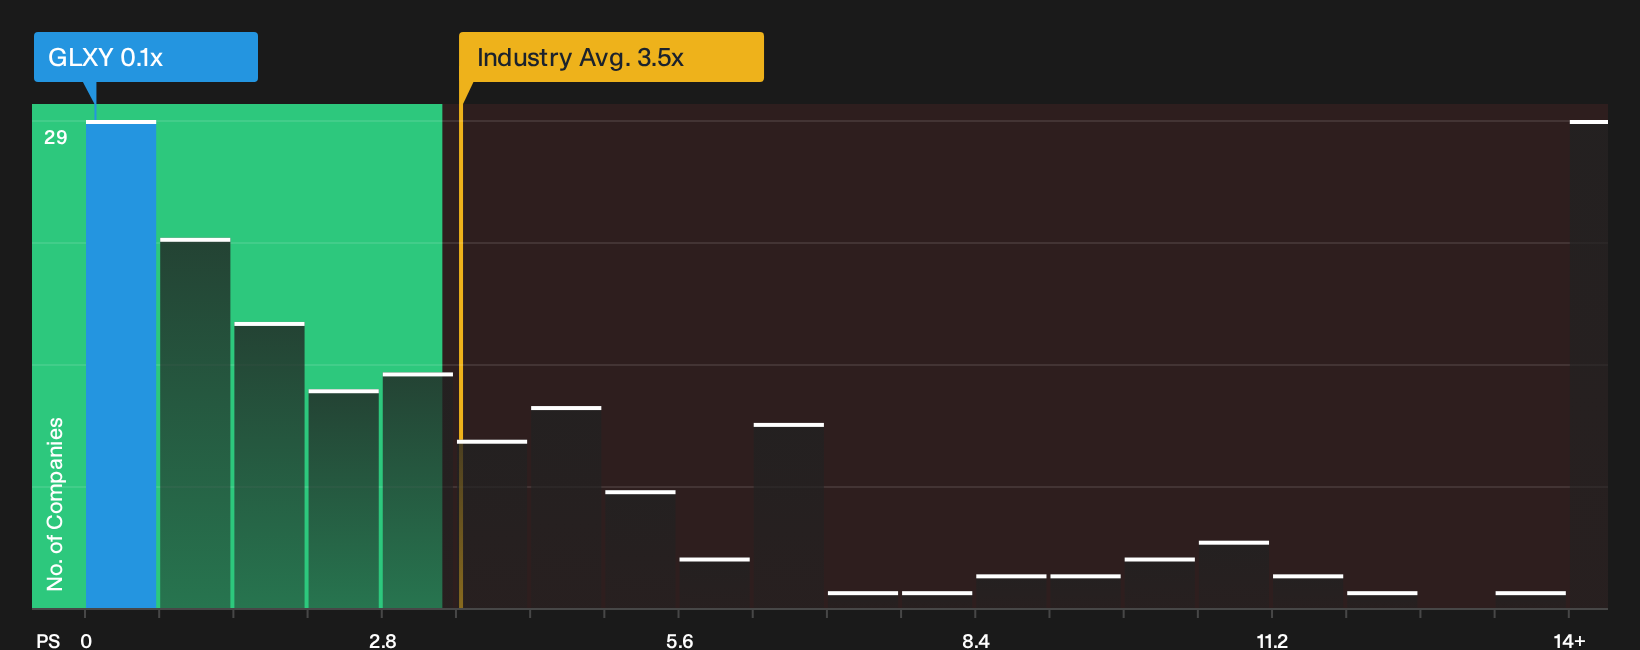
P/S works well for Galaxy Digital because investors often focus on its trading and fee revenue rather than current profits. On this metric, the stock trades on a P/S of about 0.1x, compared with an industry average of roughly 3.5x and a peer group closer to 5.1x. That is a steep gap to how similar capital markets businesses are currently valued on their sales.
The fair multiple implied by the valuation model, which factors in Galaxy Digital’s margins, scale, risk profile and sector, also sits well above the current P/S. Because the share price is acknowledged for tokenized trading on Formation Securities’ planned Solana venue in 2027, the market already knows Galaxy Digital is part of the on chain conversation, yet the present P/S still leaves the stock screening as undervalued on this framework. Explore the numbers behind Galaxy Digital's P/S valuation.
The Galaxy Digital Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Galaxy Digital valuation puzzle leaves off by spelling out which paths for growth, margins and earnings would need to play out for the stock to be worth much more or much less than today’s price. It also turns a single model output into a set of concrete assumptions you can follow over time on the Community page to see whether they still look realistic.
Galaxy Digital splits opinion, with some seeing a discounted onchain and data center platform and others focusing on Texas and funding risks.
Bull case: 55% undervalued
According to the analyst consensus Narrative on Simply Wall St, the upside case leans heavily on how Galaxy Digital scales with institutional crypto and onchain finance.
"Advancements in real-world asset tokenization and the convergence of onchain and offchain capital markets are creating new, durable revenue streams, which Galaxy is actively positioning for through innovation and platform development..."
Discover why this Narrative puts Galaxy Digital at 55% undervalued.
Bear case: 14% overvalued
DanielOliveira, a Simply Wall St Community investor who wrote the Narrative, anchors the cautious view in Texas power approvals, leasing progress and regulatory risk.
"The risk to this view is scope. I found no statement on whether a ban would reach projects already approved or under construction, so approved does not mean immune..."
Explore why this Narrative puts Galaxy Digital at 14% overvalued.
One more Galaxy Digital check that belongs beside the price tag
All the ratios and narratives still leave one big reference point for Galaxy Digital unresolved, which is how professional analysts currently map out the next few years for this business compared with today’s market value. Explore where analysts expect Galaxy Digital to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com