


Markets are being shaken by geopolitical flare ups, policy signals and fresh regulation, and that mix is forcing investors to rethink where reliable dividends might still hold up. Quality income stocks can turn that anxiety into a filter, helping you focus on larger businesses with measured payout habits and healthier balance sheets. This article walks through three dividend stocks exposed to the latest headlines and explains why their reactions to the news could matter for your portfolio decisions.
The stocks covered below are just a sample, and the full screen surfaced 18 more dividend payers with equally compelling stories that are not unpacked in this article. If you want to identify and analyze which of those could fit your income plan, head straight into the Global Quality Dividend Stocks screener.
Nippon Prologis REIT (TSE:3283)
Nippon Prologis REIT is one of the more income-focused picks in the Global Quality Dividend Stocks screener, and the analyst consensus Narrative on Simply Wall St underlines why logistics-heavy cash flows and disciplined capital management are central to its appeal.
Nippon Prologis REIT owns and leases Class A logistics facilities across Japan, earning about ¥68.8 billion from its real estate leasing business and carrying a market value of roughly ¥686.2 billion.
"Further rent reversion on leases that still sit 4% to 5% below market levels, supported by targeted average rent change above 6% for full-year 2026, could add to rental revenue and same-store NOI growth as Nippon Prologis REIT resets more contracts closer to market and replacement rent levels."
Changes in the assumptions around how quickly contract terms reset in that environment, even relatively small ones, are worth monitoring closely.
Those reset assumptions are exactly where the story gets interesting, and the full narrative for Nippon Prologis REIT unpacks how accelerating rent shifts, funding costs and tenant demand all intersect.

CT Real Estate Investment Trust (TSX:CRT.UN)
CT Real Estate Investment Trust owns a CA$4.4b portfolio of about 380 net lease retail properties across Canada. It earns roughly CA$628 million from managing primarily single tenant sites. Most locations are leased to Canadian Tire, giving CT REIT a dividend focused profile that fits the Global Quality Dividend Stocks theme.
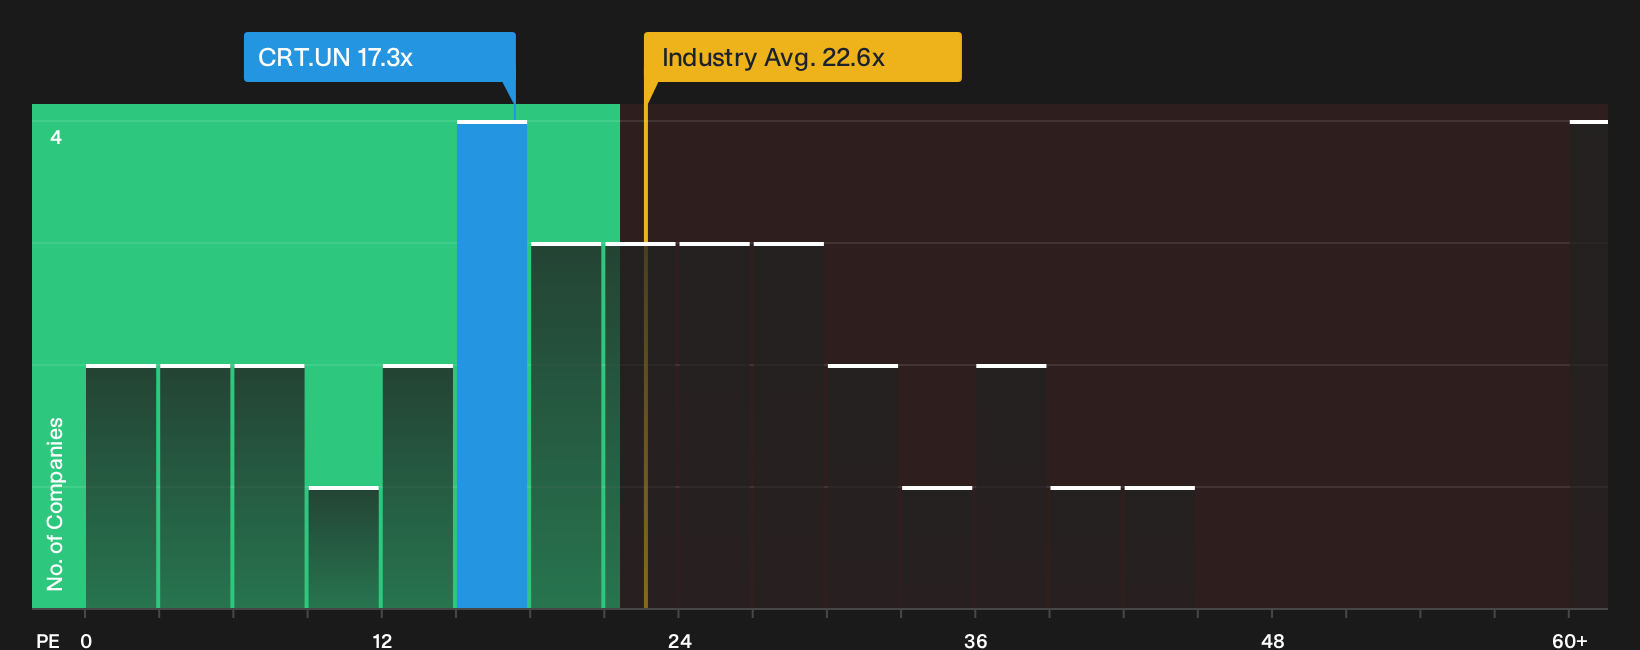
Income investors looking for steady distributions may gravitate to CT Real Estate Investment Trust because it combines a sizeable CA$4.4b footprint with long leases, high occupancy and a lower P/E than many Retail REIT peers. The appeal hinges on how pressure on debt costs and cash flow coverage resolves for this landlord focused on predictable payouts.
How that pressure resolves is exactly what the 3 key rewards and 2 important warning signs (1 is major!) hints at, revealing where CT Real Estate Investment Trust could surprise income investors next.
Mapletree Pan Asia Commercial Trust (SGX:N2IU)
Mapletree Pan Asia Commercial Trust gives this dividend screen a Pan-Asia angle, with income-focused commercial properties across key Asian hubs and a market cap of about S$6.1b. Revenue leans on VivoCity in Singapore at S$262 million and MBC at S$224 million, with added contributions from Festival Walk in Hong Kong at S$170 million and other China, Japan and Singapore assets.
The analyst consensus Narrative on Simply Wall St frames Mapletree Pan Asia Commercial Trust as a way to tap large, income-producing assets in Asia’s gateway cities while still caring about balance sheet resilience and dividend visibility.
"The maintenance of 71.5% fixed rate debt and hedging of about 95% of foreign-sourced distributable income into S$ as at 31 March 2026 gives Mapletree Pan Asia Commercial Trust clearer visibility on financing and FX costs, which supports more stable distributable income and earnings."
What happens if a single pressure point in its overseas portfolio shifts faster than expected will be crucial for how dependable those payouts feel.
That single fault line can reshape how stable those distributions feel, and the full narrative for Mapletree Pan Asia Commercial Trust lays out where income strength could be accelerating or masking new risks.

Seeking Fresh Alternatives Before They Fly
Market stories move fast and fresh opportunities do not wait. Spot potential breakout income and growth ideas before the crowd while it matters. Get in early.
- Chase durable income potential by scanning hand picked high yield payers in the 26 dividend fortresses before their yields get caught dropping as prices reset.
- Track rapid shifts in digital finance by reviewing curated companies in the 23 cryptocurrency and blockchain stocks while many of them are still under the radar for now.
- Target fast emerging automation demand by assessing focused industrial plays in the 87 robotics and automation stocks before momentum stories start flying on every headline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com