


Plug Power has seen its share price fall sharply over recent years, which puts extra focus on whether the current valuation can still be explained by the revenue the business is generating. With sentiment swinging around clean energy and fresh headlines arriving, the key issue is how today’s market value lines up against Plug Power’s sales base.
- Over the past 5 years the stock has declined 96.8%, which puts long term holders squarely on the question of what portion of Plug Power’s revenue story is already reflected in the share price.
- Recent updates highlight higher revenue and narrower losses for Plug Power, which can influence how investors weigh its sales today against expectations for future profitability and cash needs.
- Your read on Plug Power is one view; the desks covering it have another. See what analysts think Plug Power's shares could be worth.
The issue now is whether Plug Power’s current share price is justified by its sales when compared with the Fair Ratio benchmark.
If Plug Power’s steep 5 year share price decline has you reassessing where you start your research, it can help to run the same sales focused lens across 32 high quality undervalued stocks.
Is Plug Power Getting Expensive on Sales?
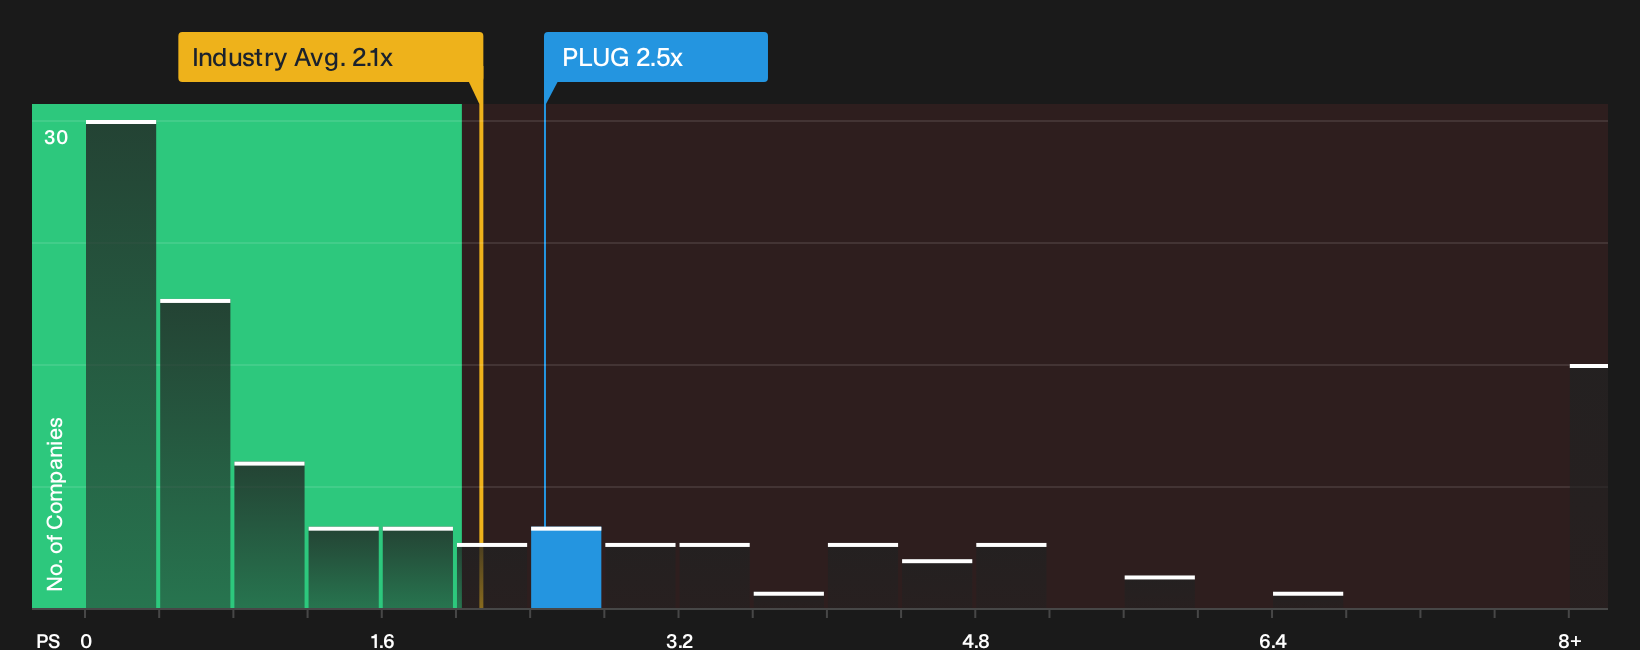
P/S suits Plug Power because profit is still negative while revenue is already meaningful. On this lens the stock trades on a P/S of about 2.5x, compared with an Electrical industry average near 2.1x and a peer group around 2.1x as well. That puts the share price at a premium to what investors are currently paying for similar levels of sales across the sector.
Recent Q3 2026 news around higher revenue and improved margins has helped rebuild confidence, yet the P/S still screens as overvalued against the Fair Ratio model, which adjusts for Plug Power’s growth profile, profitability path, size and risk. Because the Fair Ratio sits well below the current P/S, the framework is heavily penalising ongoing losses and cash burn, so the signal is more of a warning flag on how richly those sales are priced than a precise target level. Explore the numbers behind Plug Power's P/S valuation.
The Plug Power Narrative: What Would Justify Today's Price?
Plug Power’s valuation puzzle raises a sharper question that Simply Wall St Narratives try to answer: what path for its growth, margins and earnings would need to play out for the stock to be worth significantly more or less than it is today? Each scenario ties its figure to a clear view on how Plug Power’s growth, profitability and risk profile might evolve, and gives you a reference point you can revisit as fresh numbers come through on the Community page.
Bulls and bears looking at Plug Power today are reading the same cost cuts and project list in very different ways.
Bull case: 60% undervalued
According to the analyst consensus Narrative on Simply Wall St, the upside view leans heavily on execution, cost resets and embedded demand.
"Company wide cost actions under Project Quantum Leap, including the shift from very negative to roughly breakeven gross margin in recent quarters, OpEx reductions of about 50% and lower cash usage, point to a structural reset in Plug Power’s cost base…"
Discover why this Narrative puts Plug Power at 60% undervalued.
Bear case: 81% overvalued
The bearish analyst Narrative on Simply Wall St focuses on whether those same projects and refreshes actually translate into durable earnings and cash generation.
"The cancellation of the 100 MW green hydrogen plant at the Port of Antwerp after the loss of a US$1.66b loan guarantee, together with the related €13.6 million write off, shows that large European projects can still fail at a late stage…"
Explore why this Narrative puts Plug Power at 81% overvalued.
One more Plug Power cross check beyond the current price tag
Price multiples and storylines only go so far. The next piece is where sector analysts currently think Plug Power could be a few years from now, and how that compares with what the market pays today. Explore where analysts expect Plug Power to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com