


Rio Tinto Group (LSE:RIO) has approved a $144 million spend to advance the next phase of its Resolution Copper project in Arizona, and has also begun early production at the Sal de Vida lithium operation in Argentina.
Rio Tinto Group’s £63.85 share price has recently pulled back, with the 30 day share price return down 10.6% and the 90 day move down 10.9%, even though the year to date share price return is 6.7% and the 5 year total shareholder return is 102.4%. This suggests the stock has positive long term momentum while near term sentiment has cooled despite progress on copper and lithium projects.
Scan beyond Rio Tinto Group and explore other miners tied to electrification and commodities demand with our curated list of 16 top copper producer stocks in one place.
After a 10% slide over three months, alongside a solid multi year return profile and fresh copper and lithium projects moving ahead, does Rio Tinto Group still offer a payoff that justifies taking equity risk at £63.85?
Most Popular Narrative: 15% Undervalued
At a £63.85 share price, Rio Tinto Group trades below the analyst consensus Narrative fair value of £75.37, based on a 9.7% discount rate and detailed revenue and earnings assumptions from the analyst consensus Narrative on Simply Wall St.
The main thing that has to go right is continued delivery of the productivity and cost reduction program while executing large projects like Simandou, Oyu Tolgoi, lithium developments and Kangwinan without major ESG, safety or social licence setbacks.
This can structurally reduce unit costs and support wider net margins over time if volumes are maintained.
See why 299 investors see Rio Tinto Group as 15% undervalued.
Result: Fair Value of £75.37 (UNDERVALUED)
Still, Rio Tinto Group’s thesis leans heavily on the smooth delivery of big projects and on avoiding ESG or safety setbacks that could slow volumes and lift costs.
Find out about the key risks to this Rio Tinto Group narrative.
Another Angle On Rio Tinto Group’s Valuation
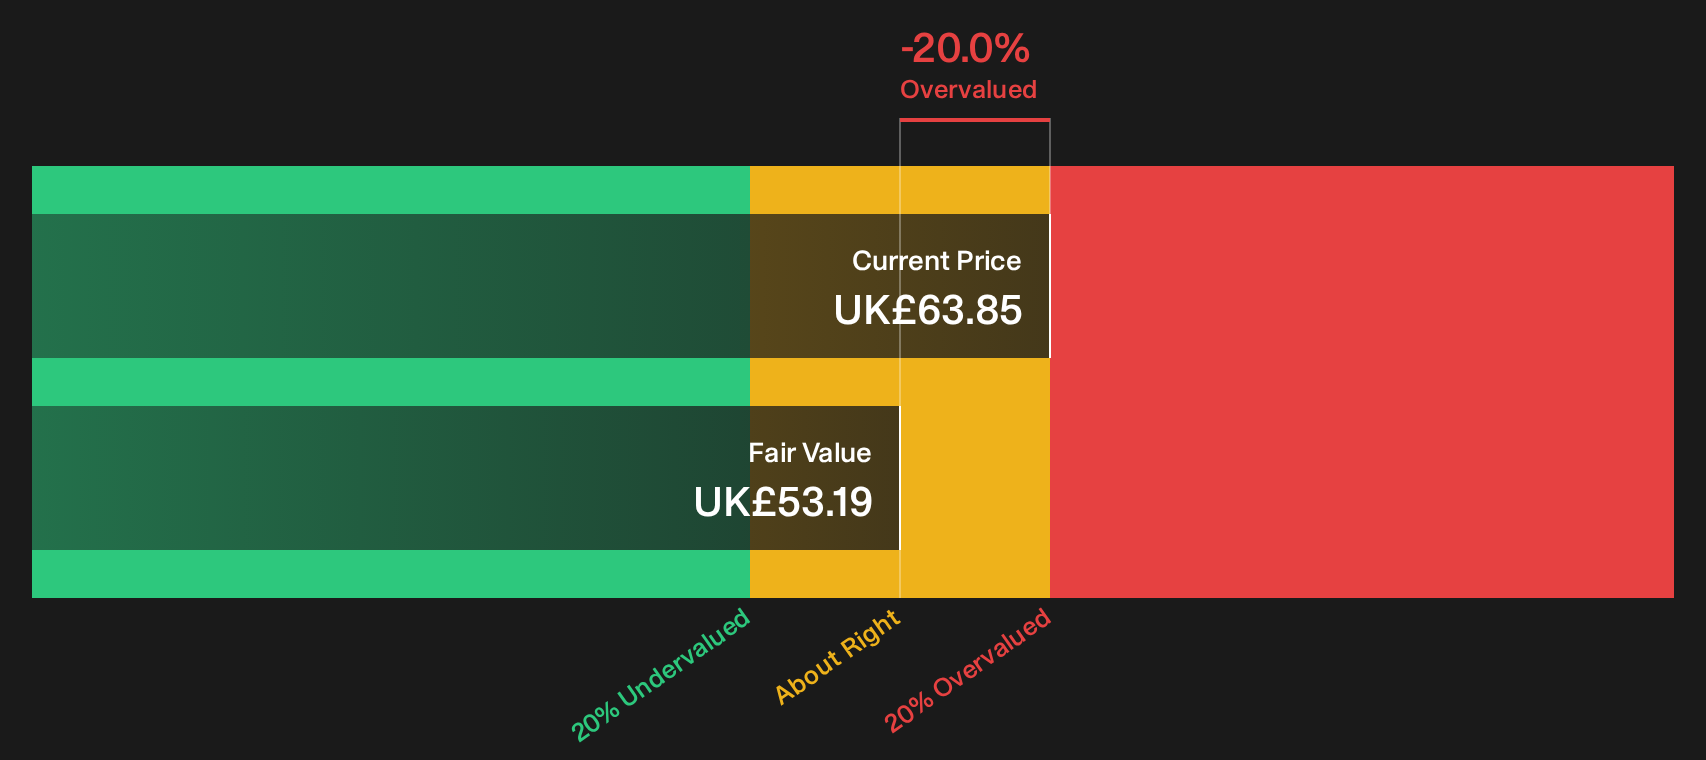
The analyst narrative points to Rio Tinto Group trading below a fair value of £75.37, yet the SWS DCF model tells a different story. On that cash flow view, the shares at £63.85 sit above an estimated value of £53.19, which screens as overvalued rather than cheap.
Two methods, one stock, and conflicting answers raise a simple question for you as an investor: do you anchor on projected cash flows or on the earnings based Narrative that frames Rio Tinto Group as 15% undervalued?
To understand how this cash flow view is built and what would need to change for the DCF output to move closer to the analyst Narrative, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals on Rio Tinto Group so far, and still not sure where you land on it? Move quickly, review the underlying data, and weigh both the upside and the downside by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Rio Tinto Group?
If Rio Tinto Group has you thinking harder about where to put fresh capital, broaden your watchlist with ideas built from clear fundamentals and disciplined filters.
- Target resilience first and put capital to work in businesses that prioritize robust finances using our list of solid balance sheet and fundamentals (9 results).
- Hunt for quality at a sensible entry point and line up opportunities that may trade below their underlying strength with the 17 high quality undervalued stocks.
- Build a watchlist that works while you sleep by focusing on steady income payers featured in the 4 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com