


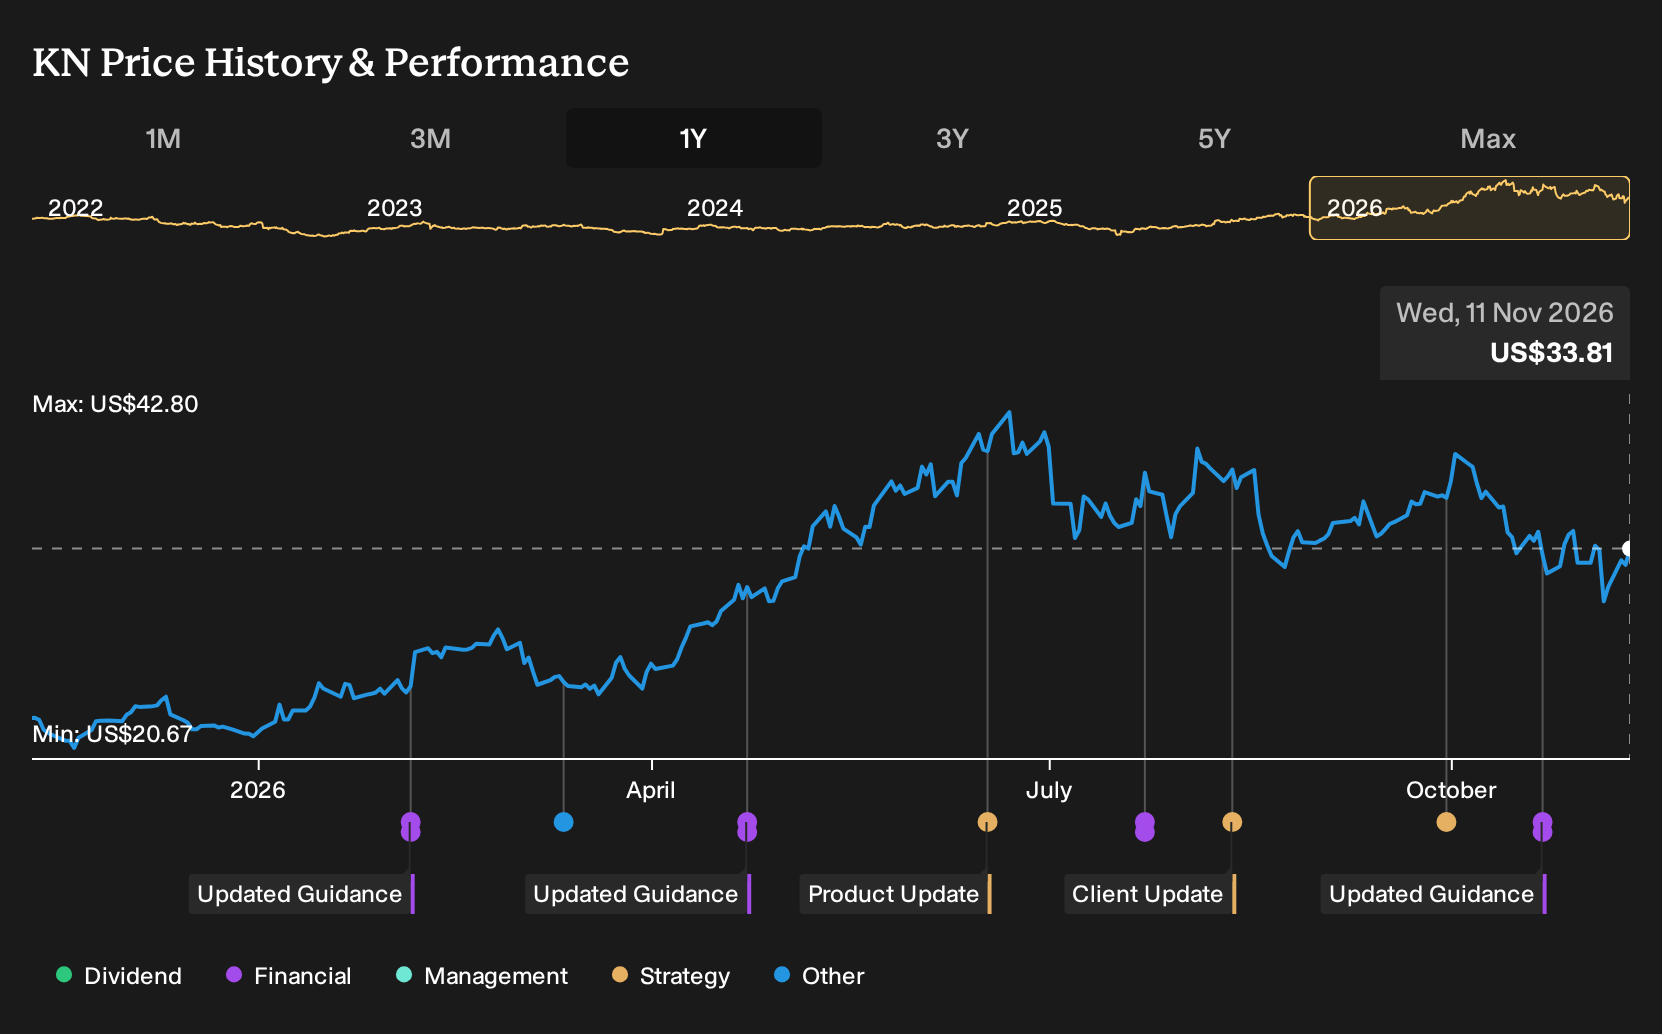
- Knowles recently received an upgrade to a Zacks Rank #1 rating after analysts lifted earnings estimates by 7.8% over the past three months. This signals a more constructive view of its future profitability.
- The sharper earnings outlook points back to Knowles' operating engine, where demand for higher value components and stronger fundamentals are supporting analysts' improved forecasts rather than sentiment alone.
- We will now look at how Knowles' upgraded earnings outlook reshapes the existing investment narrative built around utilization and margins.
Scan other earnings driven ideas that are moving on refreshed forecasts by running the 19 high quality undiscovered gems alongside your work on Knowles.
Knowles Investment Narrative Recap
To own Knowles, you need to be comfortable with a very operational story. The analyst consensus Narrative on Simply Wall St ties the equity case to keeping factory utilization healthy, while custom capacitors, RF filters and medtech audio parts support margins and cash generation. The earnings upgrade leans in that direction, since it reflects confidence in the existing engine rather than a new theme.
The key near term swing factor is still how efficiently Knowles runs its Precision Devices facilities as newer platforms scale. Ramp costs, scrap on the specialty film line and mix toward lower margin work remain the biggest operational risk. The revised earnings outlook does not remove that risk; it just suggests analysts see more cushion.
Among the developments already in focus, the large specialty film energy order is the most relevant piece to keep in mind alongside the earnings upgrade. That US$75 million plus program is now fully ramped with another 6 to 7 quarters of deliveries, and management has been targeting better yields and more automation on that line.
If that energy contract stays on schedule and utilization holds up across attenuators, inductors, Micro Solutions and RF filters, the operational backdrop that underpins the stronger earnings view remains intact. Any quality issues, schedule slips or extra spending on that facility or on other growth platforms would cut into the margin story that analysts have just become more optimistic about.
What The Upgraded Earnings Path Implies For Knowles
Knowles' current analyst framework points to US$880.3 million in revenue and US$128.0 million in earnings by 2029. That outlook is based on an assumed 9.7% yearly increase in revenue and an earnings increase of about US$51.6 million from the US$76.4 million reported today.
Uncover why Knowles' fair value indicates a 30% potential upside to its current price before other investors close that gap.
Exploring Other Perspectives
One alternate view on Knowles leans heavily on specialty film risk. Those bearish analysts were assuming about US$842.9 million of revenue and US$126.4 million of earnings by 2029, and saw a lower 29.8x P/E as more realistic. You can use the fresh Zacks upgrade to test how far that cautious story might shift instead.
Explore 3 other Knowles fair value estimates, including one that suggests as much as 58% downside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Knowles research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Knowles. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Knowles' overall financial health at a glance.
Looking for more investment ideas beyond Knowles?
If the Knowles story has sharpened how you think about earnings quality and utilization, you can use that same lens to scan a wider watchlist with the Simply Wall St Screener.
- If you want potential mispricings with solid fundamentals, start with a focused set of 32 high quality undervalued stocks that screen for quality and valuation together.
- If capital preservation sits higher on your agenda, narrow your universe to 30 resilient stocks with low risk scores that score well on financial strength and risk metrics.
- If balance sheet resilience is your priority, build a shortlist from the list of solid balance sheet and fundamentals (23 results) and keep your attention on businesses with cleaner finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com