


- Arch Capital Group recently presented at the Evercore Insurance Conference and reported that board member Moira Kilcoyne resigned in late October without any disagreement on operations or governance.
- The conference appearance and orderly board change occur as Arch Capital Group reports underwriting profitability, higher investment income and active capital returns that support its current operating profile.
- This article reviews how Arch Capital Group's investment narrative relates to its recent underwriting results highlighted around the Evercore conference.
Scan beyond Arch Capital Group and see which insurers share similar underwriting discipline and boardroom stability with the hand picked 30 resilient stocks with low risk scores.
Arch Capital Group Investment Narrative Recap
To own Arch Capital Group, you need to be comfortable with a story built on underwriting discipline, cycle management and capital allocation more than on headline revenue growth. The analyst consensus Narrative on Simply Wall St expects revenue and earnings to decline over the next few years, so the short term focus falls on how well management can keep combined ratios and returns resilient as pricing pressure builds.
The biggest swing factor is how effectively Arch Capital Group keeps shifting toward casualty, mortgage and fee rich lines while pulling back from softer property catastrophe business. The key risk is a cluster of large catastrophe or mortgage credit losses that land just as the market softens, which could quickly squeeze margins even if the recent news itself is not especially disruptive.
The recent confirmation that Moira Kilcoyne’s board resignation did not involve a dispute on operations or governance matters is relevant here. You want boardroom change to be boring when the real work is in underwriting, reinsurance mix and mortgage risk, and this update points to continuity in how the firm is overseen.
That kind of stability matters if Arch Capital Group is going to execute on the cycle management playbook described in the analyst consensus Narrative on Simply Wall St. Reweighting away from property catastrophe, investing in data and AI, expanding U.S. middle market and transactional liability, and continuing disciplined buybacks all rely on consistent oversight, not board level friction.
What The Analyst Case Implies For Arch Capital Group
Arch Capital Group's narrative projects US$15.1b revenue and US$3.2b earnings by 2029. This lines up with analysts assuming revenue will decline 7.8% per year and earnings will fall by US$1.5b from US$4.7b today.
Uncover why Arch Capital Group's fair value suggests that revenue and earnings expectations are roughly in line with its current price.
Exploring Other Perspectives
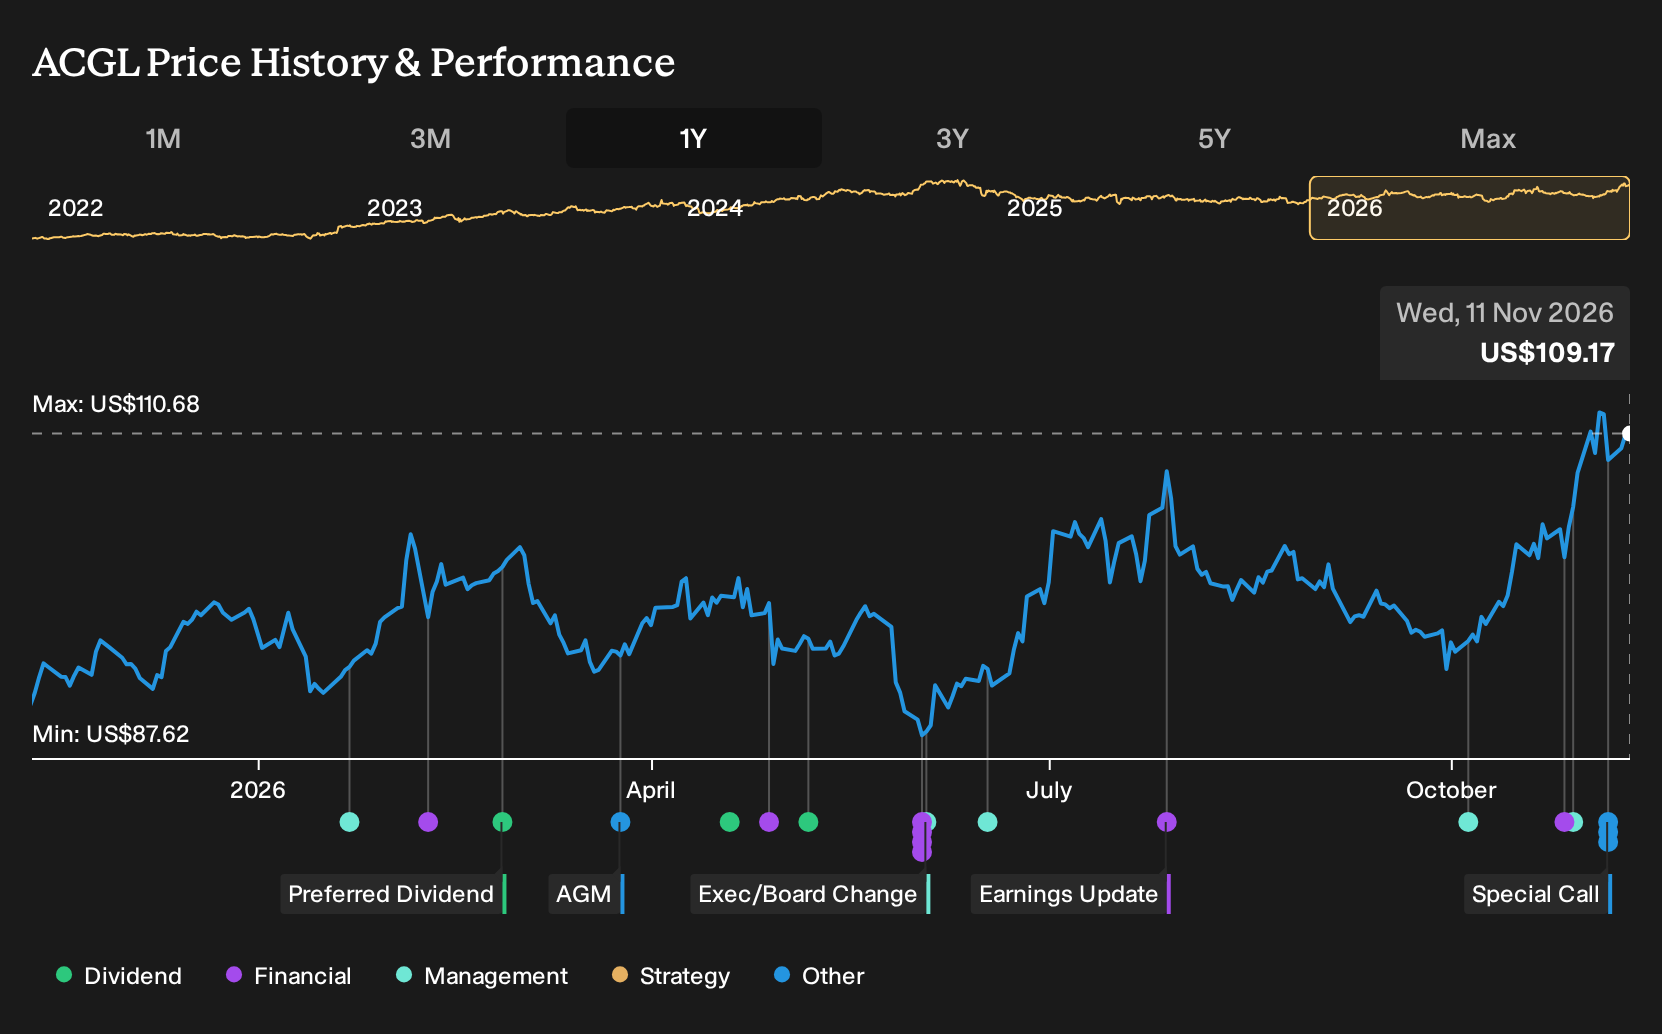
Two fair value estimates from the Simply Wall St Community span roughly US$112 to US$233 per share, which already shows how far private views on Arch Capital Group can stretch. When you set that against softening insurance markets and ongoing cycle management efforts, you get a reminder that opinions vary widely and are worth comparing directly.
Explore another Arch Capital Group fair value estimate, including one that suggests as much as 113% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own research and judgment.
- A great starting point for your Arch Capital Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arch Capital Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arch Capital Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Arch Capital Group?
Once you have formed a view on Arch Capital Group, it often helps to compare it with a wider set of companies that share similar qualities or offer very different payoffs. The Simply Wall St Screener can surface those opportunities for you in a structured way.
- If you want to focus on companies where balance sheet resilience takes center stage, start with this curated list of solid balance sheet and fundamentals (23 results) that filters for financial strength and fundamental support.
- For investors who care most about quality businesses trading below their estimated worth, the 32 high quality undervalued stocks can highlight candidates where fundamentals and pricing may be out of sync.
- If you prefer to hunt for less crowded situations with strong underlying metrics, the 19 high quality undiscovered gems can point you toward under-the-radar stocks that still pass robust quality checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com