


Susquehanna Financial Group recently highlighted Globant (NYSE:GLOB) as an AI era beneficiary, pointing to its AI Pods model, output based pricing and growing recurring AI revenue despite flat sales and reduced guidance.
Globant’s recent AI spotlight has landed after a sharp move in the share price, with a 30 day share price return of 27.2% and a 90 day gain of 13.05%. However, the year to date share price return is still down 26.53% and the 1 year total shareholder return has fallen 24.98%.
Track Globant’s AI re-rating and compare it with hand-picked peers by scanning 41 AI small caps that are also chasing recurring revenue and output-based pricing in this theme.
Globant now has an AI heavy model that many investors like, yet the share price only recently bounced off a steep multi year slide. Is this still a strong business being valued cautiously, or already priced for an AI premium?
Most Popular Narrative: 10.2% Undervalued
Against Globant’s last close at $46.34, the analyst consensus Narrative on Simply Wall St anchors fair value at $51.59, implying a modest discount that hinges on AI driven margin gains rather than rapid top line expansion.
The main thing that has to go right is that Globant scales its higher-margin AI Pods and Glob.AI model quickly enough to offset pressure from FX headwinds, softer legacy demand, and legal scrutiny of its disclosures and revenue recognition.
The current valuation, with shares moving from around US$350 in 2021 to roughly US$30 to US$40 in mid 2026 and the company buying back stock against what management describes as a double digit normalized free cash flow yield, implies the market prices in a low bar for Globant and leaves room if AI-led execution affects sentiment on the share price.
See why 56 investors see Globant as 10% undervalued.
Result: Fair Value of $51.59 (UNDERVALUED)
Still, the Globant thesis leans on AI, even as revenue growth slows and legal questions over disclosures and revenue recognition continue to hang over the story.
Find out about the key risks to this Globant narrative.
Another View: Globant Through A Cash Flow Lens
Globant may look attractively priced on analyst targets, yet the Simply Wall St DCF model points in the opposite direction. On that cash flow view, the current $46.34 share price sits above an estimated value of $40.57, which frames the stock as overvalued rather than discounted. Which story do you think holds more weight right now?
Look into how the SWS DCF model arrives at its fair value.
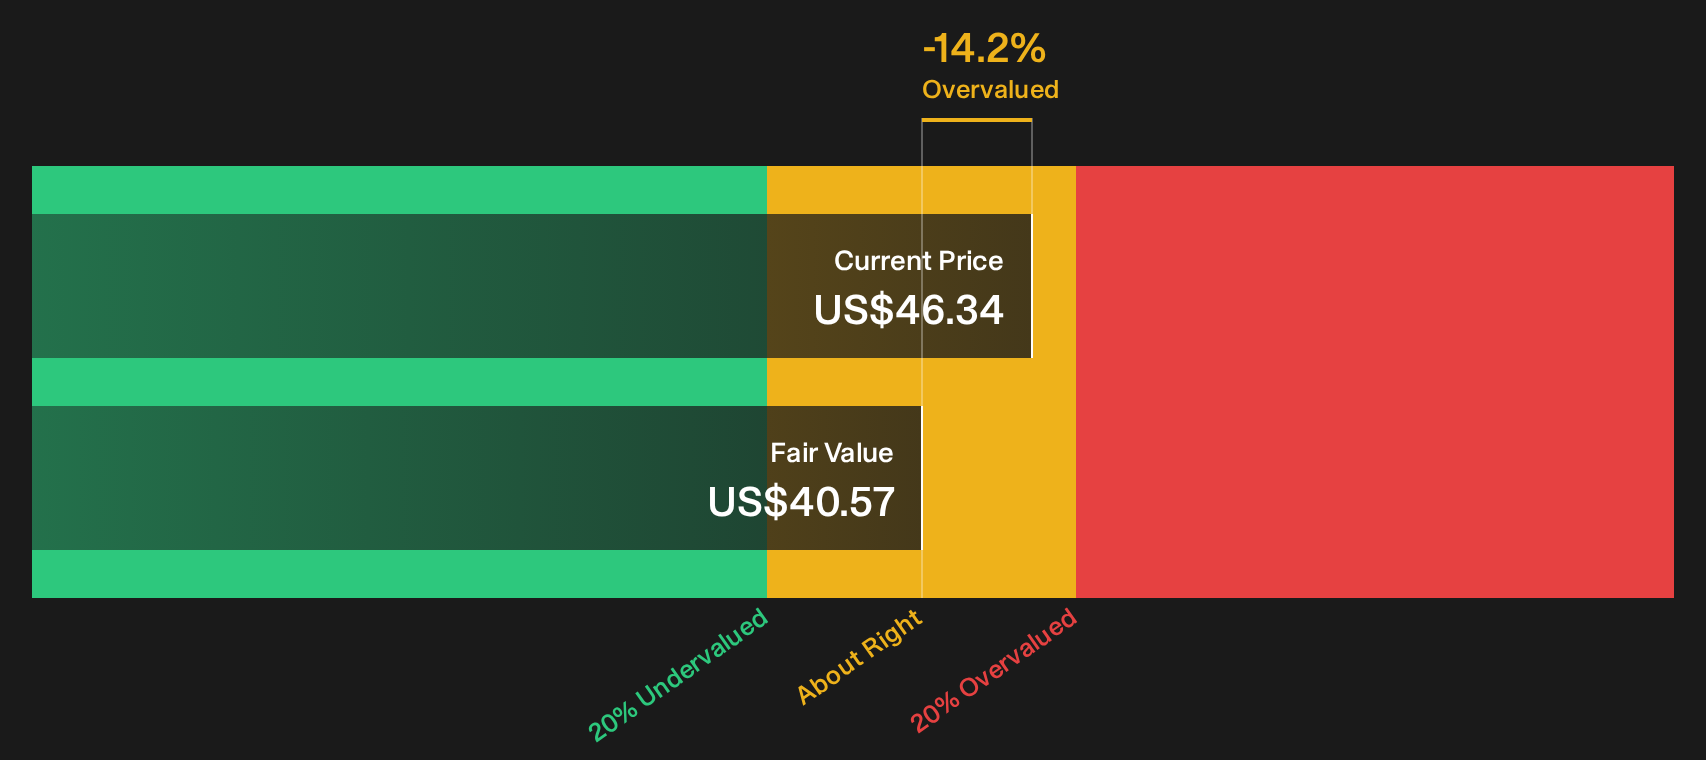
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Globant for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Globant can be useful, since they push you to inspect the numbers yourself and decide how convincing the story really feels. If you want a quick snapshot of both sides before you decide where you land, start with the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Globant?
Do not stop at one stock. Use Globant as a reference point, then scan wider so your portfolio reflects more than a single AI driven story.
- Target potential mispricing by running through our hand picked group of quality candidates in the 32 high quality undervalued stocks.
- Protect the downside first and hunt for steadier performers using the 30 resilient stocks with low risk scores so short term swings do not dominate your returns.
- Spot underfollowed opportunities early by combing through the 20 high quality undiscovered gems before the crowd catches on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com