


- Semiconductor Manufacturing International reported earnings for the nine months ended September 30, 2026, with revenue of CNY 60,618.05 million and net income of CNY 7,314.2 million, compared with CNY 49,510.42 million and CNY 3,818.07 million respectively a year earlier.
- The wider gap between revenue and net income compared with the prior year suggests improved cost control or a richer product mix in Semiconductor Manufacturing International's operations.
- Investors may monitor how Semiconductor Manufacturing International's higher nine-month net income influences the existing investment narrative around capacity expansion.
Scan how Semiconductor Manufacturing International's latest earnings compare with peers by reviewing hand picked 53 AI infrastructure stocks shaping the backbone of chip production and compute demand.
Semiconductor Manufacturing International Investment Narrative Recap
To own Semiconductor Manufacturing International, you need to be comfortable with a simple idea: heavy investment in new fabs and capacity only makes sense if demand and pricing stay firm enough to keep those lines busy and margins intact. The latest nine month earnings, with higher revenue and net income than a year earlier, support that story but do not remove the risk that pricing power softens again.
The near term swing factor is whether utilization and blended selling prices hold up as more capacity comes online. The biggest current risk sits on the cost side. Management already flagged faster depreciation and negative free cash flow after capex, so any cooling in volumes or wafer pricing could pressure earnings and cash generation at the same time.
The analyst consensus Narrative on Simply Wall St leans heavily on capacity expansion and high utilization as key drivers. The new nine month figures, which show stronger net income alongside higher sales, line up with that view that SMIC is currently filling fabs at economically sensible levels, even with large capital expenditure and rising depreciation already in the numbers.
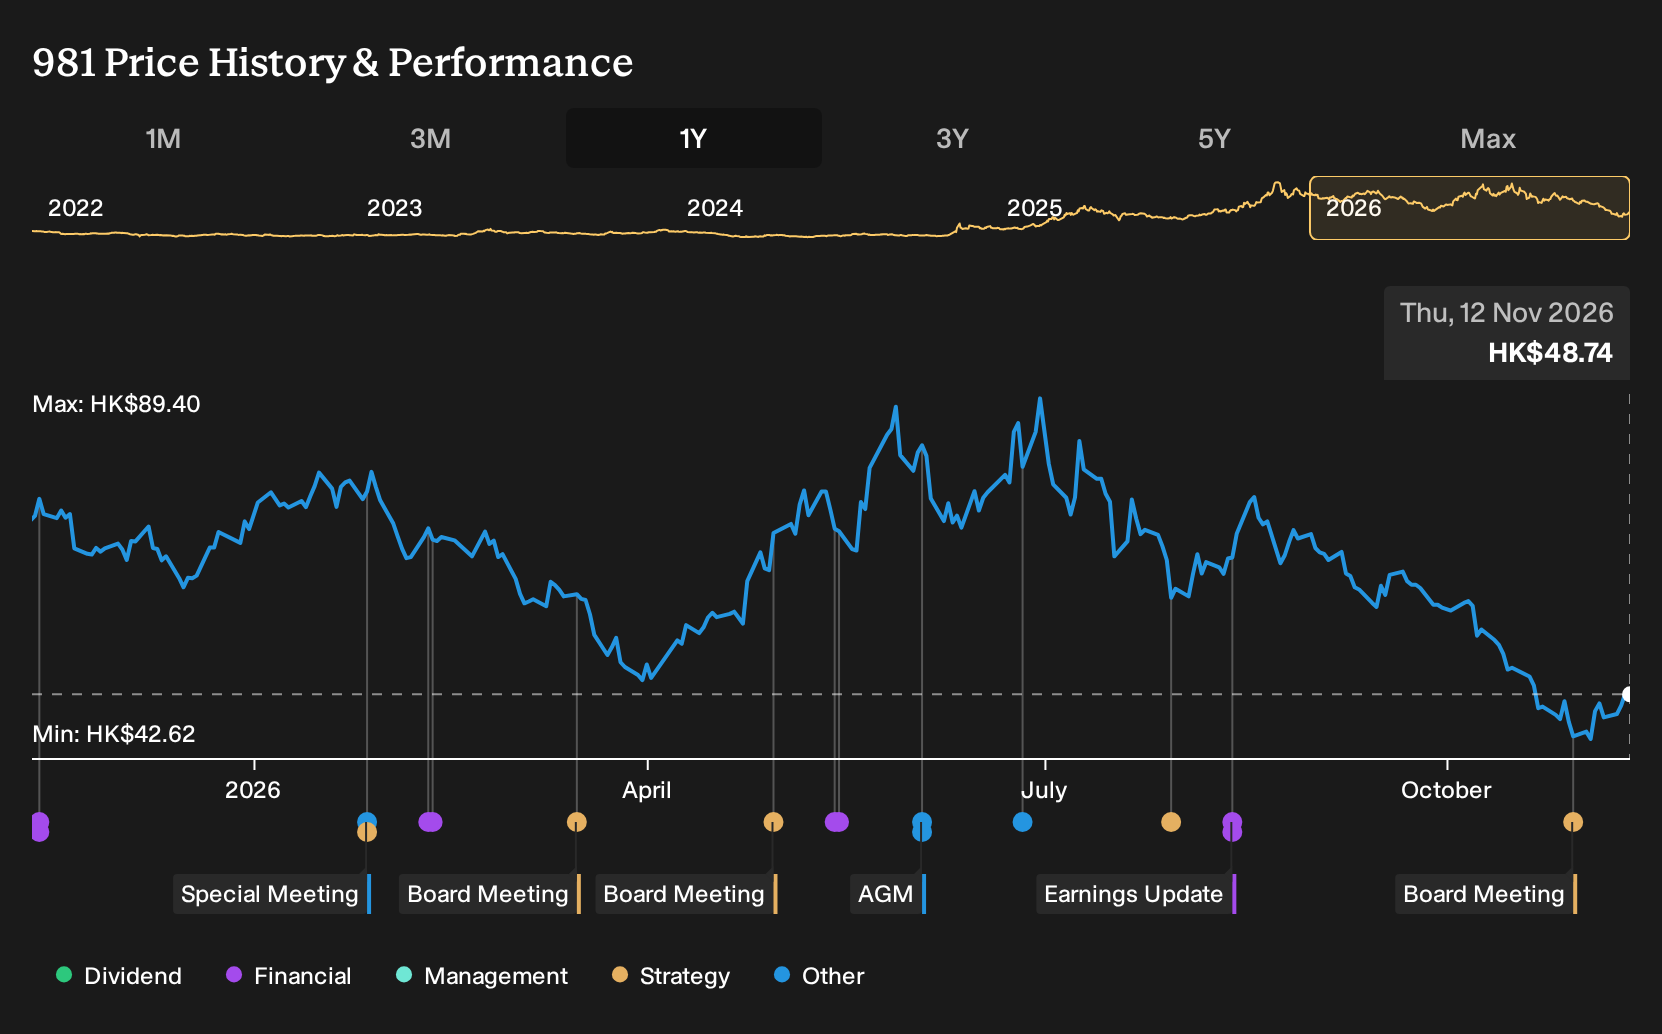
The board meeting on 12 November 2026 to approve the unaudited third quarter results is the next check point. Investors get a cleaner quarterly view on how much of the year to date strength comes from underlying demand for power management, BCD and other AI linked or automotive platforms, and how much reflects one off items that have previously affected reported earnings quality.
Semiconductor Manufacturing International's current earnings are about US$1.0b, with analysts forecasting revenue growth of 15.2% per year and consensus earnings of US$2.2b by 2029. That implies an earnings increase of roughly 2.2x from today, and a projected 2029 revenue figure of US$15.9b alongside those expected profits.
Uncover why Semiconductor Manufacturing International's fair value indicates a 97% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame capacity expansion at Semiconductor Manufacturing International as the real catalyst. They were pencilling in revenue of about US$21.4b and earnings of US$3.5b by 2029 before this update. You can see how that far more bullish story might shift again once these new nine month results are fully absorbed.
Explore 5 other Semiconductor Manufacturing International fair value estimates, including one that suggests as much as 214% potential upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Semiconductor Manufacturing International research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Semiconductor Manufacturing International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Semiconductor Manufacturing International's overall financial health at a glance.
Looking for more Semiconductor Manufacturing International investment ideas?
If this update on Semiconductor Manufacturing International has sharpened your view but you still want a wider watchlist, use the Simply Wall St Screener to surface other companies that fit the kind of profile you are hunting for.
- If capital preservation ranks high for you, start with companies that have steadier risk profiles by reviewing 206 resilient stocks with low risk scores that might help smooth out portfolio volatility.
- If quality at a reasonable price is your focus, cast a wider net across fundamentally strong opportunities through a 563 high quality undiscovered gems that many investors may not be watching yet.
- If balance sheet strength matters most, concentrate on businesses with robust finances and cleaner leverage using the list of solid balance sheet and fundamentals (198 results) to narrow your shortlist to sturdier candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com