


- CleanSpark presented at the Cantor Fitzgerald Crypto, Fintech and AI Conference in Miami, while preparing to report an expected quarterly EPS loss and lower revenue, highlighting ongoing pressure on its bitcoin mining operations and capital needs.
- Recent commentary around power constraints, data center approvals and tenant agreements has underlined how CleanSpark's long term value hinges on securing reliable energy access and committed AI or compute tenants for its sites.
- We will look at how CleanSpark's investment narrative is affected by rising power supply and data center approval risks highlighted in the recent news.
CleanSpark Investment Narrative Recap
To own CleanSpark, you need to believe that a bitcoin miner can turn its growing data center and power footprint into consistent cash generation, even with current losses and limited cash runway. In the near term the focus is on converting energy access into paying tenants for high power computing, then containing costs so future cycles hurt less.
The latest conference appearance and earnings expectations keep the main catalyst intact. According to DanielOliveira, an investor in the Simply Wall St Community, a firm lease on any part of the Texas portfolio is the key operational trigger. The biggest risk still sits in power approvals, tenant commitments and how those intersect with ongoing losses.
The most relevant piece of context is DanielOliveira’s focus on the 20 year, 175 MW Sandersville lease in Georgia, plus the letter of intent and exclusivity for up to 885 MW across 718 acres in Texas. That framework links directly to today’s debate about whether CleanSpark can secure reliable AI or compute tenants for its power heavy sites.
Sandersville already turned a signed agreement into funding through US$2,276.0 million of 7.875% senior secured notes, so the market has seen this playbook once. A similar outcome on even a slice of Texas would speak directly to the current power access conversation. By contrast, a lapse in exclusivity without leases would reinforce concerns around approvals, vacancy and capital strain.
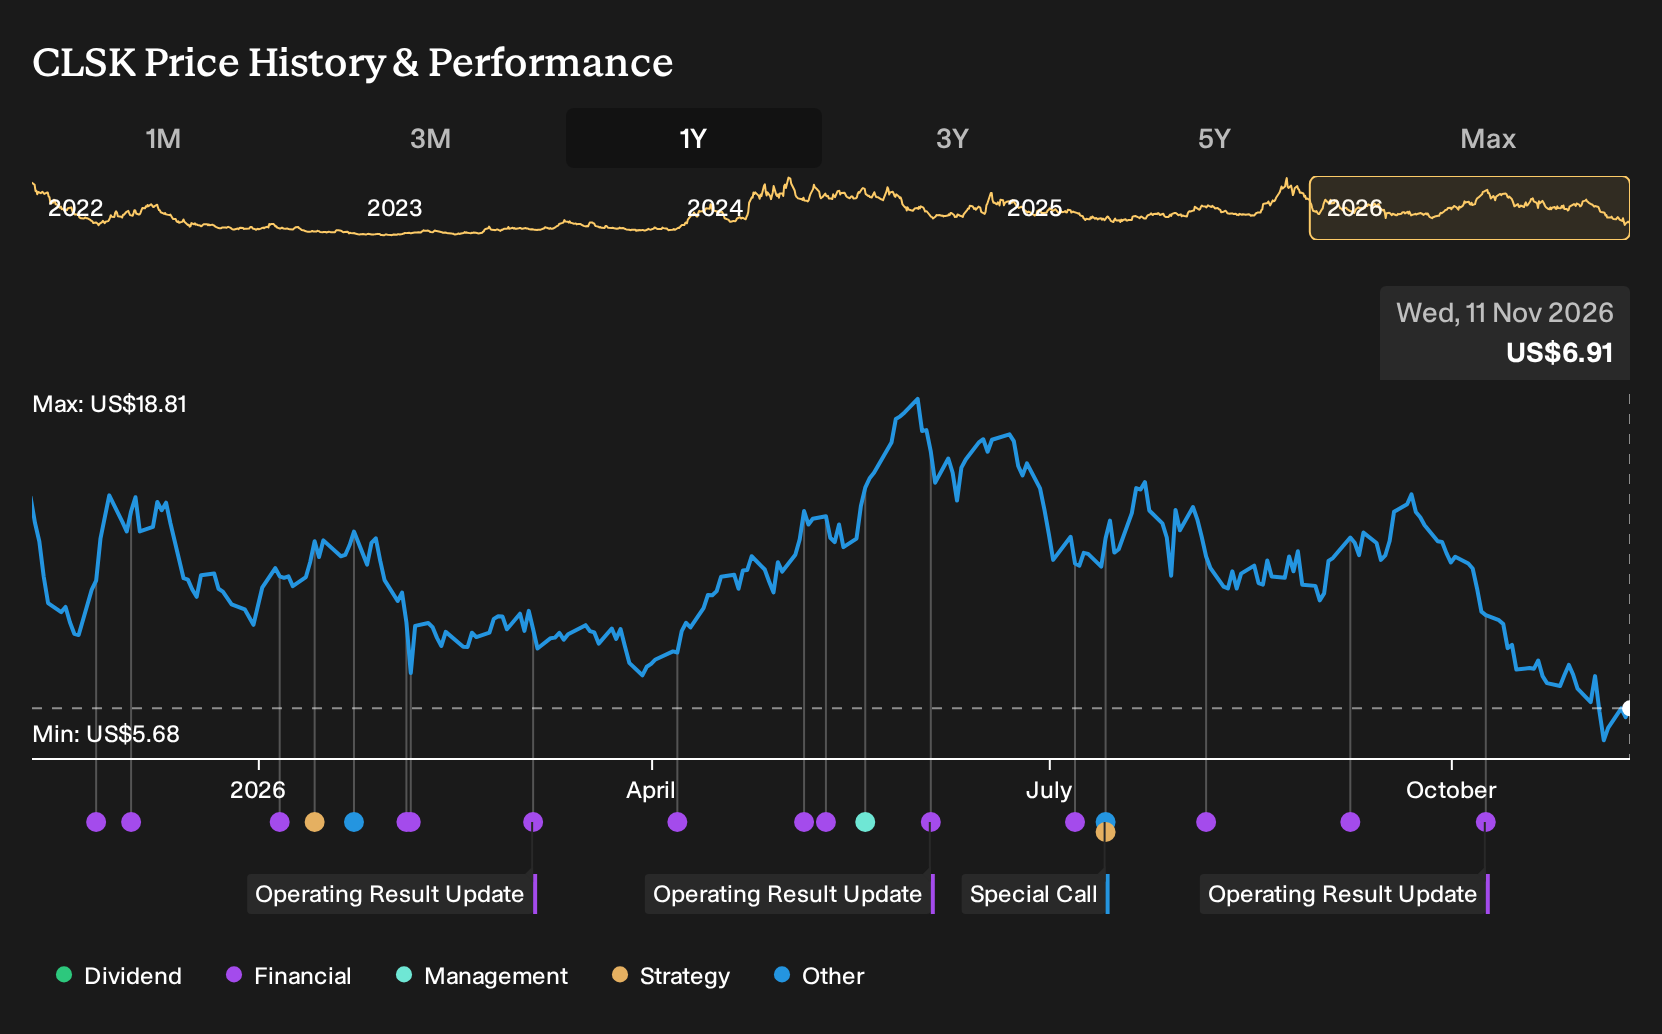
In this narrative, DanielOliveira anchors fair value at US$6.80, mainly on the expectation that a signed lease on any slice of the Texas portfolio would validate CleanSpark’s power access and tenant thesis more than the election result. At the same time, a failure to secure leases would justify the current discount.
Uncover why CleanSpark's fair value indicates that CleanSpark is roughly in line with its current price.
Exploring Other Perspectives
One bullish twist you might explore is the idea that CleanSpark’s Sandersville lease and ERCOT capacity could become a long-term income engine. The most optimistic analysts were penciling in roughly US$1.2b of revenue and US$12.5m of earnings around 2029 before this conference and an EPS loss of about US$0.36, so fresh power and tenant headlines could easily reshape those expectations.
Explore 5 other CleanSpark fair value estimates, including one that suggests potential upside of as much as 291% from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CleanSpark research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for CleanSpark. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CleanSpark's overall financial health at a glance.
Looking for more CleanSpark style investment ideas?
Once you have a view on CleanSpark, it can help to widen the lens and compare it with other businesses that match the type of opportunities you are hunting for. The Simply Wall St Screener lets you do that quickly by filtering the market down to a focused shortlist.
- If you like the idea of quality at a discount, start with a curated set of 32 high quality undervalued stocks that combine fundamental strength with appealing valuations.
- If capital preservation is front of mind, narrow your search to a 30 resilient stocks with low risk scores that score well on financial resilience and business stability.
- If you want to get ahead of the crowd, scan a 20 high quality undiscovered gems that pair healthy fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com