


Atlanta Braves Holdings (BATR.K) moved into focus after its latest earnings release, reporting higher revenue but sharply weaker profitability in the third quarter and a net loss for the nine month period.
Recent trading tells a mixed story. Atlanta Braves Holdings’ share price is up 2.94% over the past week, and the year-to-date share price return of 31.01% has helped deliver a 1-year total shareholder return of 33.86%. However, the 90-day share price performance slipped 1.77% as investors weigh stronger revenue against weaker earnings.
Compare Atlanta Braves Holdings’ mixed revenue and profit story with a hand picked set of resilient businesses using the list of solid balance sheet and fundamentals (23 results) as a starting universe.
After a strong year-to-date run and a recent wobble in profitability, Atlanta Braves Holdings now trades with a clear gap between its current price and analyst value estimates. Where does fair value realistically fall within that spread?
Most Popular Narrative: 18% Undervalued
Based on the analyst consensus Narrative on Simply Wall St, Atlanta Braves Holdings carries a fair value estimate of $63.40 against a last close of $52.22, which points to meaningful upside if those assumptions play out and helps explain why recent price weakness has not flipped the story to bearish.
The shift to BravesVision as an owned media platform, with management indicating it is on pace to meet or exceed prior local rights economics and direct-to-consumer streaming described as very strong and outperforming early projections, points to potential upside for media revenue and improved long term earnings quality as the new model scales.
See why 4 investors see Atlanta Braves Holdings as 18% undervalued.
Result: Fair Value of $63.40 (UNDERVALUED)
Still, the story can break if higher player, production and event costs keep margins under pressure, or if labor disputes materially disrupt BravesVision and game day income.
Find out about the key risks to this Atlanta Braves Holdings narrative.
Another View: What Multiples Say About Atlanta Braves Holdings
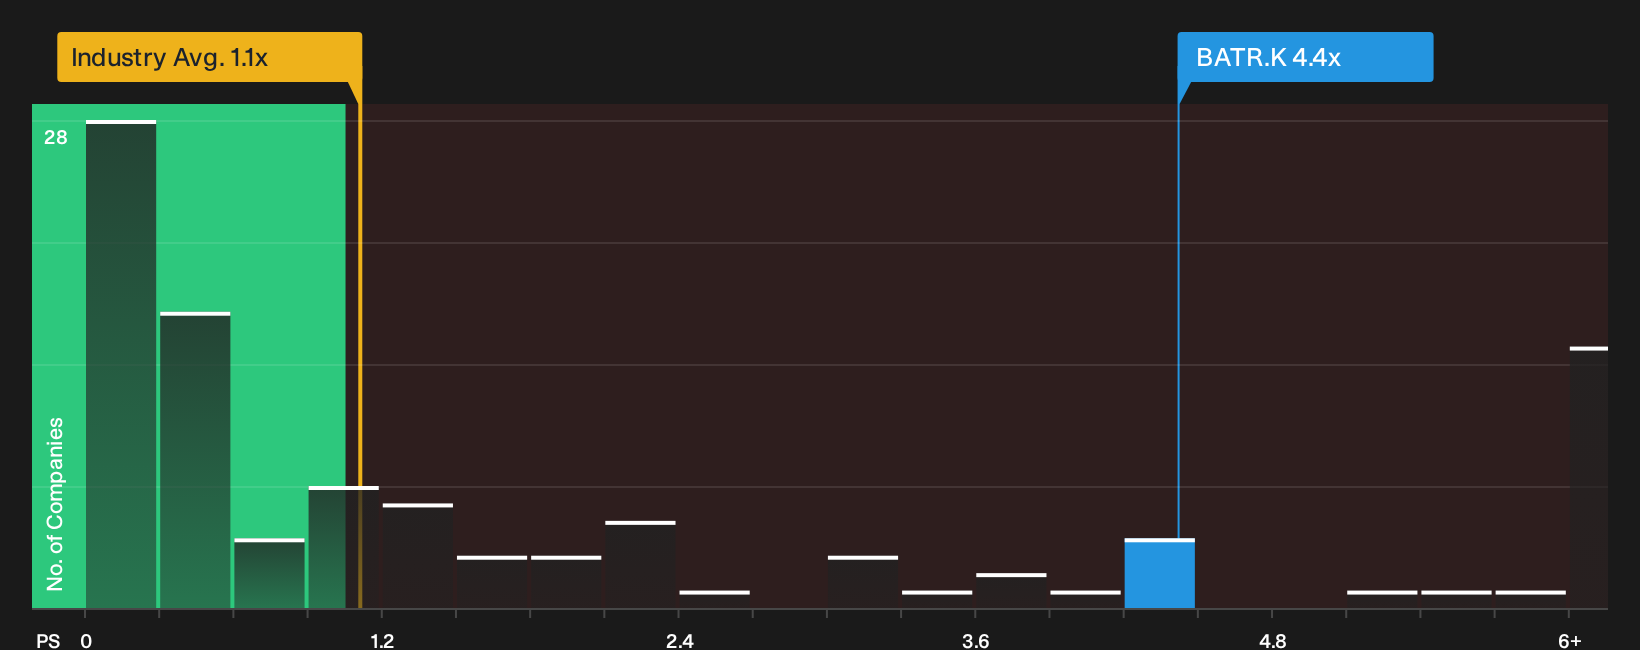
Analyst narratives reference a fair value of $63.40, yet the current trading picture for Atlanta Braves Holdings tells a different story when using its P/S ratio. The stock changes hands at 4.4x sales, while the US Entertainment industry sits near 1.1x and peers cluster around 3.5x. Against a fair ratio of 0.9x, that premium suggests investors are already paying up for the franchise story and media potential. The key consideration is whether your own assumptions about future revenue and earnings align with that level of valuation.
For a closer look at how this pricing compares with fundamentals, review the valuation breakdown via the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Atlanta Braves Holdings can create noise, so move quickly to review the underlying metrics yourself and decide whether the risk profile fits your plan. To see what is currently worrying some investors, start with the 1 important warning sign.
Looking for more investment ideas beyond Atlanta Braves Holdings?
Do not stop with just one stock. Broader context often reveals better fits for your goals, and skipping that step can quietly cap your potential returns.
- Target lower volatility in your portfolio by reviewing a curated group of steadier businesses through the 30 resilient stocks with low risk scores.
- Pinpoint companies that trade below their assessed worth using the focused list of 32 high quality undervalued stocks.
- Spot overlooked opportunities with solid fundamentals before they hit the mainstream by scanning the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com