


- J.B. Hunt Transport Services recently presented at the Baird 2026 Global Industrial Conference in Chicago, with its CFO and Intermodal president outlining the business and industry context for the trucking and logistics operator.
- Options on J.B. Hunt Transport Services now show elevated implied volatility around a specific December 2026 call strike, highlighting how investors are closely watching earnings expectations and the company’s operating outlook.
- We will now look at how the investment narrative for J.B. Hunt Transport Services could be affected by the spike in options volatility.
Scan how traders are pricing J.B. Hunt Transport Services' conference signals against peers by running through our hand picked list of 30 resilient stocks with low risk scores.
J.B. Hunt Transport Services Investment Narrative Recap
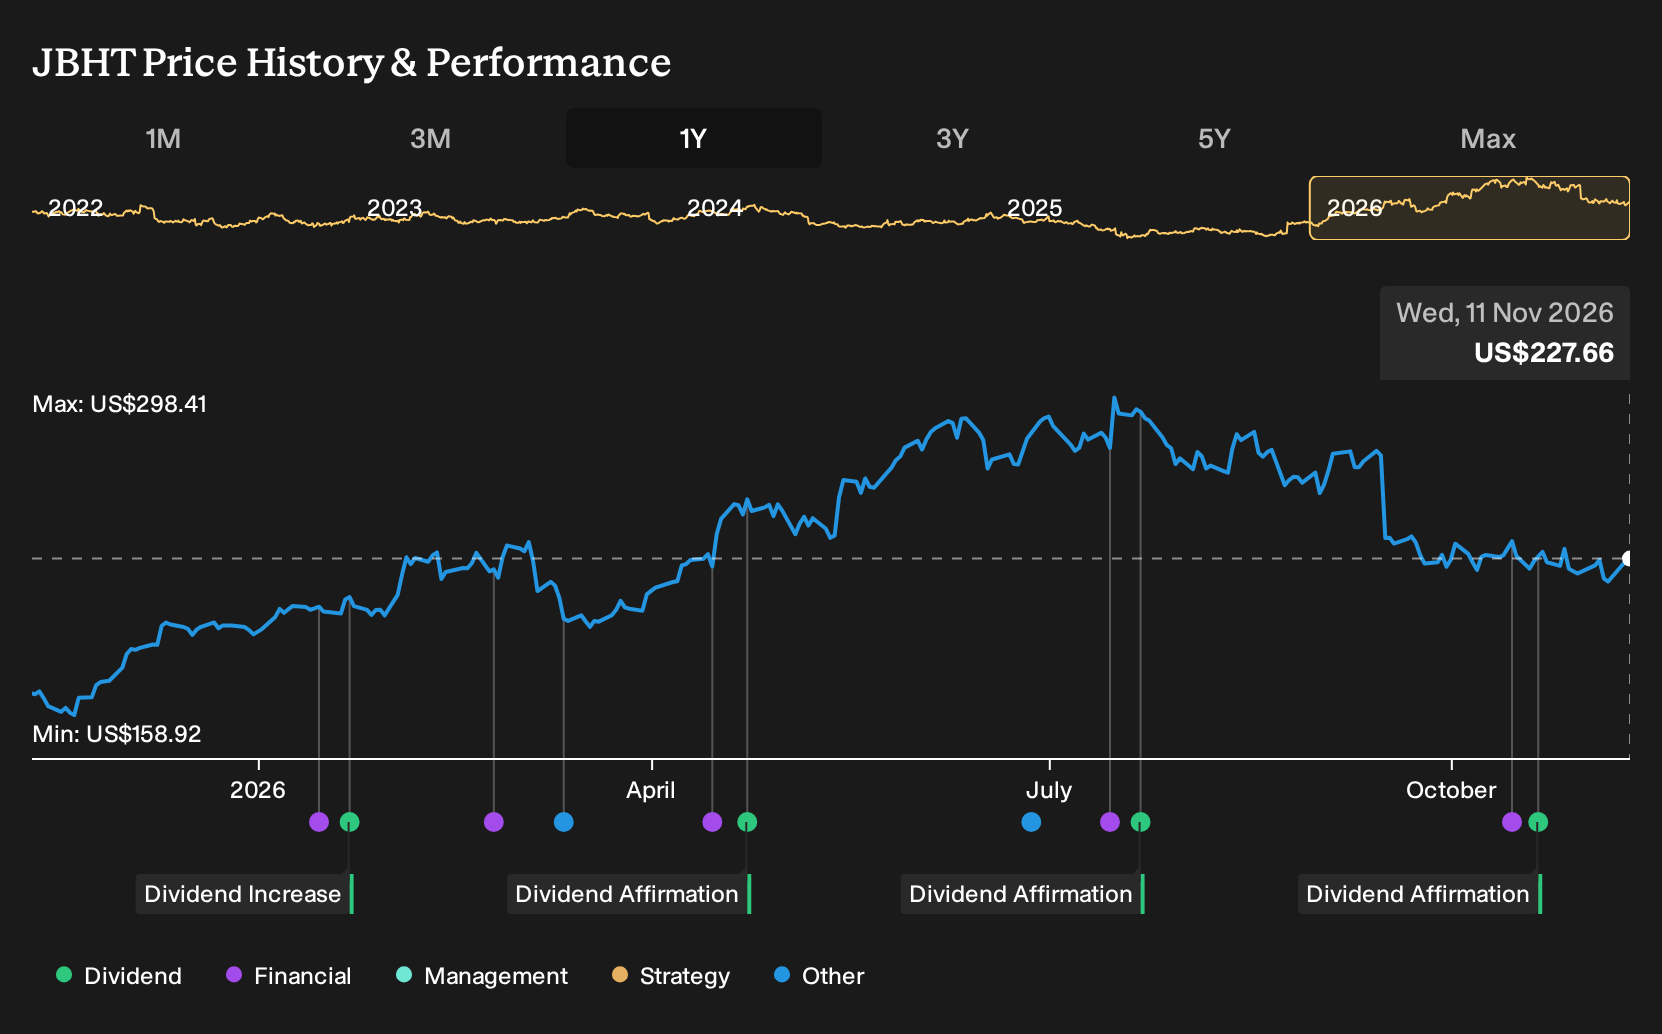
For an investor to stay with J.B. Hunt Transport Services, the core belief is that record intermodal volumes, cost discipline and the AI freight execution platform can offset pressure from driver and fuel costs. The analyst consensus Narrative on Simply Wall St flags these productivity and utilization gains as central. The recent conference and options volatility do not appear to change the near term swing factor, which is whether Q3 2026 earnings pressure stabilizes.
The biggest operational risk remains inflationary costs. Management has already guided to a 5% to 10% sequential earnings decline for Q3 2026, and extended fuel headwinds in Dedicated could keep operating margins constrained. Legal overhang from the securities class action investigation also sits in the background for sentiment, even if core operations hold steady.
The Baird 2026 Global Industrial Conference appearance is the announcement that matters most for this options spike. CFO Brad Delco and Intermodal head Darren Field are positioned to address how intermodal volumes, Dedicated Contract Services and cost to serve initiatives fit with the current earnings guidance. Options traders are essentially pricing how credible that operational story looks against existing headwinds.
What you want to listen for is how J.B. Hunt Transport Services frames record intermodal loads, the US$135m of structural cost removal and the rollout of its AI freight execution platform relative to fuel and driver inflation. Any update on Dedicated margins, intermodal bid seasons or the sales pipeline tied to the planned 1,000 to 1,200 truck additions in 2026 could reset expectations for both the key catalyst and the main risk.
J.B. Hunt Transport Services' current analyst story assumes revenue reaches US$16.7b and earnings come in at US$1.1b by 2029, based on 9.5% yearly revenue growth and an earnings increase of about US$425.5m from US$674.5m today.
Uncover why J.B. Hunt Transport Services' fair value indicates a 24% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses less on record intermodal volumes and more on whether J.B. Hunt Transport Services can earn enough on that freight. The most cautious analysts were penciling in about US$16.3b of revenue and US$1.1b of earnings by 2029 before this conference. That is a tighter, more margin wary story. With options volatility spiking around the Baird appearance, treat this as a signal to compare those cautious forecasts with the more upbeat consensus and decide which story fits your own expectations.
Explore 3 other J.B. Hunt Transport Services fair value estimates, including one that suggests as much as 8% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your J.B. Hunt Transport Services research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for J.B. Hunt Transport Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate J.B. Hunt Transport Services' overall financial health at a glance.
Looking for more investment ideas beyond J.B. Hunt Transport Services?
If the J.B. Hunt Transport Services story has you thinking about portfolio balance, use this moment to scan a wider field of opportunities. The Simply Wall St Screener can help you quickly narrow down stocks that better match your risk tolerance, income needs or preference for quality balance sheets.
- For investors who care most about capital preservation and steadier profiles, start with companies that score well on resilience through the 30 resilient stocks with low risk scores.
- If you want to focus on businesses that combine quality fundamentals with share prices that may not fully reflect them, filter for potential value opportunities using the 32 high quality undervalued stocks.
- For readers building a long term income stream, check out higher yielding payout candidates by running a search through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com