


- Viking Holdings is approaching its November 17 earnings release for the September 2026 quarter, with analysts expecting earnings per share of $1.23 and revenue of $2.18b, while recent estimate revisions have turned more cautious.
- At the same time, Viking Holdings has attracted attention from traders as technical analysis points to a breakout setup and strong price and volume accumulation in the stock.
- We will now look at how Viking Holdings' investment narrative could be influenced by the upcoming earnings release and potential technical breakout in the stock.
Scan beyond Viking Holdings and line up other potential breakout candidates with the hand picked 32 high quality undervalued stocks, which already pair momentum with underlying business quality.
Viking Holdings Investment Narrative Recap
To own Viking Holdings, you need to be comfortable with a cruise operator that focuses on an affluent, older guest base, a large committed fleet and a high level of debt. The analyst consensus Narrative on Simply Wall St highlights capacity expansion into India, Egypt and the U.S. market, together with strong booking visibility, as key supports for the long term story.
Right now the main near term swing factor is execution on that capacity ramp while keeping itineraries running smoothly despite environmental or geopolitical disruptions. The earnings print on November 17 may shape sentiment, but the core risk remains whether Viking can fund ship spending and any capital returns without stretching its balance sheet.
The most relevant recent development for this setup is the expectation of higher earnings and revenue for the September 2026 quarter, paired with more cautious analyst revisions. That combination often sharpens focus on how efficiently Viking Holdings is converting bookings and committed capacity into net income and cash generation.
For you, the link back to catalysts is straightforward. Strong advanced bookings and committed ship deliveries create a pipeline, while the slightly bearish revisions serve as a reminder that execution on margins, disruption management and debt service is being watched closely. The technical breakout story only really holds if those operational pieces stack up over coming quarters.
Viking Holdings' current earnings are about US$1.3b, and analysts expect revenue to grow by 15.9% each year, with earnings projected to reach US$2.5b by 2029. This implies an increase of roughly US$1.2b from earnings today, supported by forecast revenues of US$10.9b in the same year.
Uncover why Viking Holdings' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
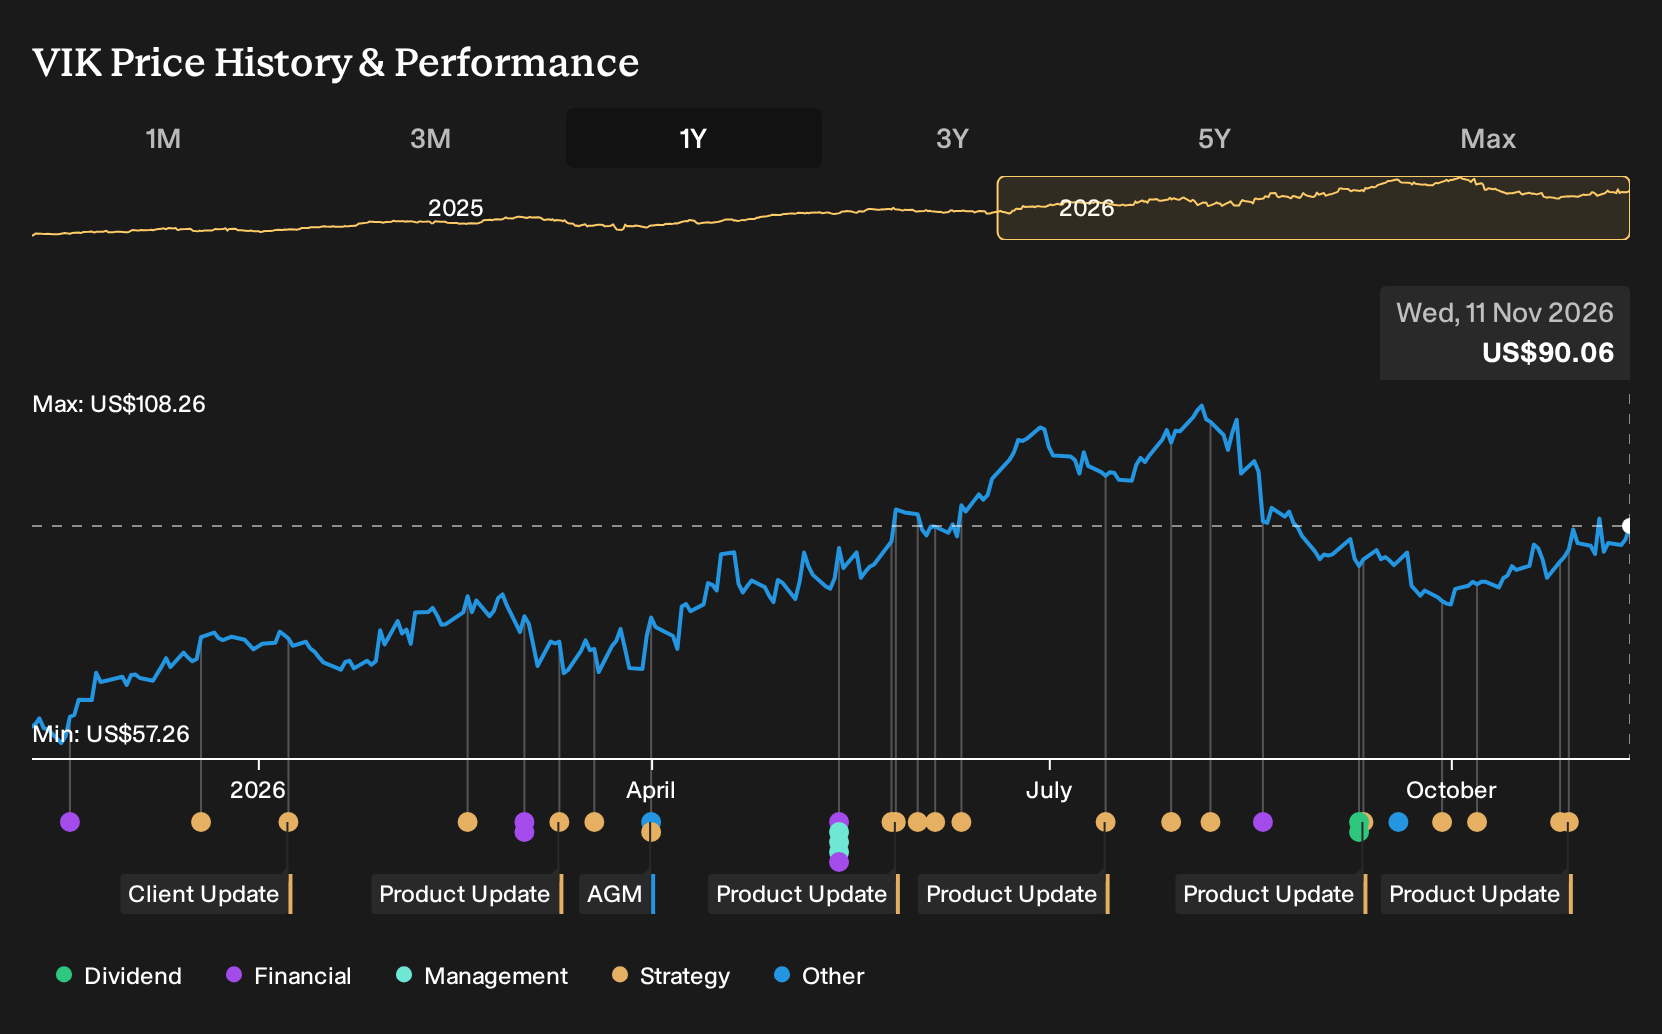
Exploring Other Perspectives
One bullish twist on Viking Holdings focuses less on booking risk and more on financial firepower. The most optimistic analysts point to the roughly US$4b cash balance and US$1b revolver, and had pencilled in revenue of about US$11.5b and earnings of US$2.9b by 2029. Those forecasts were set before this earnings release, so you may want to see how the story shifts once fresh numbers land.
Explore 4 other Viking Holdings fair value estimates, including one that suggests there could be as much as 45% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Viking Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viking Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viking Holdings' overall financial health at a glance.
Looking for more Viking Holdings style investment ideas?
If the setup around Viking Holdings has sharpened your thinking, use that same lens to scan a broader list of potential opportunities with the Simply Wall St Screener.
- For readers who care most about quality at a sensible entry point, line up candidates that combine strong fundamentals with appealing valuations through the 20 high quality undiscovered gems.
- If capital preservation is front of mind, focus on steadier businesses that score well on financial resilience by running the 30 resilient stocks with low risk scores.
- Income focused investors who want consistent cash returns from their holdings can zero in on reliable payers using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com