


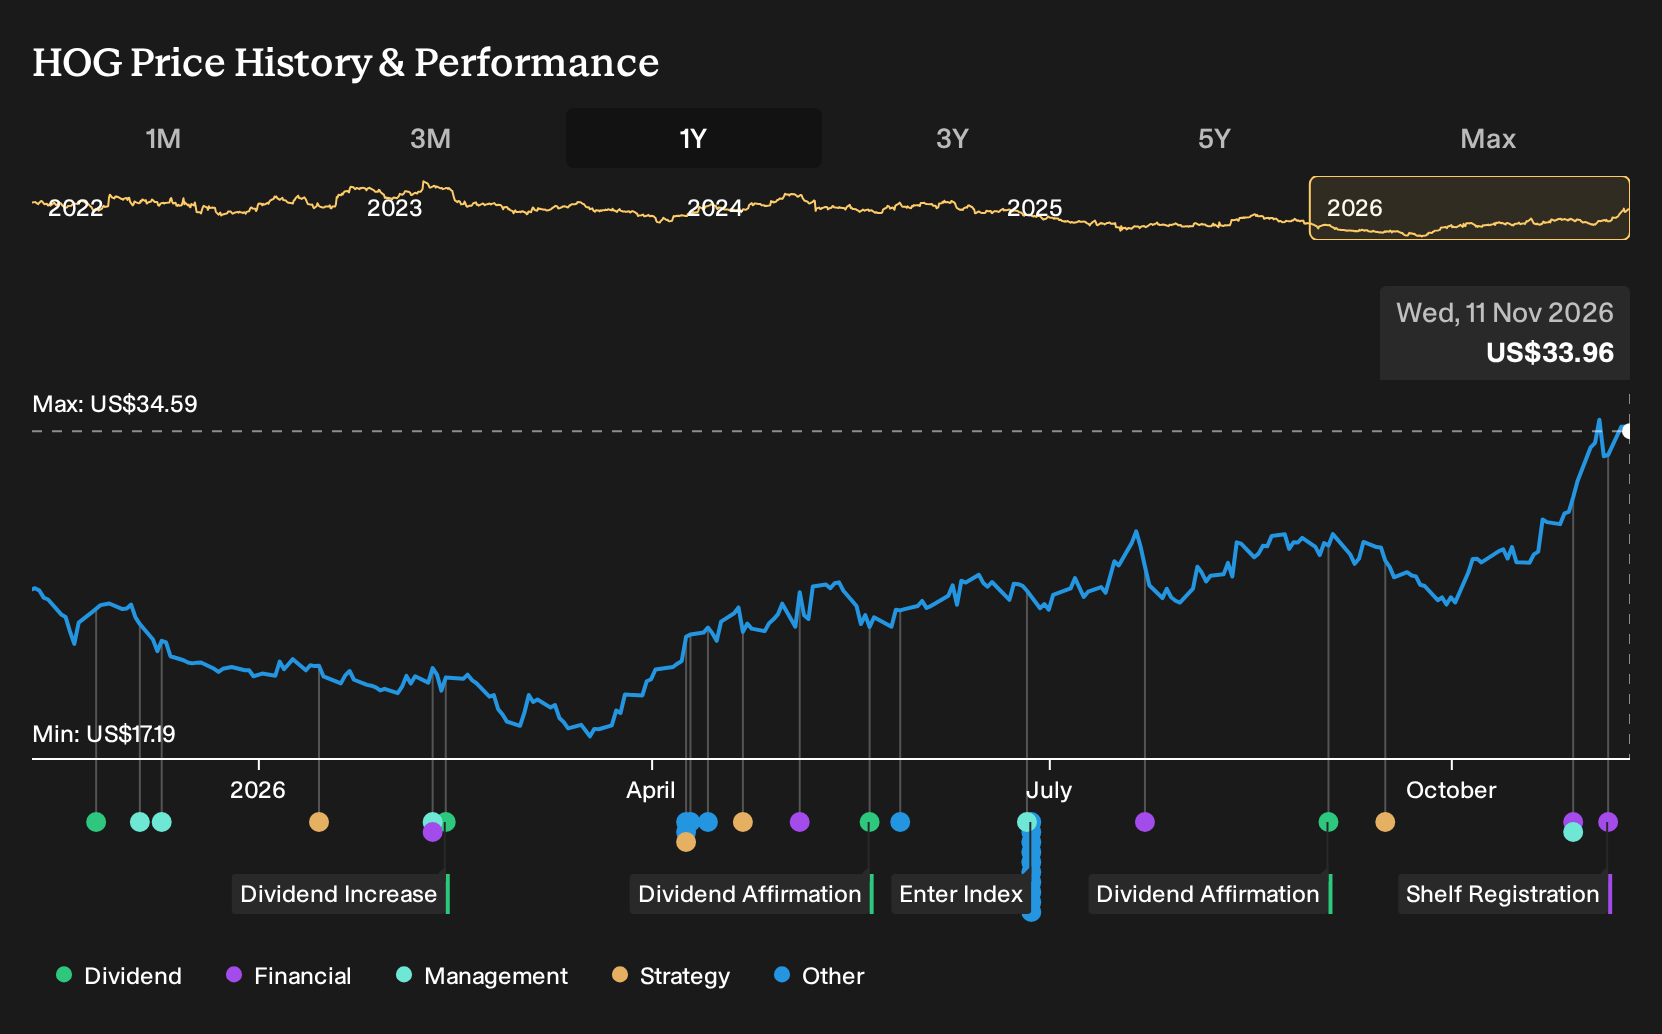
- Harley-Davidson filed an omnibus shelf registration in early November 2026 that covers common and preferred stock, debt securities, warrants, stock purchase contracts, depositary shares, and equity units, shortly after reporting much lower net income and earnings per share for both the third quarter and first nine months of 2026 compared with a year earlier.
- The combination of weaker recent profitability and fresh flexibility to issue a wide range of securities puts Harley-Davidson’s capital needs, potential dilution, and funding choices under closer scrutiny for anyone focused on its Back to the Bricks execution and balance sheet goals.
- We will now look at how Harley-Davidson’s investment narrative could be affected by the new shelf registration and funding flexibility.
Harley-Davidson Investment Narrative Recap
To own Harley-Davidson, you need to believe the Back to the Bricks plan can still restore healthier profitability despite a much weaker 2026 earnings run rate. Net income for the third quarter dropped to US$42.76 million from US$377.37 million, and nine month profit also declined sharply. That puts the spotlight firmly on execution rather than story.
The key near term catalyst is whether cost savings and product mix changes can steady margins while tariffs continue to pressure expenses. The biggest risk right now is that softer earnings, combined with a heavier tilt to more affordable bikes, leaves Harley-Davidson with less profit to support reinvestment and any shareholder returns.
The new omnibus shelf registration is the announcement that ties most directly to this setup. It gives Harley-Davidson room to issue equity, debt or hybrids at relatively short notice. After such a steep drop in earnings per share, any sizeable equity issuance would likely sharpen investor focus on potential dilution and required returns on that capital.
At the same time, that extra flexibility could matter if tariffs keep adding US$75 million to US$90 million of annual cost pressure versus 2024 and if margins stay tight. The analyst consensus narrative on Simply Wall St emphasizes a capital light finance arm and fixed cost savings as core catalysts. Funding choices under the new shelf now sit alongside those execution goals as an important part of the Harley-Davidson story.
Harley-Davidson's narrative projects US$4.0b revenue and US$264.4 million earnings by 2029, with analysts assuming revenue stays broadly flat and earnings rise by about US$396 million from a loss of US$132.0 million today.
Uncover why Harley-Davidson's fair value indicates a 12% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame Harley-Davidson’s shelf registration as a future capital tool for growth, not just a dilution risk. Before this filing and the weaker 2026 earnings, they were modeling revenue at about US$4.3b and earnings near US$461.8 million by 2029. Your view may differ. Treat these pre news forecasts as reference points that could shift.
Explore 3 other Harley-Davidson fair value estimates, including one that suggests there may be as much as 9% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Harley-Davidson research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Harley-Davidson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Harley-Davidson's overall financial health at a glance.
Looking for more Harley-Davidson investment ideas?
Once you have a handle on Harley-Davidson, it can help to compare its setup with other opportunities that better match your goals for income, quality, or risk. The Simply Wall St Screener can be a useful way to widen your watchlist without losing focus on fundamentals.
- If you want income to carry more weight in your portfolio, check out a curated group of resilient payers through 6 dividend fortresses.
- If capital preservation matters most to you, you can filter for sturdier balance sheets and measured risk using the 30 resilient stocks with low risk scores.
- If you are hunting for quality at a reasonable price, you can scan a focused list of potentially mispriced opportunities via the 32 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com