


Hot U.S. inflation data and louder Fed talk about more rate hikes are putting interest rates back at the center of every market conversation. Higher yields can reshape where money flows, whether you own banks, insurers, or broad index funds. This article walks through three large U.S. financial stocks that our screener flags as potentially resilient to rising rates, so you can decide whether they deserve a closer look.
The three stocks covered below are just a sample from this idea, and the full screen surfaced 25 more large U.S. banks and insurers with equally compelling quantitative stories that are not discussed in this article. To identify your own shortlist, head straight to the U.S. Large-Cap Financials (Banks & Insurance) Benefiting from Higher Interest Rates screener to analyze, compare, and focus on the highest-conviction candidates that fit your risk and income goals.
Hancock Whitney (HWC)
Hancock Whitney sits near the center of this higher rate theme, with a balance sheet geared to net interest income and an analyst consensus Narrative on Simply Wall St that focuses on how management is trying to turn that rate sensitivity into more durable earnings power.
Hancock Whitney is a regional financial holding company providing deposit, lending, treasury, and wealth services across commercial, small business, and retail clients, generating about US$1.4b from banking operations in the United States and carrying a market cap of roughly US$5.7b.
"Ongoing balance sheet repricing, including the January 2026 bond portfolio restructuring that moved US$1.5b of securities from a 2.49% yield to 4.35%, is expected to add roughly 7 basis points to net interest margin and about US$24m of net interest income each year."
The real swing factor for Hancock Whitney is how one less visible pressure on profitability ultimately feeds through to that rate sensitive margin story.
That pressure point is where things get interesting, and the full narrative for Hancock Whitney shows whether rate sensitivity is quietly masking risk or setting up a stronger earnings mix ahead.

ConnectOne Bancorp (CNOB)
ConnectOne Bancorp taps directly into the higher rate theme of this screener, since the analyst consensus Narrative on Simply Wall St frames it as a balance sheet focused lender to small and mid sized businesses where loan repricing, funding costs and credit quality can heavily influence earnings power.
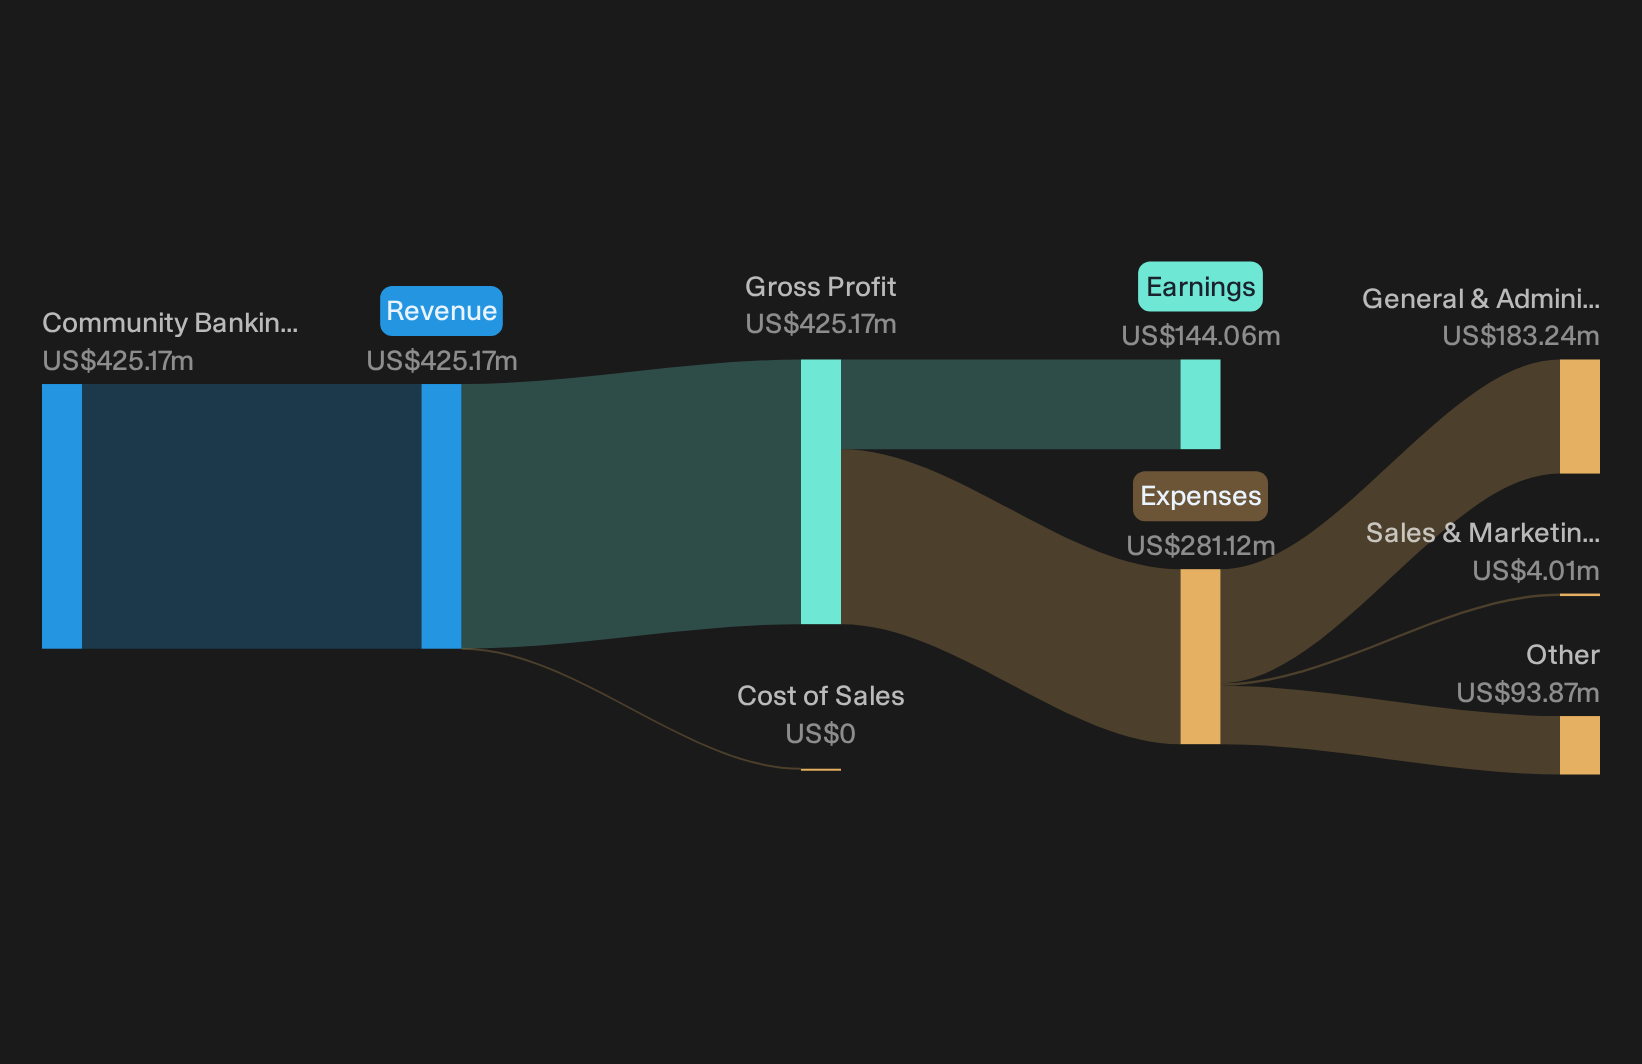
ConnectOne Bancorp runs a U.S. community banking franchise that earns about US$425 million from community banking services and has a roughly US$1.6b market cap. This ties its fortunes closely to how higher interest rates filter through loan yields and deposit pricing.
"ConnectOne Bancorp is working through a large pipeline of adjustable rate and fixed loans that are repricing at higher yields, with about US$700m already repriced in 2026 at an average 255 basis point increase and similar volumes expected ahead."
What matters next is how one persistent cost line reacts if funding competition tightens just as that repricing wave runs through the book.
If that funding squeeze is what you are weighing up, the full narrative for ConnectOne Bancorp explains how repricing, costs and credit risk could be quietly accelerating or stalling ConnectOne Bancorp.
Glacier Bancorp (GBCI)
Glacier Bancorp is one of the clearest examples in this higher rate screen of a commercial bank whose earnings are closely tied to interest income, generating about US$1.2b from banking services in the United States and carrying a market value near US$6.4b.
The analyst consensus Narrative on Simply Wall St frames Glacier Bancorp as a higher rate beneficiary because loan yields, securities reinvestment and deposit costs all feed directly into its profitability story.
"Continued repricing of Glacier Bancorp’s loan and securities books, combined with the removal of $440 million of higher cost Federal Home Loan Bank advances and lower total funding costs that moved from 1.52% in Q4 2025 to 1.33% in Q2 2026, is expected to keep widening net interest margin and support future earnings."
For investors watching this bank, much depends on how one less visible funding pressure shapes the next phase of that margin path.
That funding question is exactly what the full narrative for Glacier Bancorp unpacks, highlighting where Glacier Bancorp’s margin story could be quietly accelerating or at risk of stalling in the future.

Seeking Fresh Alternatives Before They Fly
Market momentum can flip fast. Fresh opportunities can be identified early, then move out of reach while the data is still under the radar for now. Scan new ideas and act promptly.
- Spot income workhorses delivering consistent cash today by running the 6 dividend fortresses before yields change and the crowd starts bidding them up.
- Track fast moving AI enablers quietly building real profits with the 42 profitable AI stocks that aren't just burning cash while valuations still reflect hesitation rather than full blown enthusiasm.
- Target potential critical metals suppliers using the 33 best rare earth metal stocks so you are positioned before demand momentum turns these under followed producers into crowded trades.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com