

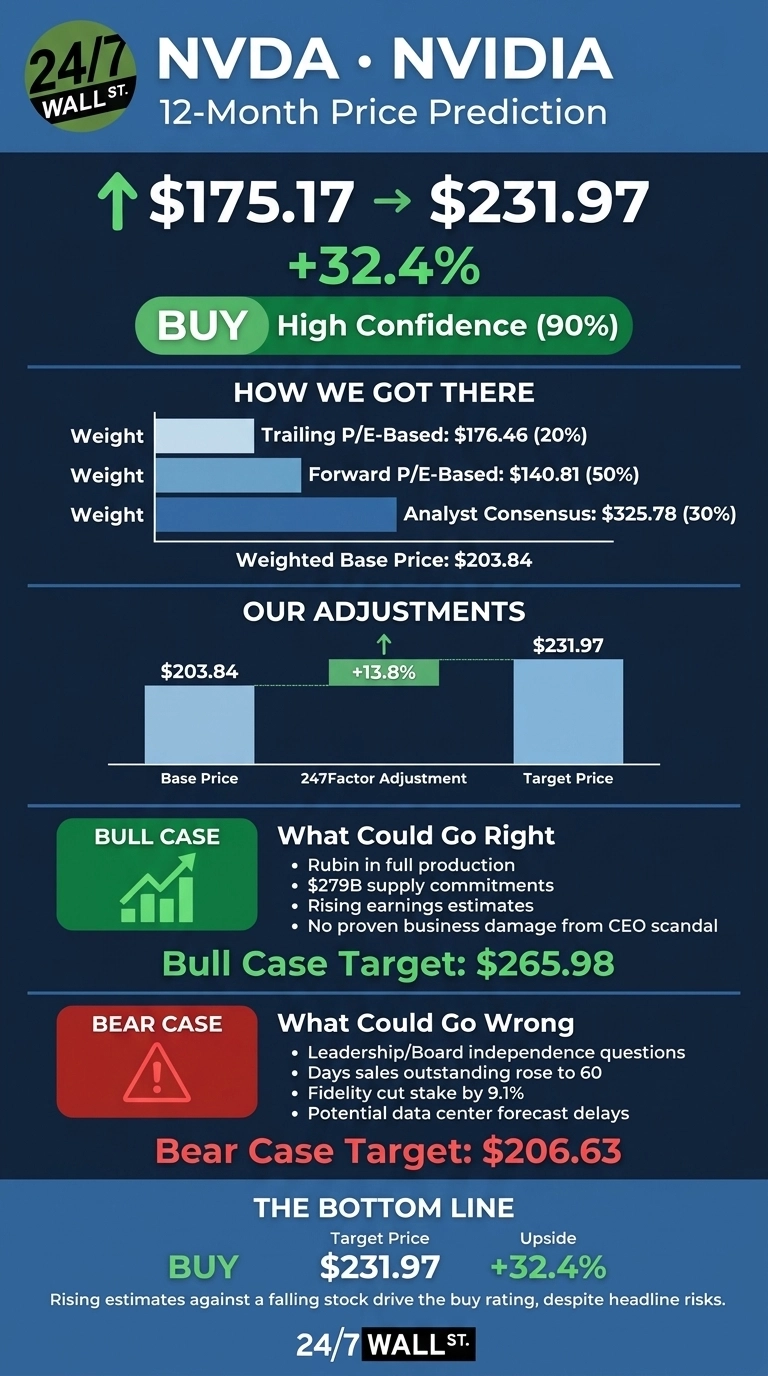
In premarket trading, NVIDIA (NASDAQ:NVDA) is up 3.72% at $175.17 after a selloff linked to a scandal involving its chief executive. For NVIDIA, the 24/7 Wall St. price target is $231.97 over the next 12 months, which means 32.4% upside. The stock earns a buy rating with high confidence from our model.
Metric Value Current Price $175.17 Price Target from 24/7 Wall St. $231.97 Upside/Downside 32.4% Recommendation BUY Confidence Level 90%Confidence has held at 0.9 in every weekly reading since mid-August, even as the target fell from $307.28 in early September. Earnings estimates kept rising while the share price dropped, and that gap is what drives the rating.
A Spy Scandal and Baird’s Downgrade Sent Shares Down 24% in a MonthShares fell 15.25% over the past week and 23.6% over the past month. That leaves them down 5.86% year to date and 28% below the 52-week high of $243.37.
The trigger was CEO Jensen Huang’s admitted affair with a Chinese executive accused of espionage. According to The New York Times, NVIDIA hired Wachtell Lipton to look into. The Kobeissi Letter estimated losses reached $500 billion in market value at one point.
Barron’s reports that the first analyst call for Huang to step aside came with a downgrade, and the stock is rising anyway (Barron’s). Baird’s Tristan Gerra moved NVIDIA to Neutral from Outperform and cut his target to $200 from $500. He cited delays to 2027 data center forecasts amid supply constraints in a note titled “‘Icarus’ Rise and Fall; Company Will Be Fine.”
The business itself is still accelerating. Fiscal Q2 2027 revenue rose 105.8% to $96.22 billion, ahead of the $92.07 billion estimate. Non-GAAP EPS came in at $2.22, beating the $2.09 estimate. Q3 guidance calls for $108 billion, and that report arrives November 17.
 24/7 Wall St. Rubin’s Ramp Gives Bulls a Path to $266
In Huang’s words, Vera Rubin is “now in full production.” Supply commitments of $279 billion, mostly memory for Rubin, point to a large ramp ahead. Data center networking grew 138% last quarter. The fiscal 2028 EPS estimate has rose to $15.9146 from $12.8148 90 days ago.
BofA repeated a Buy with a $350 target, saying the CEO allegations add uncertainty but have caused no proven business damage. Guidance also excludes China data center revenue, so any return there would be extra upside. Our bull case is $265.98.
Leadership Questions Could Cap the ReboundOur bear case is $206.63. NVIDIA’s board has no chair, and four directors have served alongside Huang for roughly 30 years or longer, which raises questions about how independent it can be.
Days sales outstanding rose to 60 from 45, and Fidelity cut its stake by 9.1%. On the other side, debt-to-equity is just 0.073 and $99 billion remains on the buyback, so the balance sheet can absorb a lot.
NVIDIA Grows Faster Than AMD and BroadcomAdvanced Micro Devices (NASDAQ:AMD) is NVIDIA’s most direct GPU rival, with Helios racks running at OpenAI, Meta and Microsoft. AMD’s Q3 revenue rose 44.68%, yet it trades at 126x free cash flow versus NVIDIA’s 42x. NVIDIA is growing faster at a much lower cash flow multiple.
The same hyperscaler budgets also buy custom AI accelerators from Broadcom (NASDAQ:AVGO). AI semiconductor revenue rose 221% to $16.70 billion, but that is still a small piece of NVIDIA’s $89.02 billion data center quarter.
Company Latest Quarter Revenue Growth Market Cap NVIDIA 105.8% $4.078 trillion AMD 44.68% $845 billion Broadcom 85.5% $1.585 trillionCompared with these peers, our target looks reasonable and arguably conservative.
Earnings Estimates Are Rising Faster Than the Headline RiskI see the 24/7 Wall St. price target of $231.97, with a buy rating and 90% confidence, as well supported. The deciding factor is rising estimates against a falling stock.
The case gets stronger if the November 17 report confirms the $108 billion guidance and the board settles the leadership question quickly. It gets weaker if the Wachtell review drags on or Rubin shipments slip. Right now, the fundamentals favor the bulls.
Beyond that, here is where our model projects NVIDIA could trade if current growth trends and market conditions hold.
Year Price Target from 24/7 Wall St. 2026 $231.97 2027 $263.38 2028 $299.04 2029 $339.52 2030 $385.49These projections assume NVIDIA keeps executing on its Rubin roadmap. A leadership change, new export restrictions or a pullback in hyperscaler spending could push the outcome far above or below this path.