


Iovance Biotherapeutics (IOVA) is back in focus after reaffirming its 2026 revenue outlook of US$410 million to US$420 million and reporting third quarter results that combined higher sales with a sharply narrower net loss.
The reaffirmed 2026 outlook and fresh lifileucel data arrive after a sharp reset, with a 30-day share price return down 44.21% even as the 1-year total shareholder return of 235.68% and 3-year total shareholder return of 83.86% point to strong longer term momentum.
Seize this reset in Iovance Biotherapeutics to benchmark it against a hand-picked 37 healthcare AI stocks harnessing data and biology in very different ways.After a 44% slide over 30 days, Iovance Biotherapeutics now trades at a steep discount to both analyst targets and intrinsic estimates. Is that a mispricing, or a fair penalty for still sizable losses?
Most Popular Narrative: 55% Undervalued
Iovance Biotherapeutics last closed at $8.09, while the most followed valuation narrative on Simply Wall St assigns a fair value of $18. The gap between those two figures is the lens this section uses, and according to Polip, an investor in the Simply Wall St Community who wrote the narrative, the current share price reflects old worries more than the present setup.
In my opinion, Iovance is one of those biotech companies where the market is still focused on what went wrong in the past instead of what could happen over the next few years. After a disappointing commercial launch in 2025, many investors lost confidence and the share price fell sharply. However, I believe the company today is much stronger than the market gives it credit for.
See why 26 investors see Iovance Biotherapeutics as 55% undervalued.
That fair value of $18 implies a 55.1% discount to the narrative estimate, using a 6.43% discount rate to bring projected cash flows back to today. The author assumes Iovance Biotherapeutics can convert its TIL platform into meaningful margins over time and treats the current loss making status as a transition phase rather than a steady state.
The same narrative leans heavily on the idea that an approved product, Amtagvi, and a growing treatment center footprint give the business a real commercial footing already. It also frames future studies across melanoma, cervical cancer, non small cell lung cancer, endometrial cancer and head and neck cancers as potential upside to that base case rather than prerequisites for the valuation to hold.
Investors weighing this $18 fair value against the $8.09 share price still need to judge whether the assumptions behind the projections feel realistic, especially around future revenue growth, eventual profitability and any capital raises along the way. The narrative highlights upside drivers, while current losses, share price volatility over the last three months and prior shareholder dilution underline why the market may be reluctant to close that gap quickly.
Result: Fair Value of $18 (UNDERVALUED)
Still, the Iovance Biotherapeutics story hinges on lifileucel execution and managing a US$220.535 million net loss, while avoiding shareholder dilution becoming a recurring feature.
Find out about the key risks to this Iovance Biotherapeutics narrative.
Another View: Market Ratios Push Back
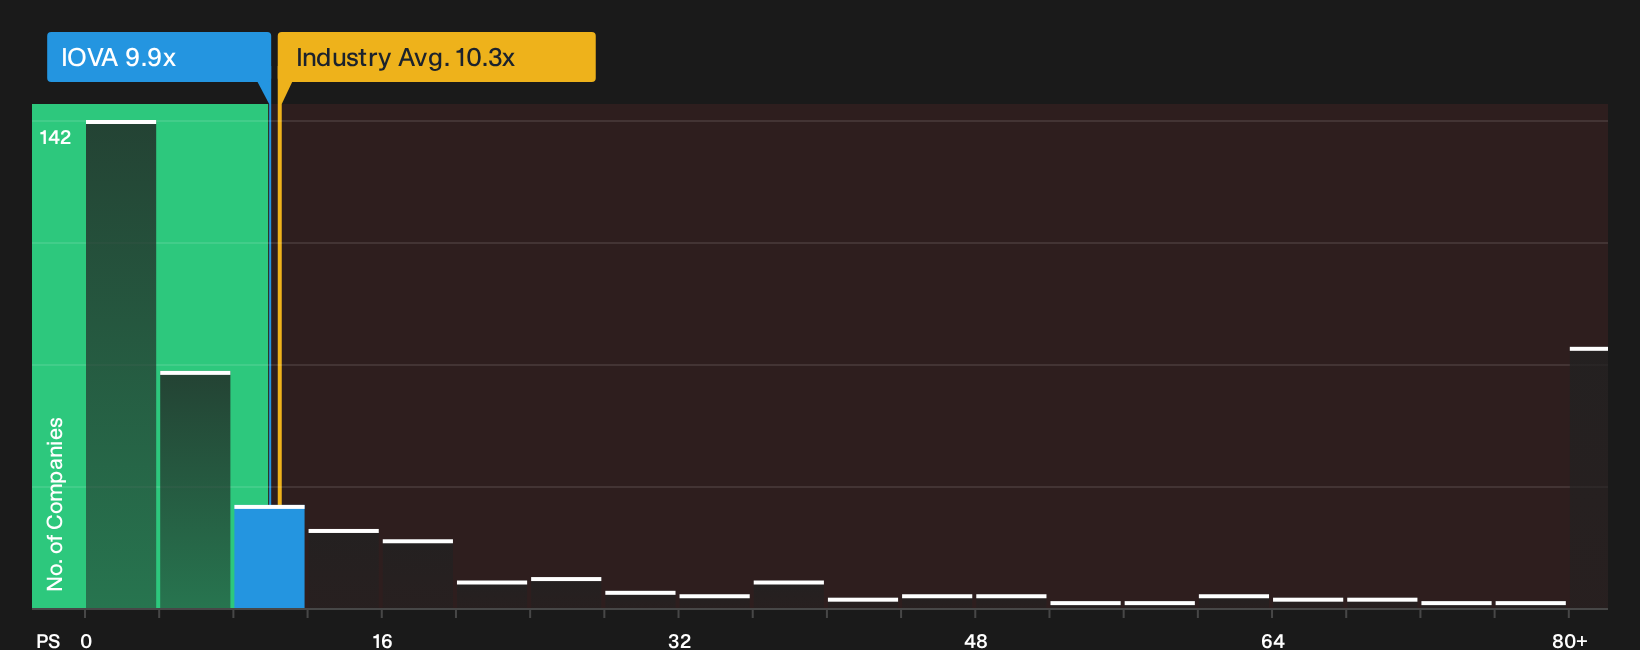
The user narrative sees Iovance Biotherapeutics as deeply undervalued, but the market ratio picture tells a tougher story. The stock trades on a P/S of 9.9x, which is richer than its 8.5x fair ratio and almost double the 5x peer average. That gap raises real questions about downside risk if sentiment cools.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Views on Iovance Biotherapeutics in this article are mixed, so consider reviewing the details promptly and evaluate the assumptions against your own framework using the 3 key rewards and 2 important warning signs.
Looking for more Iovance Biotherapeutics sized ideas?
Do not stop your research with Iovance Biotherapeutics. The same toolkit that surfaces this kind of setup can point you toward other compelling opportunities.
- Target potential mispricings by scanning a curated list of quality companies that screens for value and balance sheet strength with 32 high quality undervalued stocks.
- Build a portfolio with staying power by focusing on payouts that clear a 5% yield hurdle using the 6 dividend fortresses.
- Reduce unpleasant surprises by concentrating on businesses that the Simply Wall St risk model scores as more resilient through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com