


- Berkshire Hathaway (NYSE:BRK.A) reported that BNSF Railway Q3 earnings rose 19.3%, supported by higher freight volumes and efficiency gains.
- BNSF's stronger Q3 helped offset pressure from fuel costs that weighed on other parts of Berkshire Hathaway's operating results.
- The railroad's higher profit contribution is set to have a larger influence on Berkshire Hathaway's overall earnings mix for the quarter.
- BNSF's 19.3% Q3 earnings jump is only one piece of the broader Berkshire Hathaway story investors need to understand. We have also spotted 1 major warning sign worth knowing about at Berkshire Hathaway.
Freight strength at BNSF highlights a wider rail and logistics trend that could support taking a closer look at less crowded quality stocks as well. our screener containing 20 high quality undiscovered gems.
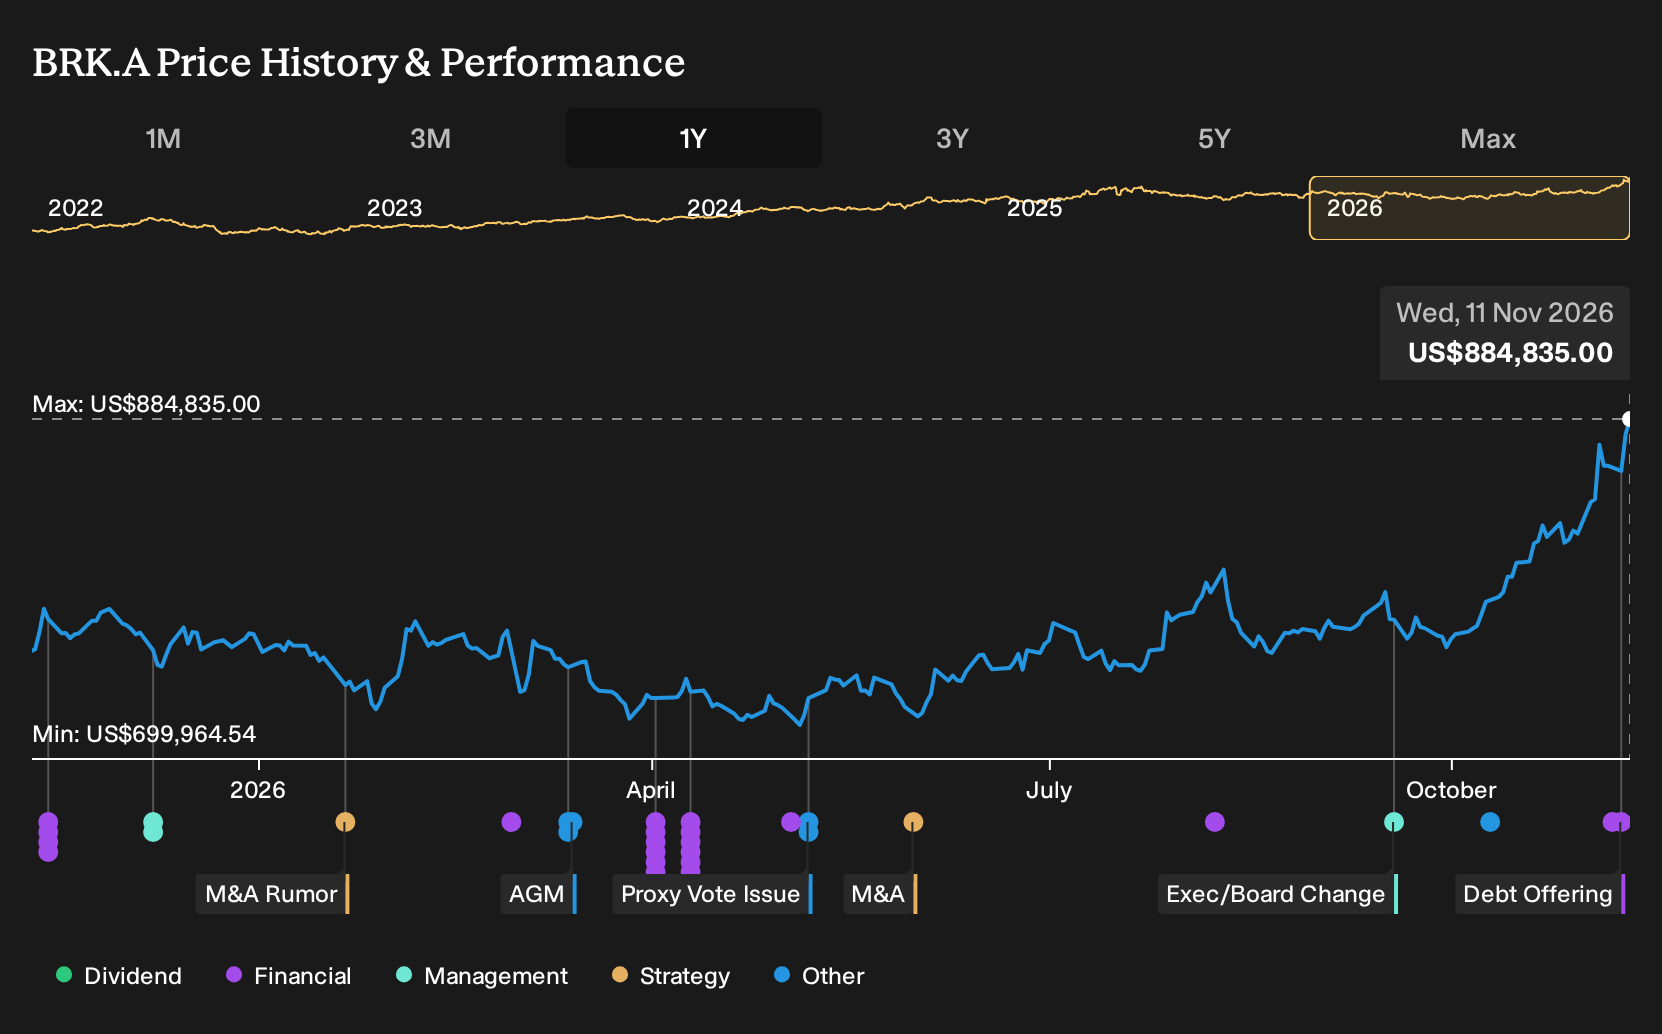
Berkshire Hathaway runs a large freight rail operation alongside its insurance and utility businesses, so a stronger quarter from BNSF matters not just for rail exposure but also for how this diversified group balances earnings between transport, underwriting and regulated energy operations.
See which insiders are buying and selling Berkshire Hathaway following this latest news.
Stronger BNSF takes some pressure off Berkshire Hathaway’s mixed quarter
BNSF’s 19.3% Q3 earnings jump gives Berkshire Hathaway a clearer bright spot in a period when group operating results felt pressure from higher fuel costs and softer insurance profitability. A sturdier rail contribution helps support the idea that Berkshire’s operating mix can balance out weak patches in other divisions, rather than relying heavily on underwriting and investment income. The unresolved piece is whether this healthier rail performance marks a consistent earnings pillar or just a strong single quarter inside a complex conglomerate.
What matters next is how BNSF’s numbers look alongside Berkshire Hathaway’s insurance and utility results in upcoming quarters, especially after the Q3 2026 report showing US$105.6b of revenue and US$22.1b of net income. Watch the rail segment’s operating earnings and volume trends in the next earnings release to see if this stronger contribution holds up as a meaningful offset to any ongoing insurance strain.
Add Berkshire Hathaway to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com