


- WPP recently featured in industry research that praised its AI driven media and data capabilities, while also flagging organisational complexity, client churn and execution challenges tied to the Elevate28 restructuring plan.
- Over the same period, analysts debated how effectively WPP can convert AI infused workflows and production changes into a healthier sales mix and margins, given recent pressure on like for like net sales.
- We will examine how WPP's investment narrative is shaped by Elevate28 and AI execution following fresh scrutiny of its media operations.
Compare how WPP's AI driven restructuring story stacks up against other potential breakouts by scanning our hand picked 4 AI small caps with similar tech heavy narratives.
WPP Investment Narrative Recap
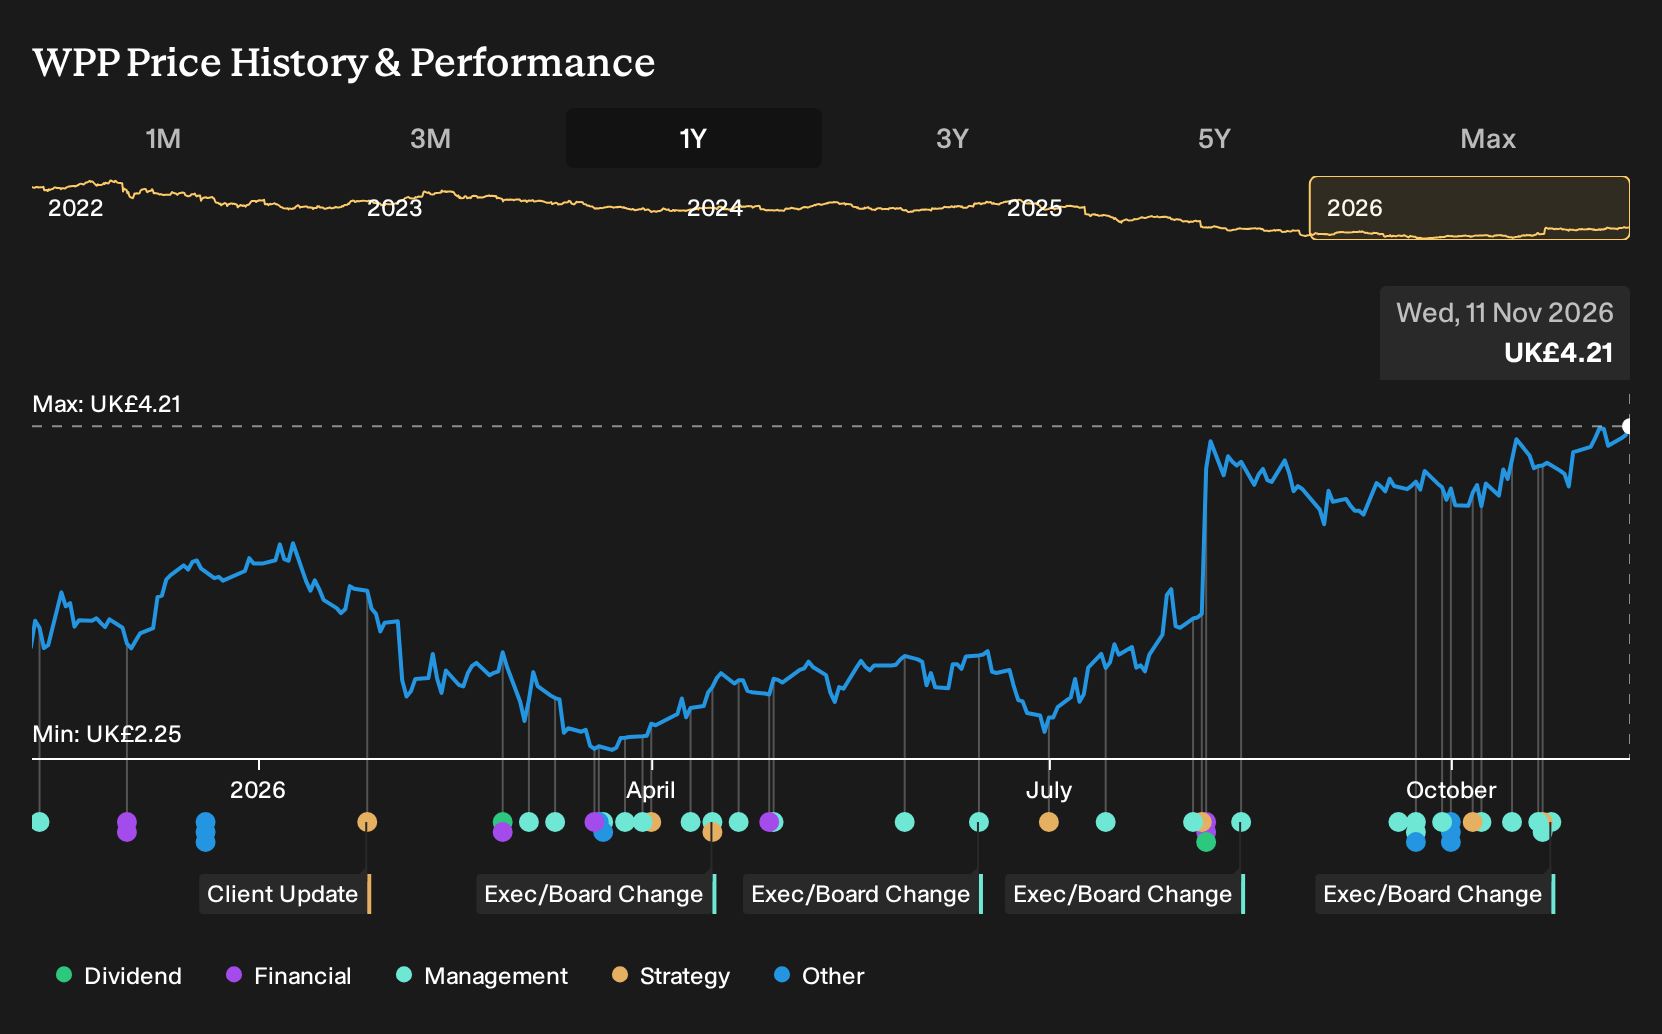
To own WPP, you need to believe that Elevate28, AI led workflows and a unified media and production model can offset pressure on like for like net sales and an unprofitable base. The analyst consensus narrative on Simply Wall St focuses on margin repair from cost savings and automation, while organic revenue headwinds ease over time.
The key short term swing factor remains whether Elevate28 execution can push delivery costs lower without worsening client churn or staff turnover. Recent commentary on WPP Media and the German restructuring keeps that risk firmly in view. Based on current information, the latest headlines do not materially change that core near term catalyst or the main downside case.
The most relevant recent data point is Forrester placing WPP alongside Omnicom and Publicis in the leader group for media services, citing its AI, data and addressable media depth. That aligns with the core catalyst, which is WPP Open, Open Intelligence and AI infused production workflows gradually lifting efficiency and, potentially, margins.
Set against that, the same report flags organisational complexity, employee churn and higher than typical client attrition, all of which are key threats to Elevate28 delivery. Analyst debate around whether current AI investment and restructuring are enough to stabilise like for like net sales and rebuild earnings underlines how execution sensitive the next couple of years look for shareholders.
On current analyst assumptions, WPP's story hinges on revenues reaching £8.9b and earnings of £301.5m by 2029, with that outcome built on revenue declining 12.3% per year and earnings shifting from a loss of £240.0m today to a profit, which is an earnings swing of about £541.5m.
Uncover how WPP's fair value indicates a 4% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
The bearish twist in the WPP story is leverage. The lowest analysts worry that debt around 2.18x headline EBITDA and roughly £3.3b of average adjusted net borrowings could limit flexibility, even as promotions like the new Associate Vice President at WPP Media signal internal momentum. Those pessimists still pencilled in about £9.0b of 2029 revenue and around £547.7m of earnings before this latest news. Use that spread to stress test your own view and decide which version of WPP’s future feels more realistic to you.
Explore 4 other WPP fair value estimates, including one that suggests as much as 29% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your WPP research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for WPP. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate WPP's overall financial health at a glance.
Looking for more ideas beyond WPP?
Once you have a view on WPP, it can help to compare it with other opportunities that fit different risk and income profiles. The Simply Wall St Screener is a quick way to line up potential candidates and pressure test where WPP really belongs in your portfolio.
- If you want resilient businesses that aim to keep downside risk in check, scan a curated set of 5 resilient stocks with low risk scores that may better suit a cautious approach.
- If dependable cash flows and income matter most to you, focus on potential 4 dividend fortresses that prioritise yield alongside staying power.
- If you prefer to hunt earlier in the story, look through a hand picked 5 high quality undiscovered gems that could offer different upside and risk profiles to WPP.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com