


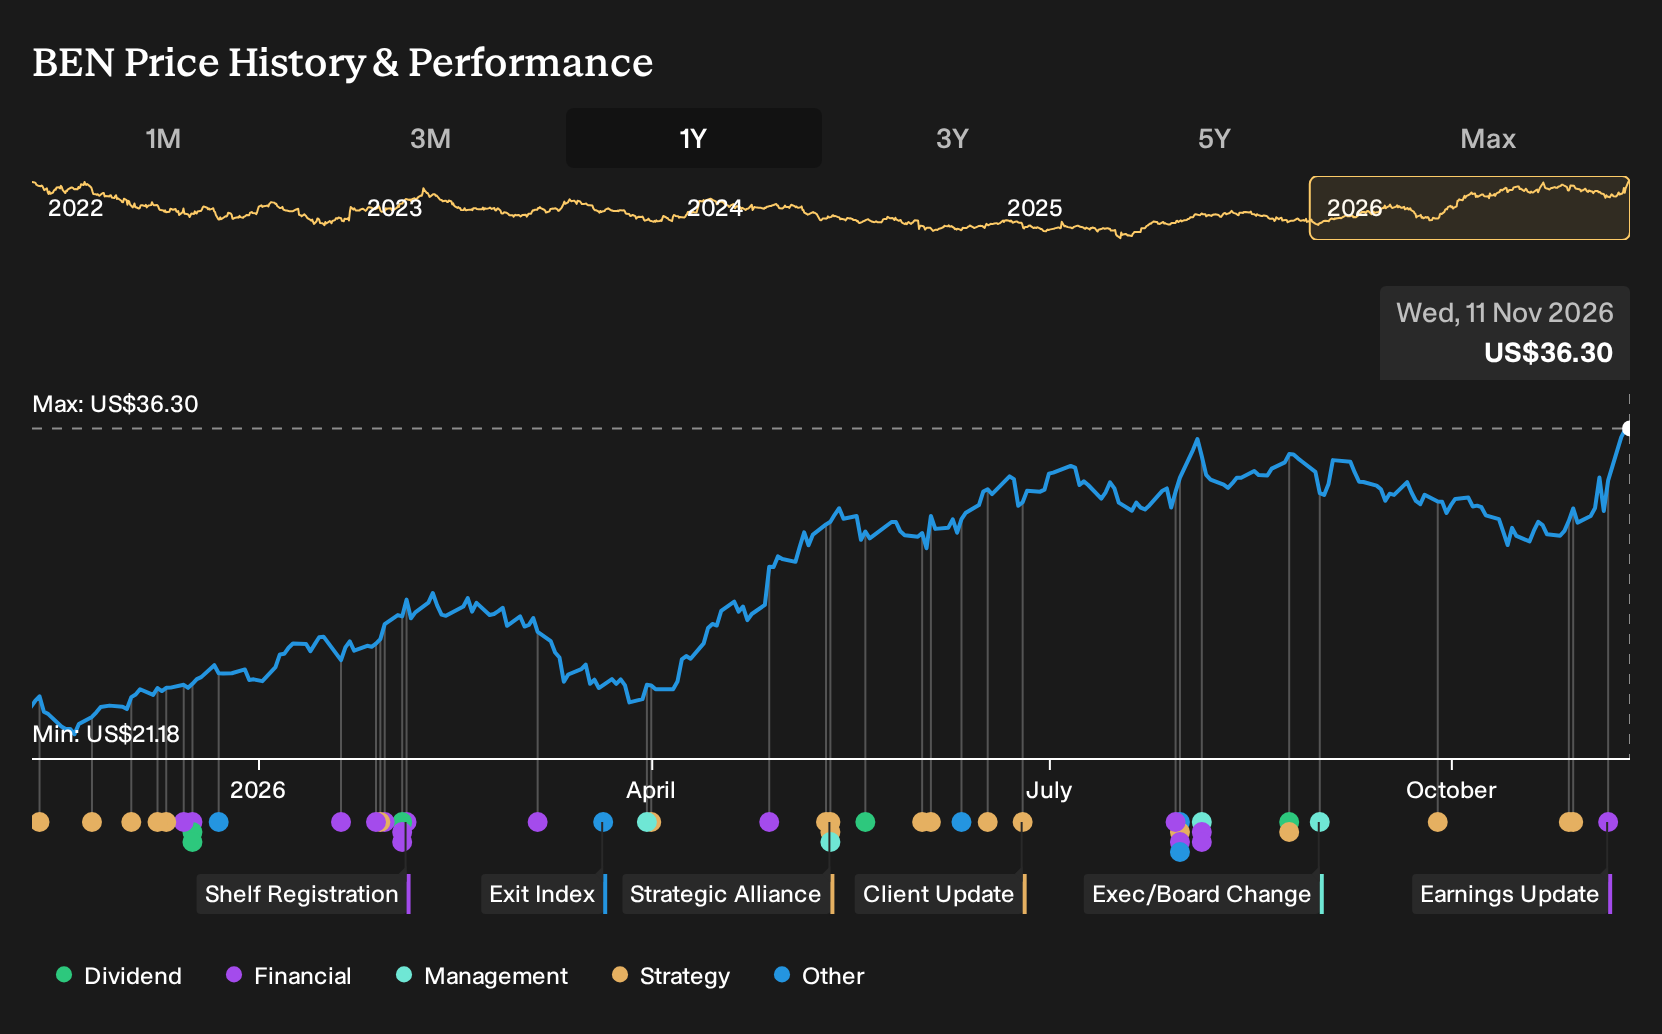
- Franklin Templeton reported higher fourth quarter and full year 2026 sales, revenue, net income and earnings per share compared with the prior year. This highlights stronger profitability from its core investment management activities.
- The launch of two new Nasdaq listed ETFs that blend U.S. equities with indirect Bitcoin exposure adds a differentiated product line to Franklin Templeton's fee earning platform.
- We will look at how Franklin Templeton's investment narrative is influenced by the jump in full year net income and earnings.
Scan how Franklin Templeton’s earnings jump and new Bitcoin themed ETFs compare with other asset managers by reviewing the hand picked 32 high quality undervalued stocks in this space.
Franklin Templeton Investment Narrative Recap
To own Franklin Templeton, you need to believe the asset manager can keep turning its broad product set and global reach into steady fee income, even while pricing pressure and platform bargaining power keep fees tight. The analyst consensus Narrative on Simply Wall St ties that story to higher margin alternatives, multi asset and digital products becoming a larger share of the mix.
The latest full year numbers, with revenue of US$9.4b and net income of about US$1.1b, show a much higher earnings base than a year earlier. This supports that thesis but does not remove the main near term swing factor. The key catalyst still rests on sustaining net inflows into higher fee strategies, while the biggest risk remains fee and distribution pressure that could cap margins even if assets stay resilient.
The launch of the Franklin U.S. Equity Bitcoin DRIP Index ETF and Franklin U.S. Innovation Bitcoin DRIP Index ETF is the clearest recent operational move tied to that story. These funds sit alongside Franklin Templeton’s existing ETF and digital asset efforts and add a different way to earn fees from U.S. equity exposure with indirect Bitcoin exposure layered on top.
Both products keep Bitcoin as a secondary allocation, starting at 5% and using dividends from the underlying shares to add to the crypto sleeve over time. That structure creates a fresh talking point with advisers and platforms but also pulls Franklin Templeton deeper into an area with regulatory, technology and market structure risks, so execution and risk controls will matter as much as investor demand.
Franklin Templeton’s current analyst storyline centers on projected revenues of about US$9.2b and earnings of roughly US$1.7b by 2029. This implies broadly flat revenue each year and an earnings increase of about US$0.6b from the US$1.1b level today.
Discover why Franklin Templeton's fair value appears to be essentially aligned with its current price.
Exploring Other Perspectives
One alternate view focuses on Franklin Templeton’s push into higher margin products as a potential upside catalyst. The most optimistic analysts were already penciling in earnings of about US$2.1b on roughly US$9.2b of revenue by 2029, above consensus. Those forecasts came before this earnings jump and the Bitcoin themed ETF launches, so you may want to compare several viewpoints and decide which story feels more realistic to you.
Explore 5 other Franklin Templeton fair value estimates, including one that suggests as much as 39% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Franklin Templeton research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Franklin Templeton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Franklin Templeton's overall financial health at a glance.
Looking For More Ideas Beyond Franklin Templeton?
If Franklin Templeton has you thinking about portfolio upgrades, it can help to scan a wider field of opportunities that share some of the qualities you value most. The Simply Wall St Screener lets you filter for very different types of stocks, so you can match ideas to your risk tolerance, time horizon and income needs.
- For investors who care most about quality at a reasonable price, start with companies that screen well on both fundamentals and valuation using the 32 high quality undervalued stocks.
- If capital preservation and steadier profiles are your priority, narrow the universe to businesses that clear our balance sheet checks through the list of solid balance sheet and fundamentals (23 results).
- For those hunting for potential early stage opportunities with room to grow, consider filtering the market by financial strength and price using the 12 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com