


- Selective Insurance Group has been highlighted as a value oriented insurer, with P/E and P/S ratios below industry averages and supported by a favorable earnings outlook and meaningful contribution from net investment income.
- The combination of an A grade for Value and investment income that is supported by higher yields and growing invested assets underscores how much of Selective Insurance Group's earnings power is currently coming from its balance sheet as well as its underwriting.
- We will now examine how Selective Insurance Group's value rating and strong net investment income profile could influence its broader investment narrative.
Scan beyond Selective Insurance Group and line up other value focused insurers by running the hand picked 32 high quality undervalued stocks alongside SIGI's current valuation profile.
Selective Insurance Group Investment Narrative Recap
To own Selective Insurance Group, you need to believe the insurer can keep underwriting discipline tight while casualty claim severities stay elevated and social inflation remains a headwind. The analyst consensus narrative on Simply Wall St leans on the idea that technology investments and pricing actions hold combined ratios in check. The recent focus on strong value grades and healthy net investment income does not materially change that near term operating catalyst.
The biggest swing factor right now is whether casualty trends and prior year reserve development stay manageable as management re underwrites weaker books and accepts slower Standard Commercial premium growth. The main risk is that persistent loss pressure and tighter regulation strain earnings volatility and limit revenue, despite Selective Insurance Group's improving net income and 9.2% net margin.
The most relevant piece of context to this value focused news is the growing role of net investment income in Selective Insurance Group's story. After tax NII of about US$119m in 2Q 2026 and updated 2026 guidance of US$480m show how much of the earnings base is now tied to the investment portfolio rather than pure underwriting alone.
For you as a shareholder, that means catalysts are increasingly split between operational moves and balance sheet productivity. Stronger investment returns can help absorb casualty volatility and stricter underwriting that already links to falling Standard Commercial new business, but reliance on higher yielding assets also makes execution on credit quality, duration and reinvestment decisions more important to the overall outlook.
Selective Insurance Group's narrative projects US$5.5b revenue and US$575.2m earnings by 2029. This aligns with analysts who anticipate relatively stable yearly revenue and an earnings increase of about US$86.8m from US$488.4m today.
Uncover why Selective Insurance Group's fair value appears to be effectively aligned with its current price.
Exploring Other Perspectives
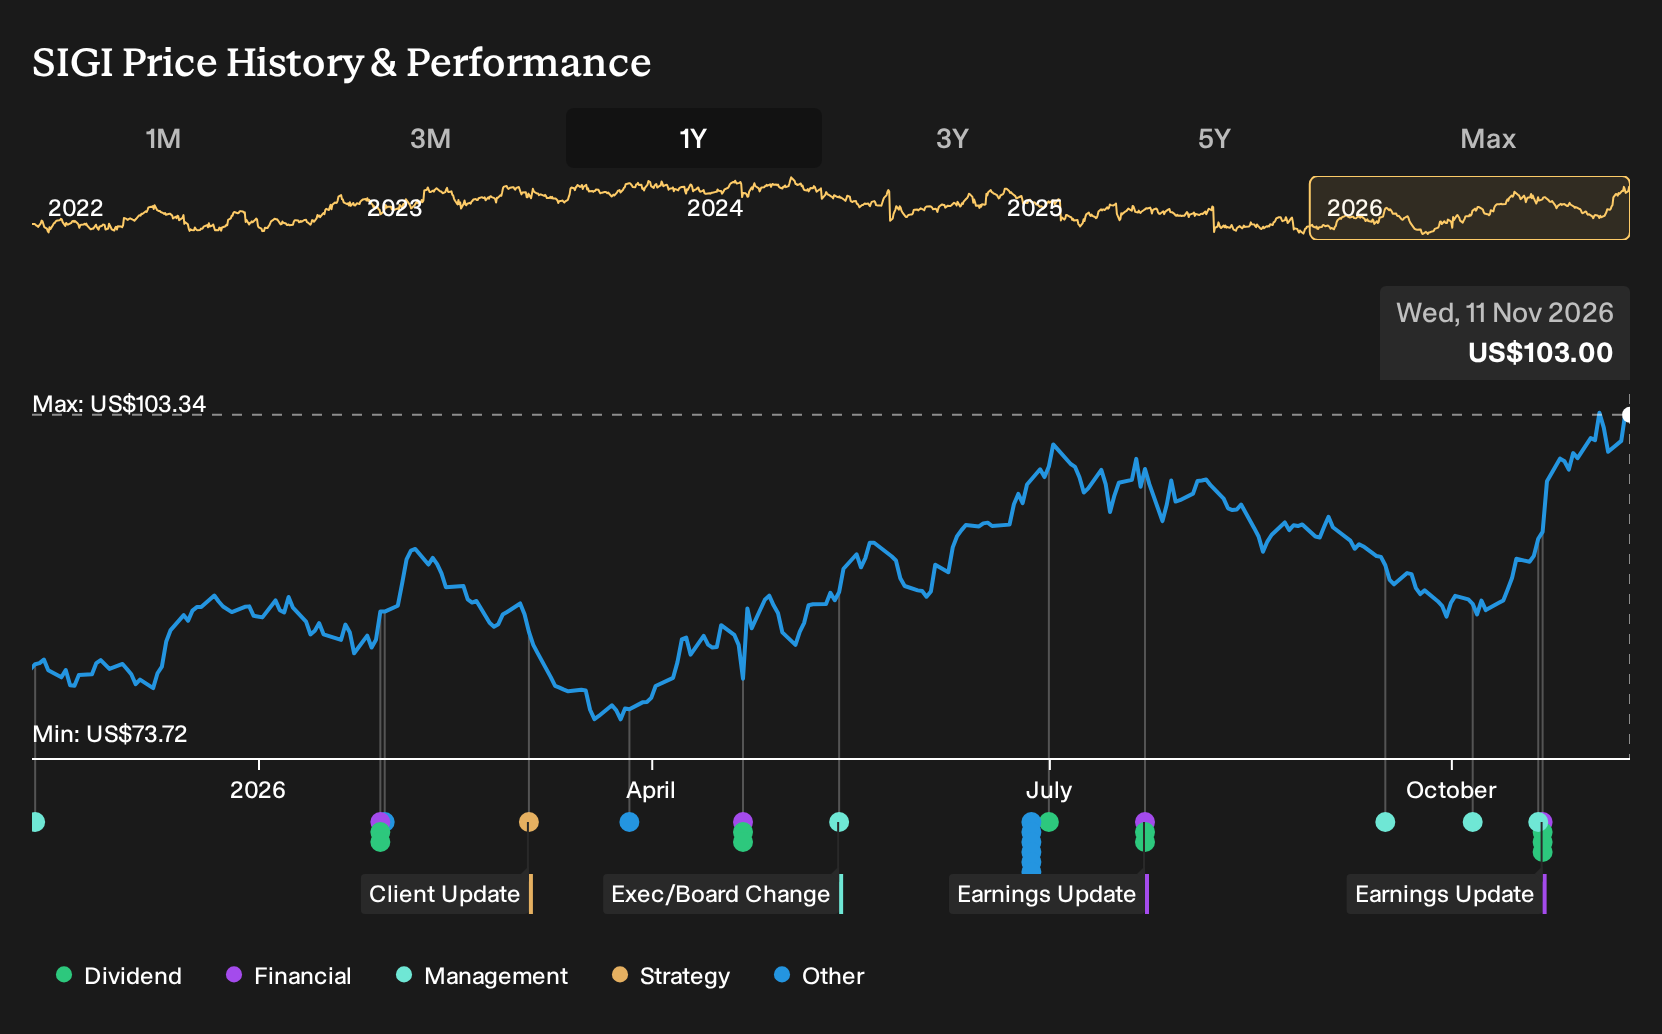
Community views on Selective Insurance Group are wide. Two fair value estimates from the Simply Wall St Community range from about US$101.86 to US$201.51 per share, reflecting very different expectations. When you set those against casualty loss trends near 9% and commercial auto severity around 10%, you can see how quickly sentiment can shift. Use these contrasts to pressure test your own assumptions.
Explore another Selective Insurance Group fair value estimate, including one that suggests it could be worth just $101.86.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Selective Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Selective Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Selective Insurance Group's overall financial health at a glance.
Looking for more investment ideas beyond Selective Insurance Group?
Once you have a view on Selective Insurance Group, it can help to widen the lens and compare it with other stocks that share some of the same qualities you care about, whether that is value, resilience or income.
- If you want potential value combined with financial strength, scan a curated list of solid balance sheet and fundamentals (23 results) to see which businesses pair disciplined balance sheets with healthier fundamentals.
- If your priority is limiting downside risk, focus on stability first and see which companies make it into a 30 resilient stocks with low risk scores that screens for resilience rather than just fast growth.
- If you are hunting for opportunities that are not yet widely followed, sift through a 20 high quality undiscovered gems where the fundamentals, not the headlines, do the talking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com