


PROCEPT BioRobotics earnings put growth and losses in focus
PROCEPT BioRobotics (PRCT) just released third quarter 2026 results and reaffirmed its full year revenue outlook, a combination that highlights growing sales alongside continued losses.
The business reported third quarter revenue of US$98.29 million, compared with US$83.33 million in the same period last year. Net loss for the quarter was US$26.52 million, with basic loss per share from continuing operations of US$0.46, versus US$21.41 million and US$0.38 respectively a year ago.
Across the first nine months of 2026, PROCEPT BioRobotics generated sales of US$275.92 million against US$231.67 million for the prior year period. Over that span, the firm recorded a net loss of US$85.02 million, or US$1.49 basic loss per share from continuing operations, compared with a loss of US$65.73 million, or US$1.19 per share, in the previous year period.
Alongside these figures, management reiterated its 2026 revenue guidance of US$390 million to US$410 million. The company states that this would represent growth of 27% to 33% compared with last year. For investors, that pairing of expanding top line and ongoing losses is the core question around PROCEPT BioRobotics today.
Investors have reacted positively in the short term, with PROCEPT BioRobotics posting a 7.76% 7-day share price return and a 19.26% 30-day share price return after reaffirming its 2026 revenue outlook, even though the 1-year total shareholder return is down 24.15%.
Scan a curated set of 87 robotics and automation stocks to see how other automation players compare with PROCEPT BioRobotics following this latest earnings and guidance update.After a sharp bounce on reaffirmed guidance and with PROCEPT BioRobotics trading slightly above the average analyst target, the debate is simple. Is the meaningful upside still ahead, or was most of it reflected in this latest move?
Most Popular Narrative: 61% Undervalued
Compared with PROCEPT BioRobotics' last close at $23.34, the leading Simply Wall St Community narrative points to a fair value of $60. According to Betsareoff, a Simply Wall St Community investor who wrote the narrative, that gap reflects sentiment rather than fundamentals.
I have been an investor in PRCT since before IPO. The wild fluctuations in share price recently make no sense. The sell side analyst who chased the share price up to highs in 2024 (when the price was way too frothy) are doing the same thing now by revising the share price lower and lower, when clearly the company is still doing a great job. The recent downgrade by Leerink, citing PAE as a possible headwind for PRCT growth, is in direct opposition to what Larry Wood (CEO) stated at the last earnings call. To quote Larry Wood, “I don’t think PAE is a headwind for us at all. I think PAE is a big red herring. It’s a procedure that really does not get performed in any volume in Europe. And the reason it doesn’t get performed is because it doesn’t get paid for because it’s not a very good procedure.” So if you believe Larry Wood, then the company has been grossly oversold and looks very very cheap down here. If PRCT hit the Q2 numbers watch all the sheep suddenly revise their target prices back up again. I think fair value is still up at $47. PRCT had a reassessment of how to report handpiece sales versus procedures and therefore there was a shortfall on revenue. Clearly they could have stuck with the old model and revenue would have been better. Larry is doing a great job of making reporting a direct reflection of procedures being done. If the numbers are delivered, watch this thing fly.
See why 6 investors see PROCEPT BioRobotics as 61% undervalued.
Result: Fair Value of $60 (UNDERVALUED)
Still, the narrative can break if PROCEPT BioRobotics' losses stay elevated or if procedure adoption slows, which would reduce confidence in those fair value estimates.
Find out about the key risks to this PROCEPT BioRobotics narrative.
Another View: PROCEPT BioRobotics looks expensive on cash flow
There is a sharp contrast once you move from the community fair value to the SWS DCF model. On that framework, PROCEPT BioRobotics at $23.34 trades well above an estimated future cash flow value of $10.17, which points to an overvalued stock rather than a bargain.
For anyone weighing those conflicting signals, it helps to see how the full cash flow model fits together in detail through the Look into how the SWS DCF model arrives at its fair value..
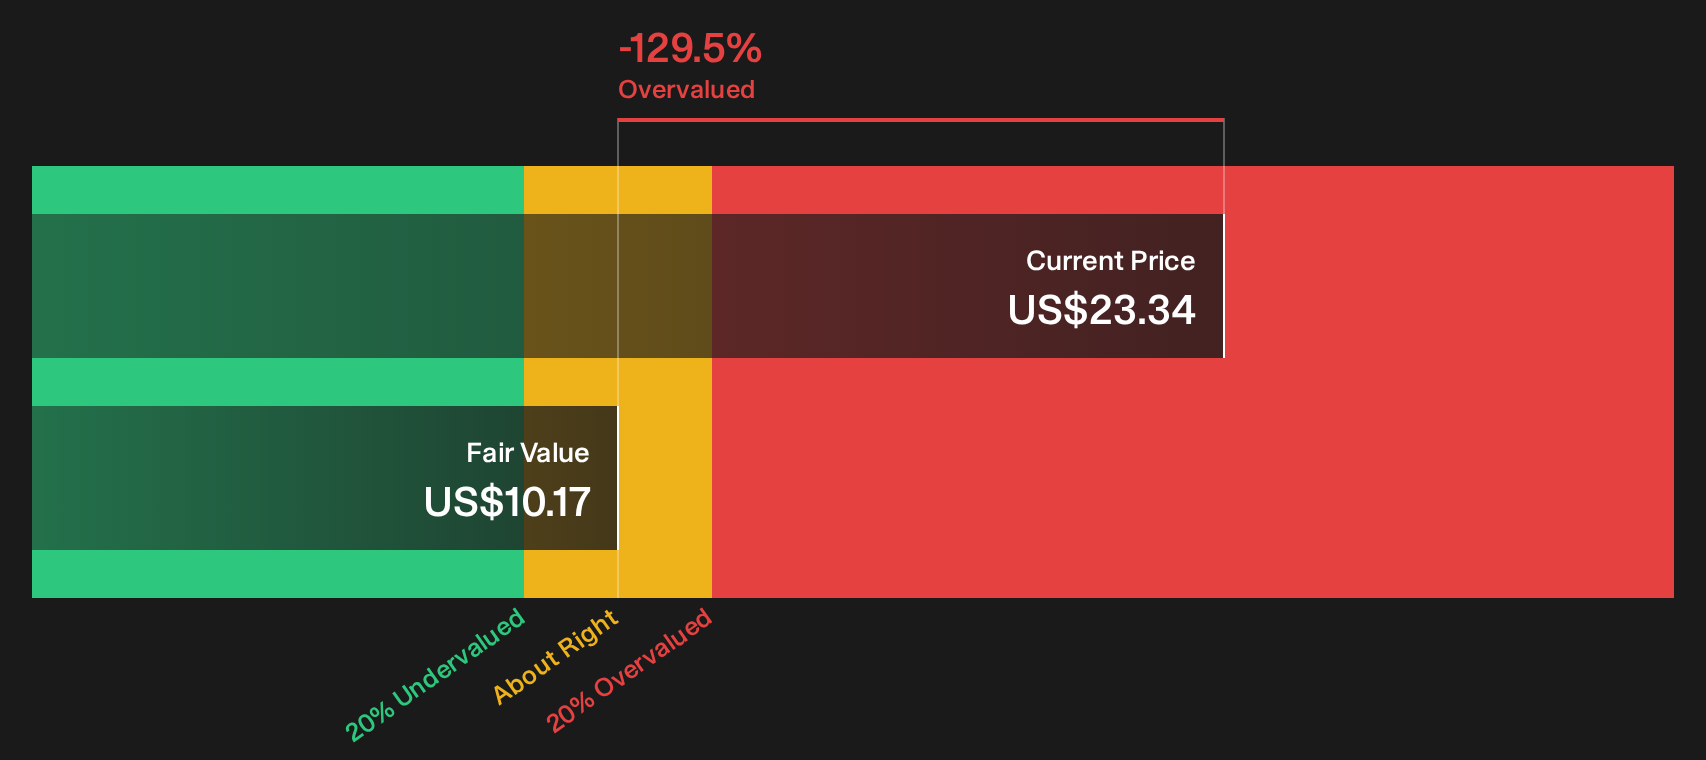
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out PROCEPT BioRobotics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the PROCEPT BioRobotics story so far. Act while sentiment is still split, and weigh the potential upside against the potential downside with 1 key reward and 1 important warning sign.
Looking for more PROCEPT BioRobotics style investment ideas?
Do not stop with PROCEPT BioRobotics. Broader context around quality, value and risk can sharpen your judgment and keep you from anchoring on a single story.
- Target resilient balance sheets and steady fundamentals by scanning a curated list of solid balance sheet and fundamentals (23 results) that can help you stress test your portfolio.
- Hunt for quality at a reasonable price by reviewing a focused 32 high quality undervalued stocks that filters for both strong financials and supportive valuations.
- Add a potential safety net of income and stability by checking a concentrated 6 dividend fortresses that screens for higher yield with discipline.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com