


After years of pouring billions into artificial intelligence (AI), investors appear to be losing some of their appetite for the AI trade, as Wall Street's once red-hot enthusiasm gives way to a much-needed reality check. The growing skepticism is taking a toll on some of the market's biggest AI and semiconductor names, and Applied Materials (AMAT) has not been spared.
The stock has seen a significant chunk of its impressive 2026 rally evaporate, shedding double-digit percentage points over the past month as investors rotate away from high-flying AI and chip stocks, seek safer alternatives, and lock in profits after years of outsized gains. The growing unease goes beyond profit-taking.
Investors are increasingly questioning whether the enormous capital being funneled into AI infrastructure will generate sustainable returns anytime soon. Adding to the uncertainty, supply chain warnings have clouded the industry's outlook, while a sweeping Democratic victory in the U.S. midterm elections has revived fears of tighter AI regulations, potential industry crackdowns, and stricter export restrictions on semiconductor technology.
Yet, despite the bruising selloff, Applied Materials is once again drawing investor attention. Shares are moving higher as market participants position themselves ahead of the company's fiscal fourth-quarter 2026 earnings report, due after the market closes on Thursday, Nov. 12. With AMAT stock still down more than 20% over the past month, could this pre-earnings rebound signal an attractive opportunity to buy the dip, or is Wall Street's AI pullback far from over?
About Applied Materials Stock
Established in 1967 and headquartered in Santa Clara, California, Applied Materials is one of the key players in the global semiconductor ecosystem. Rather than producing finished chips, the company specializes in developing the advanced equipment, engineering solutions, software, and services that semiconductor manufacturers need to make them. Its technologies support the production of a wide range of chips, from processors and memory to the semiconductors used in smartphones, automobiles, data centers, and AI applications.
As chip designs grow more sophisticated and the need for high-performance computing accelerates, Applied Materials continues to play a crucial role in helping manufacturers build smaller, faster, and more power-efficient semiconductors. Despite its importance to the industry, the company, currently valued at approximately $313.53 billion, has come under significant selling pressure as Wall Street's enthusiasm for AI-related investments starts to fade.
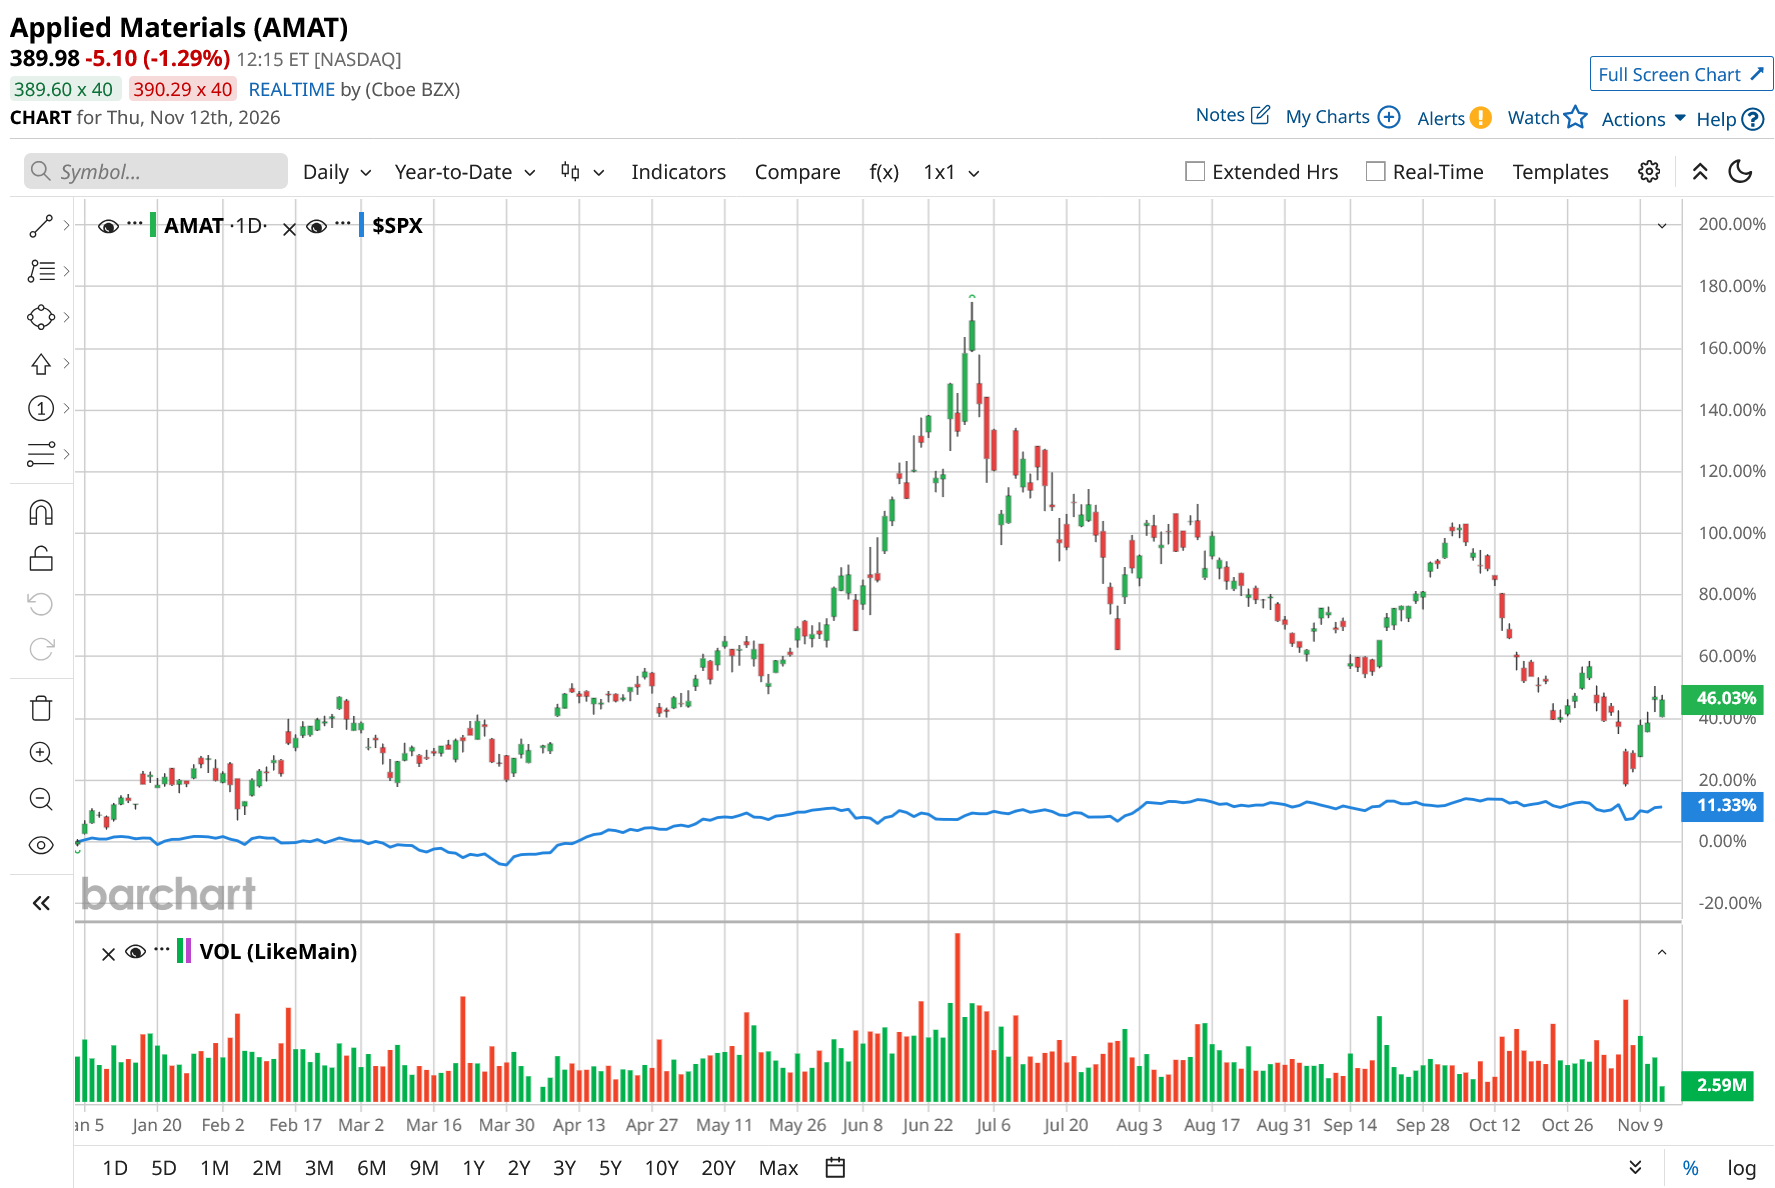
AMAT has been caught in the broader semiconductor selloff, with shares tumbling about 20% over the past month, dramatically underperforming the S&P 500 Index ($SPX), which has declined just 2.3% over the same period. The correction has also pushed the stock nearly 47% below its 52-week peak of $739.67, recorded in June.
Still, the recent weakness has not erased what has otherwise been a stellar year for the semiconductor equipment maker. With its earnings announcement approaching, investors appear to be stepping back into the stock, driving a 24% gain over the past five trading sessions alone. Zooming out, AMAT remains up an impressive 54% in 2026, comfortably outperforming the broader market's 11.4% advance over the same stretch.
Q3 Earnings Snapshot
Applied Materials set a new quarterly revenue record in fiscal third-quarter 2026, delivering results that exceeded Wall Street expectations on both the top and bottom lines. Reported on Aug. 13, the company's strong performance reflected the accelerating adoption of AI worldwide and the resulting demand for increasingly sophisticated semiconductor manufacturing equipment. Revenue climbed 25% year-over-year (YoY) to a record $9.12 billion, compared with $7.30 billion in the corresponding period last year, comfortably beating analysts' estimates of $9 billion.
Earnings growth was even stronger, highlighting the company's ability to translate higher sales into improved profitability. Non-GAAP earnings jumped 41% from the year-ago quarter to $3.50 per share, topping the consensus estimate of $3.39. Applied Materials also recorded further improvements in its margins, supported by a favorable mix of higher-value products and greater operational efficiency. Non-GAAP gross margin increased 1.5 percentage points to 50.4%, while operating margin expanded 3.3 percentage points to 34%.
A closer look at the individual businesses shows that Semiconductor Systems continued to drive the bulk of the company's growth. The segment generated $7.04 billion in revenue, marking a 27% increase from the same quarter last year. Meanwhile, Applied Global Services (AGS) added another $1.78 billion to quarterly revenue, delivering steady growth. Cash flow was another major highlight, with cash generated from operations reaching a quarterly record of $3.04 billion.
The company returned $860 million to shareholders during the period, comprising $440 million in stock buybacks and $420 million in dividend distributions. Notably, Applied Materials has now recorded 13 consecutive quarters of YoY gross margin expansion, highlighting the consistency of its profitability improvements. Looking ahead, management anticipates revenue growth to remain robust throughout the second half of the calendar year, with DRAM, leading-edge foundry-logic, and advanced packaging expected to be key contributors.
The company is also stepping up investments in manufacturing capacity to position itself for the anticipated increase in demand through the end of the decade. For fiscal year fourth-quarter 2026, management issued revenue guidance in the range of $9.75 billion to $10.75 billion. Non-GAAP earnings per share are expected to fall between $3.82 and $4.22, signaling expectations for another strong quarter.
How Do Analysts View AMAT Stock?
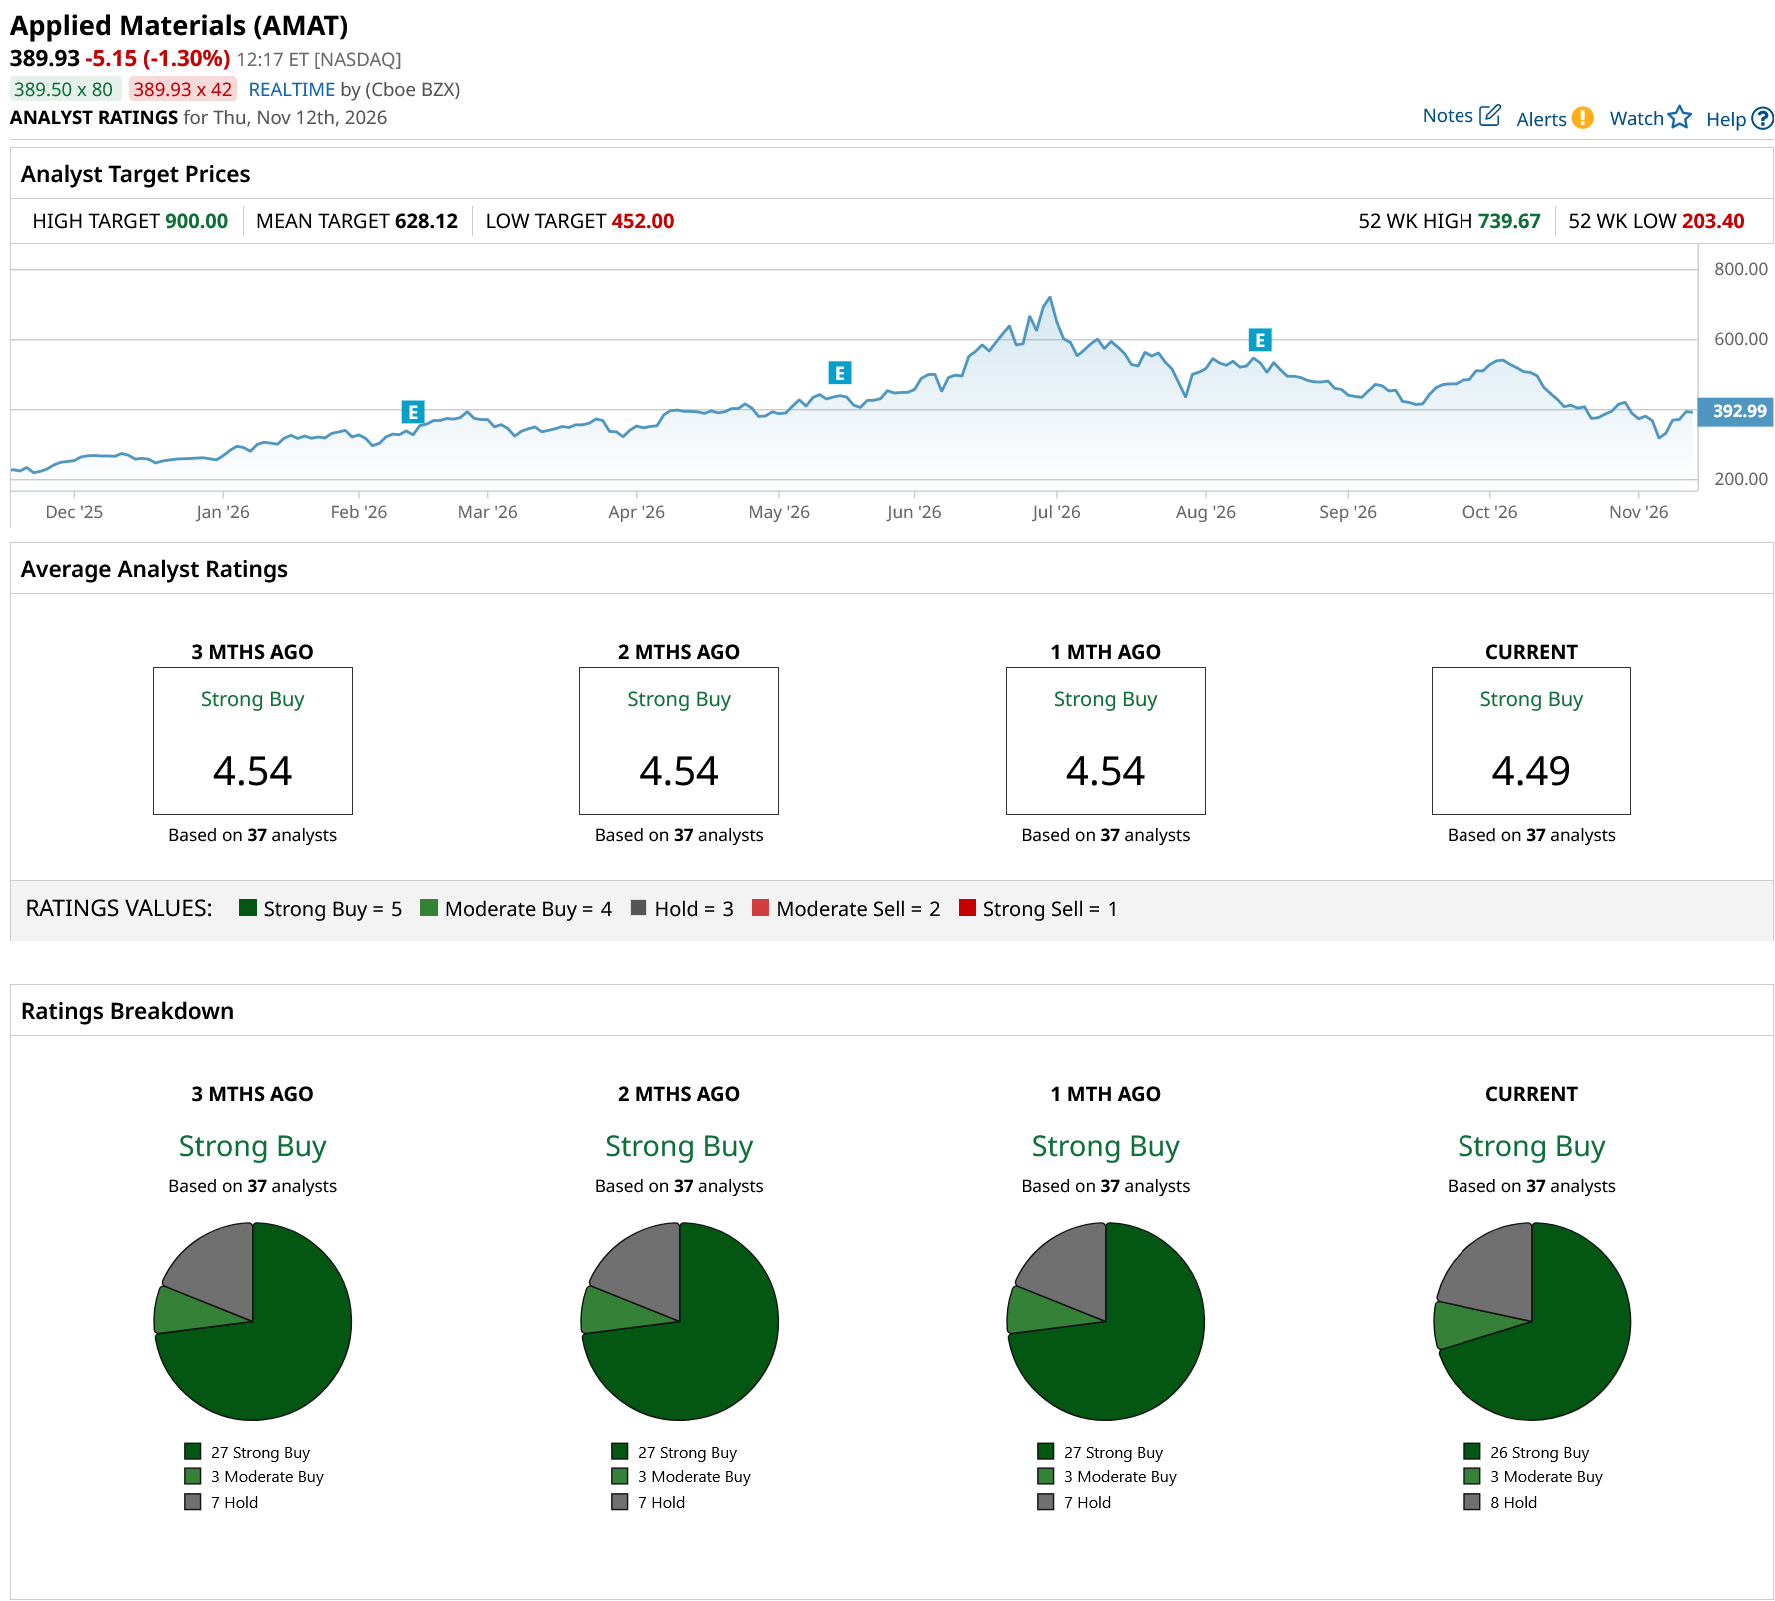
Despite the recent selloff, Wall Street remains firmly bullish on AMAT, with the stock carrying a consensus “Strong Buy” rating. Among the 37 analysts covering AMAT stock, 26 recommend a “Strong Buy,” three favor a “Moderate Buy,” and eight maintain a “Hold” rating. The average price target of $628.12 points to a potential upside of 61%, while the Street-high target of $900 leaves room for a staggering 131% rally from current levels.
On the date of publication, Anushka Mukherji did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.