


- Viatris reported third quarter 2026 revenue of US$3,749.5 million with a net loss of US$325.3 million, and raised full year 2026 revenue guidance slightly while affirming a US$0.12 quarterly dividend declared in early November.
- The combination of a smaller year to date net loss, a tighter full year revenue range and continued dividend payments suggests that Viatris is focusing on earnings quality, cash discipline and shareholder returns, while product recalls and operational issues remain in the background.
- This article will examine how Viatris's raised 2026 guidance, despite reporting a quarterly loss, fits into the broader investment narrative.
Compare Viatris' guidance shift and dividend stance with a curated group of companies on our 32 high quality undervalued stocks, which pair resilient balance sheets with disciplined cash generation.
Viatris Investment Narrative Recap
To own Viatris, you need to believe the business can gradually shift its mix toward higher value products while keeping cash generation steady enough to manage its balance sheet and shareholder returns. The raised 2026 revenue guidance, despite a quarterly net loss of US$325.3 million, points to reasonably stable near term operations rather than a sharp inflection point.
The key short term catalyst remains execution on higher margin launches and cost savings described in the analyst consensus Narrative on Simply Wall St. This would allow earnings quality to improve despite price pressure on older drugs. The biggest current risk sits in manufacturing and regulatory execution, where issues like facility remediation or product recalls can eat into margins and distract management.
The recent voluntary Class III recall of certain Telmisartan and Amlodipine tablets is the announcement that links most directly to this earnings update. It reinforces that Viatris operates a large, complex supply chain where quality deviations, even for a limited number of 30 count bottles, can add incremental cost and operational friction over time.
For catalysts, that recall sits alongside ongoing facility remediation in places such as Indore and Nashik. Analysts already expect this to trim second half 2026 revenue by US$100 million to US$150 million. Your read on Viatris will likely hinge on whether quality control and manufacturing systems can tighten enough to keep such issues contained while the firm leans into higher value products and the Pacira acquisition story.
Viatris' current analyst framework points to revenues of US$15.9b and earnings of US$704.2 million by 2029, based on revenue growth of 2.6% per year and a move from current earnings of a US$410.7 million loss to projected profits. This implies an earnings swing of roughly US$1.1b from today to the 2029 consensus estimate.
Uncover how Viatris' fair value indicates a 5% potential downside to its current price, suggesting a valuation premium that leaves little room for error.
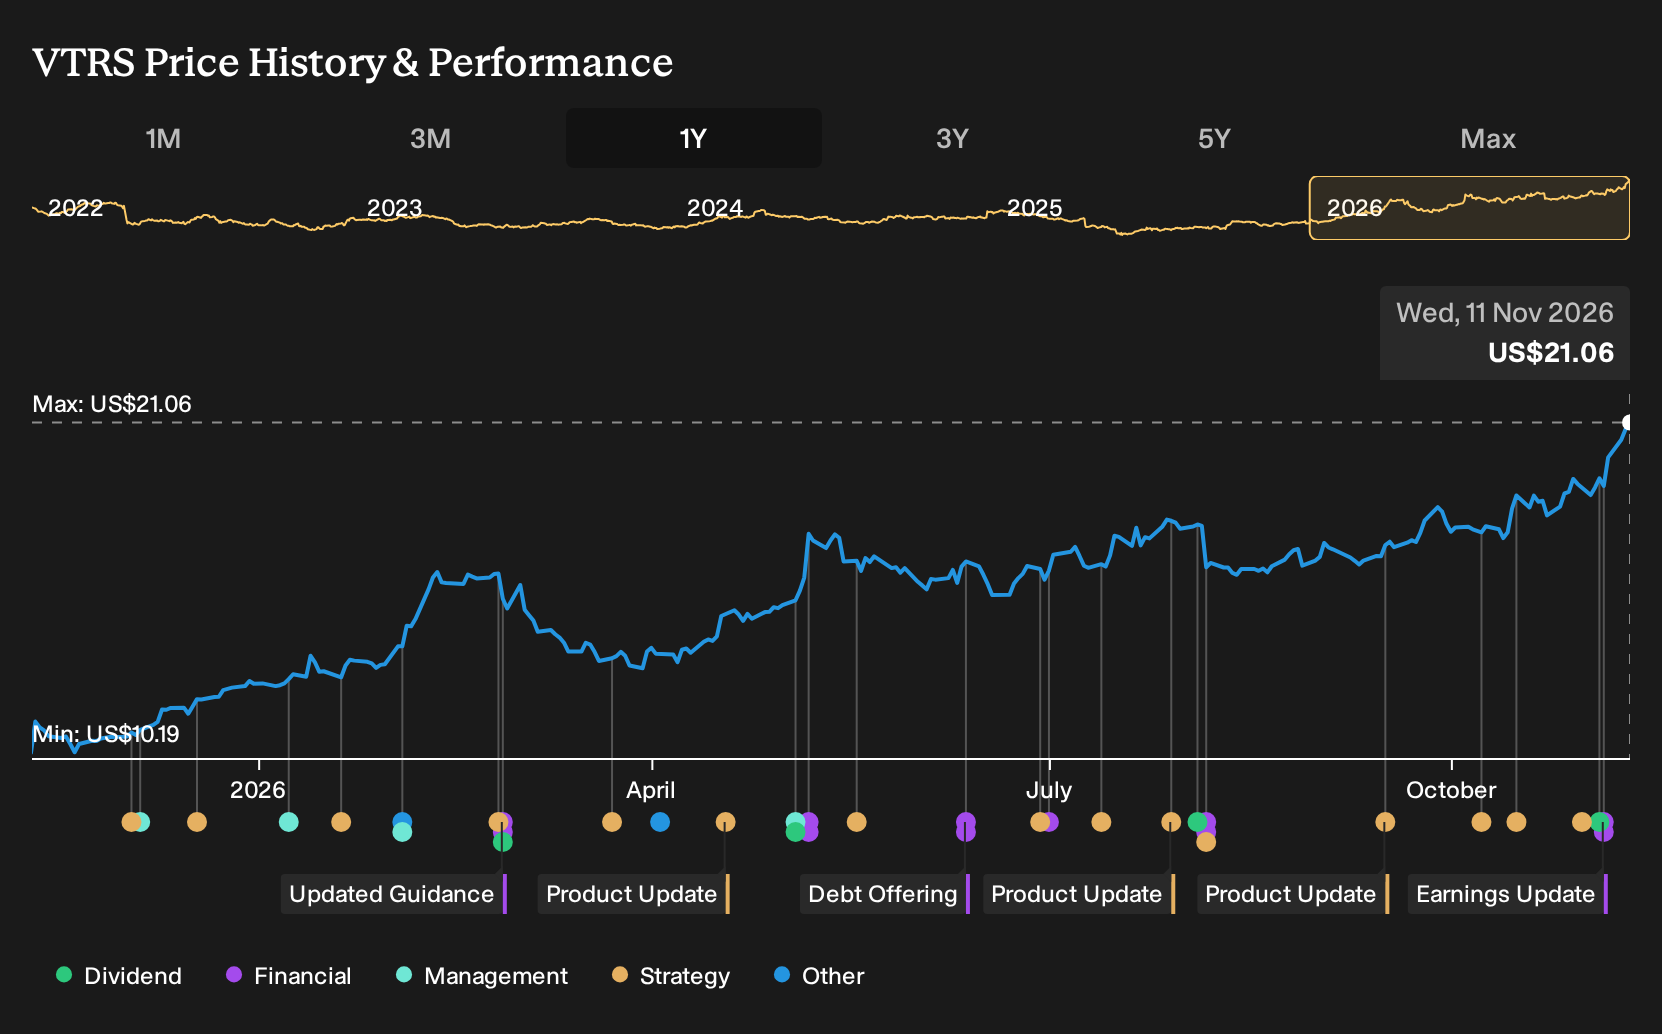
Exploring Other Perspectives
One alternative reading of Viatris focuses less on product recalls and more on the Pacira deal possibly straining free cash flow. The lowest analysts were already working with slower revenue growth near 1.9% a year and 2029 earnings of about US$564.3 million. After this guidance raise and dividend affirmation, those pre news assumptions may look conservative or may gain weight, depending on how you view execution risk. That gap in expectations is exactly why you should compare several narratives before deciding how Viatris fits your own portfolio.
Explore 4 other Viatris fair value estimates, including one that suggests there may be as much as 5% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Viatris research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Viatris. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Viatris' overall financial health at a glance.
Looking for more investment ideas beyond Viatris?
If Viatris has prompted you to rethink how you balance quality, income and risk, it can help to scan a wider opportunity set using the Simply Wall St Screener and compare how other businesses stack up on the same metrics.
- For investors who want staying power to matter as much as returns, focus on companies with sturdier finances through the list of solid balance sheet and fundamentals (23 results).
- If capital protection sits high on your priority list, you might prefer stocks that score well on stability in the 30 resilient stocks with low risk scores.
- Those hunting for less crowded opportunities can cast a wider net across under-followed businesses using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com