


Progyny has delivered a strong share price run recently, which puts a spotlight on whether the current valuation is properly supported by the fertility benefits provider's earnings power. After that kind of move, the question for anyone looking at Progyny stock is how much of its profit story is already reflected in the price.
- Progyny has returned 51.6% over the past year, which raises the stakes on whether recent enthusiasm is aligned with what the business is earning today.
- Management recently reported record profitability and higher expected earnings, which can influence how investors think about the durability and timing of future profit streams that support the valuation.
- The analysts covering Progyny have run their own numbers. See what analysts think Progyny's shares could be worth.
The issue now is whether Progyny's current share price around US$36.50 is justified by its earnings when set against the Fair Ratio benchmark.
If you want to test the same earnings driven valuation question you are asking about Progyny across a wider opportunity set, take a look at 32 high quality undervalued stocks.
Does Progyny Look Fairly Valued on Earnings?
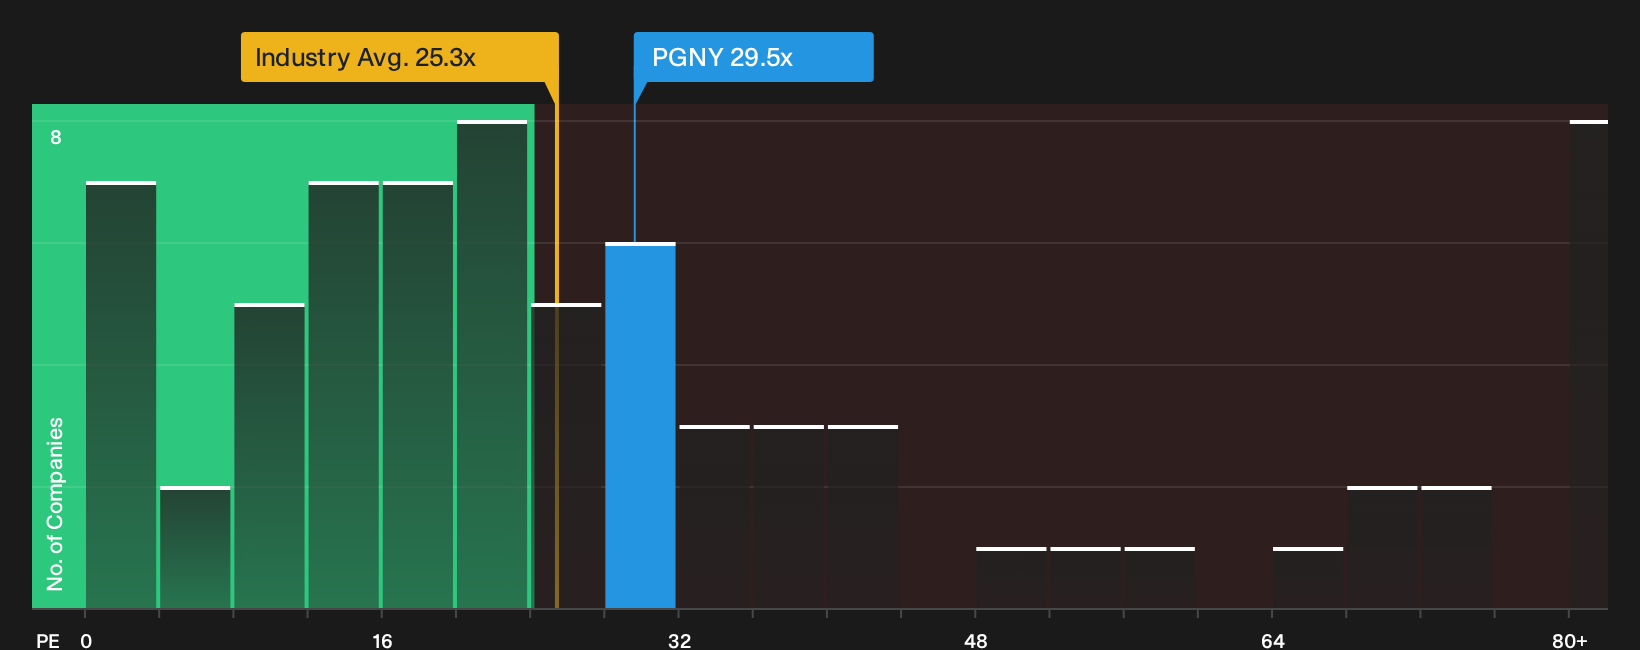
P/E works well for Progyny because the business is already earning profits that can be compared directly with what investors are paying for each dollar of earnings. At a current P/E of 29.5x, Progyny trades above the broader Healthcare sector average of 25.3x but below the 39.6x level implied by peers in its space.
Because record Q3 earnings and the raised 2026 guidance are fresh in investors' minds, this gap suggests the stock is no longer priced as a clear bargain yet is not being valued as aggressively as some peers. The P/E sits slightly above the tailored Fair Ratio benchmark, which points to a valuation that is about right on this earnings based lens and leaves the share price closely aligned with what the model suggests is fair. Explore the numbers behind Progyny's P/E valuation.
The Progyny Narrative: What Would Justify Today's Price?
Progyny Narratives on Simply Wall St pick up where the P/E puzzle leaves off by spelling out the specific combinations of future growth, margins and earnings that would need to occur for the stock to trade meaningfully higher or lower than it does today on the market. Instead of a single valuation number, Narratives outline the future path that figure rests on so you can watch how Progyny's actual results and management decisions compare with that implied roadmap over time on the Community page.
Progyny splits opinion around how much credit the current price gives to its cash generation and women’s health expansion.
Bull case: 9% undervalued
The bullish analyst Narrative on Simply Wall St focuses on Progyny’s cash engine, health plan reach and capital returns.
"Progyny's consistent conversion of at least 75% of adjusted EBITDA into operating cash flow, with trailing 12 month operating cash flow around US$201 million, leaves meaningful capacity to redirect future free cash…"
Discover why this Narrative puts Progyny at 9% undervalued.
Bear case: roughly fairly valued
The analyst consensus Narrative on Simply Wall St sees less upside if utilization and margins do not keep pace with expectations.
"If Progyny continues to show only modest revenue growth alongside weaker unit volumes, limited distribution scale, and little movement in adjusted operating margins relative to larger peers, investors may question the ability to reach greater scale…"
Explore why this Narrative puts Progyny at roughly fairly valued.
One more angle on Progyny that could change how you see the stock
All the earnings work still leaves one big open question, which is how professional analysts see Progyny a few years from now and how that compares with what you are paying today. Explore where analysts expect Progyny to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com