


- DXP Enterprises reported Q3 2026 sales of US$587.18 million and net income of US$26.87 million, with higher basic and diluted earnings per share from continuing operations than a year earlier.
- The company paired record Q3 revenue with increased operating profitability across all segments, supported by five acquisitions and continued expansion of its DXP Water platform.
- This report will now explore how DXP Enterprises' record Q3 sales and stronger profitability could reshape the broader investment narrative for the business.
DXP Enterprises Investment Narrative Recap
To own DXP Enterprises, an investor needs to believe the business can keep compounding earnings from its mix of MRO distribution, higher value engineered solutions and the DXP Water platform while carrying meaningful debt. The analyst consensus Narrative on Simply Wall St leans on that idea. The latest quarter supports that story at an operating level, with record Q3 revenue, stronger profitability and five acquisitions feeding into a broader platform.
The near term swing factor is execution on integration and sustaining margin quality while servicing about US$842.5 million of total debt. Record Q3 results help ease concerns around recent Q1 misses but do not remove the risk that any earnings soft patch or weaker cash generation could make that leverage feel heavier.
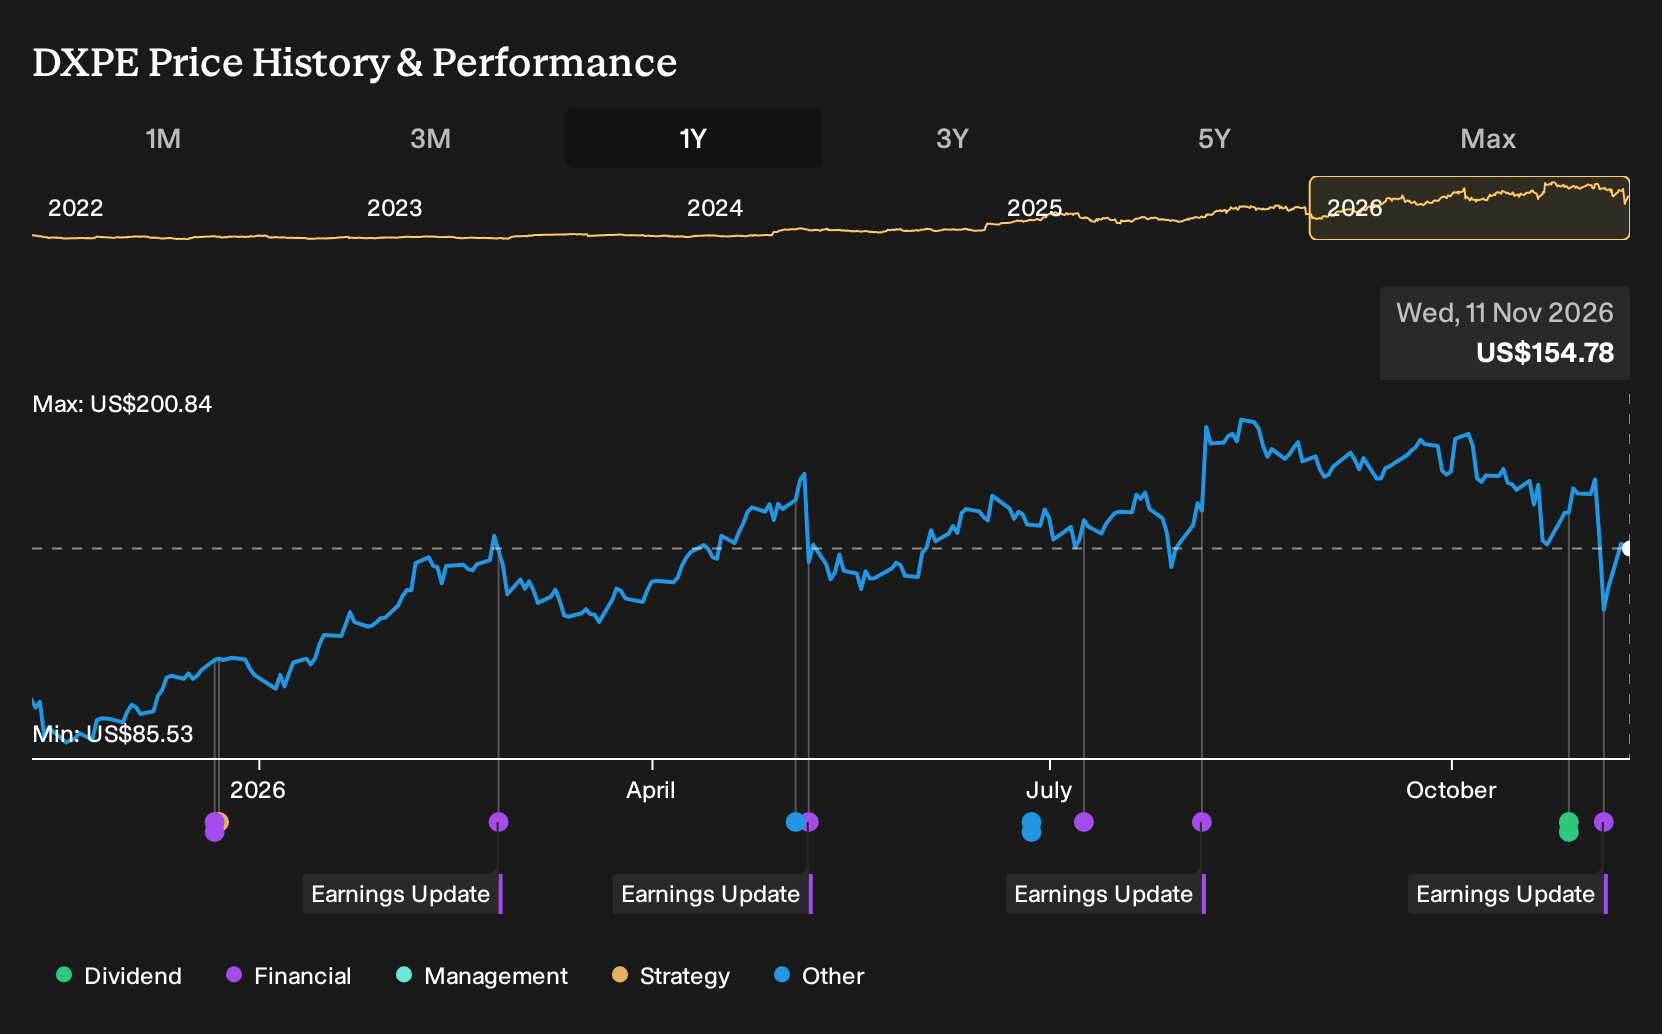
The most relevant fresh data point is the Q3 2026 earnings release itself. DXP Enterprises reported Q3 sales of US$587.18 million and net income of US$26.87 million, with both basic and diluted EPS from continuing operations higher than a year earlier. For the first nine months of 2026, sales reached US$1.69b and net income was US$75.56 million, which gives you a clearer run rate against the analyst consensus Narrative on Simply Wall St.
For catalysts, this update shows the acquisition program and DXP Water expansion are already embedded in reported numbers rather than sitting only in forecasts. The risk side is just as clear. With debt not well covered by operating cash flow and past market reactions to earnings shortfalls, the key operational test now is whether management can keep integrating acquisitions, protecting margins and generating enough cash to comfortably cover interest and obligations.
DXP Enterprises' analyst narrative projects US$2.8b in revenue and US$177.0 million in earnings by 2029. This assumes 7.9% yearly revenue growth and an earnings increase of about US$78.7 million from US$98.3 million today.
Uncover how DXP Enterprises' fair value indicates a 21% potential upside to its current price that could narrow quickly if sentiment continues to track Q3 momentum.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between about US$187.50 and US$219.87, which leaves room for both deep value and full pricing arguments around DXP Enterprises. Those retail views sit beside debt-related risks and acquisition-led catalysts, so you are seeing genuinely different playbooks. Explore them.
Explore another DXP Enterprises fair value estimate, including one that suggests as much as 42% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research and analysis.
- A great starting point for your DXP Enterprises research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DXP Enterprises. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate DXP Enterprises' overall financial health at a glance.
Looking For More Investment Ideas Beyond DXP Enterprises?
If DXP Enterprises is already on your watchlist, it can help to widen the lens and compare it with other businesses that share similar quality traits or different risk and return profiles. The Simply Wall St Screener offers several focused ways to do that, so you can line up DXP alongside peers that match your own preferences on fundamentals, balance sheet strength, or downside risk.
- If capital preservation sits high on your list, check out a group of comparatively steadier businesses through 30 resilient stocks with low risk scores that keeps the focus on resilience over drama.
- For investors who care most about strong finances and cleaner balance sheets, run your eye over a list of solid balance sheet and fundamentals (23 results) that can sit alongside DXP Enterprises in a more quality-focused watchlist.
- Those hunting for potential future favourites before the crowd arrives can scan a curated pool of 20 high quality undiscovered gems that may complement or contrast with your thesis on DXP.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com