


Aker BP’s latest project decision is back in focus after SLB (SLB) secured a subsea production systems contract for the Lyra field, putting the stock’s offshore exposure under closer investor scrutiny.
For context, SLB shares trade at US$50.96 after a 2.12% 1-day share price gain that partly offsets a recent 7-day dip. The 26.77% year-to-date share price return and 44.73% 1-year total shareholder return indicate that momentum has been building over a longer horizon as offshore contract wins and sector conferences keep the story in focus.
Scan for other offshore contractors with similar momentum and contract pipelines by running the curated 43 power grid technology and infrastructure stocks alongside your SLB research.
SLB’s recent contract win and price swing can be interpreted either as a clear signal about the underlying business or as sentiment chasing offshore headlines. The valuation work starts by separating those two stories.
Most Popular Narrative: 18% Undervalued
On Simply Wall St, the analyst consensus Narrative suggests a fair value for SLB of about $62 per share compared with the latest close at $50.96, which frames the Lyra contract as part of a wider earnings story that extends beyond one subsea award.
Rapid scaling of SLB’s Data Center Solutions business, backed by a backlog that underpins an annualized revenue run rate exceeding US$2 billion by the end of 2027 and medium term targets of US$4.5 billion to US$5.0 billion of data center revenue and US$700 million to US$800 million of adjusted EBITDA in 2028 after the Kelvion acquisition, introduces a large, capital light revenue stream that can add meaningfully to consolidated revenue, EBITDA and cash generation.
See why 177 investors see SLB as 18% undervalued.
Result: Fair Value of $62 (UNDERVALUED)
Still, the SLB story can break if Middle East disruption drags on, or if data center and Kelvion targets slip, leaving earnings more tied to traditional cycles.
Find out about the key risks to this SLB narrative.
Another View: What SLB’s P/E Is Telling You
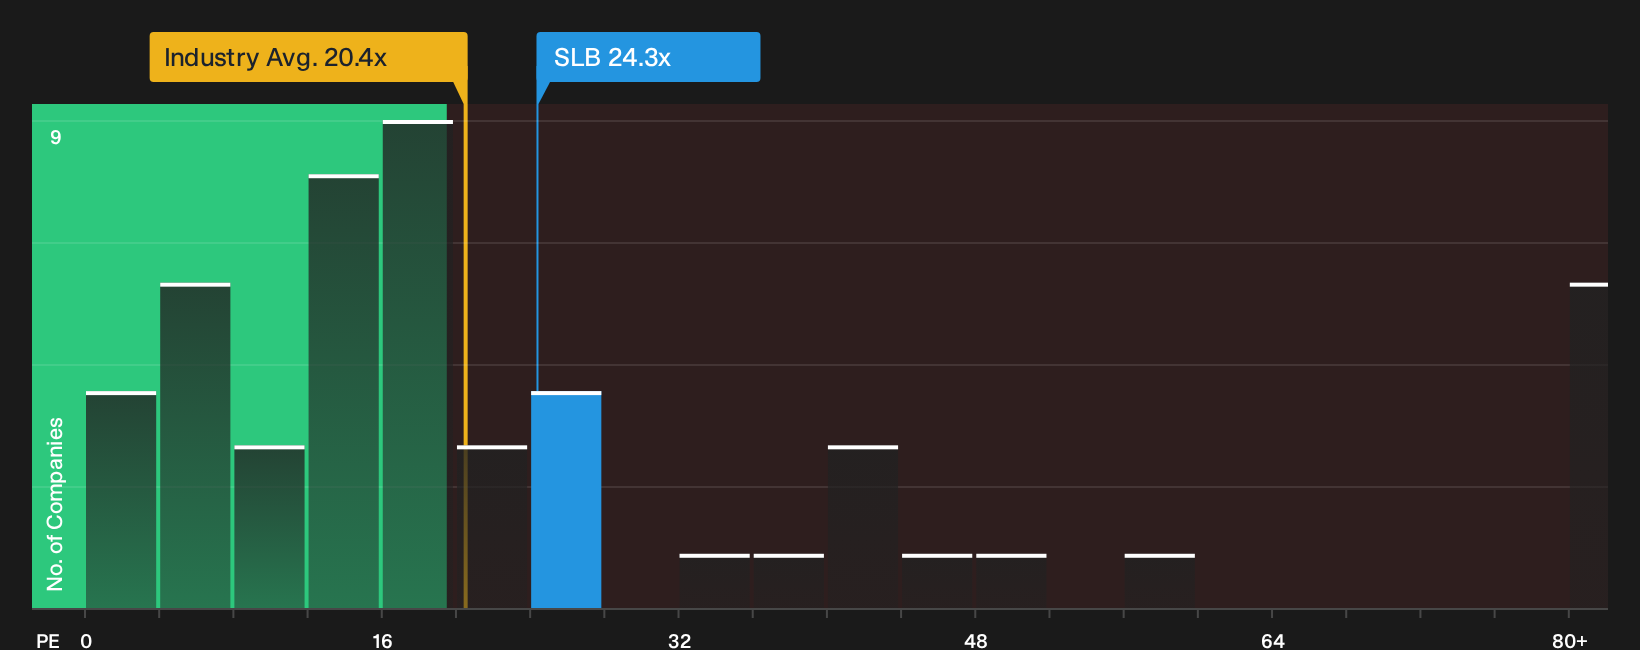
The first narrative paints SLB as undervalued, yet the current P/E of 24.3x sits above both the US Energy Services industry on 20.4x and the peer average at 23.8x, and even above a fair ratio of 23.3x. That gap points to valuation risk if expectations ease rather than improve. Where do you think the multiple drifts next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on SLB is clearly split, with investors weighing both fresh risks and emerging bright spots. Consider acting promptly, review the numbers yourself, and decide where you land after weighing the 3 key rewards and 2 important warning signs.
Looking for more ideas beyond SLB?
Do not stop your research with a single offshore contractor. Broader idea hunting gives you context, options, and a better sense of what value really looks like.
- Scan for potential mispriced opportunities by running a focused search built around 32 high quality undervalued stocks.
- Prioritize stability and capital protection by zeroing in on companies highlighted through the 30 resilient stocks with low risk scores.
- Hunt for early-stage potential with solid foundations by filtering through the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com