


Danaher has delivered solid multiyear gains for shareholders, and recent headlines around its life sciences and diagnostics units keep attention on the story. The open question is whether the current share price is properly grounded in the cash flows the business can generate.
- Over the past 3 years the stock has returned 15.0%, which puts real weight on whether that share price performance lines up with the stream of cash the company can produce.
- Fresh FDA clearances for Cepheid and Beckman Coulter products can influence expectations for diagnostic testing volumes and future cash flow timing, as new assays plug into existing instrument platforms rather than requiring heavy upfront capital spend.
- What if you looked at Danaher through its earnings instead? See what Danaher's 38.6x P/E says about the price.
The issue now is whether Danaher's current valuation is justified by the cash flows implied by its Discounted Cash Flow (DCF) intrinsic value estimate.
If you want to test the same cash flow question you are asking about Danaher across a wider set of life sciences and diagnostics players, start by scanning 30 resilient stocks with low risk scores.
Where Does Danaher Sit on Cash Flow?
The Discounted Cash Flow (DCF) model here looks at the cash Danaher can return to shareholders over time and discounts it back to today. On this view, the latest twelve month free cash flow sits at about $5.6b, with projections pointing to growing cash generation through 2030 rather than a shrinking profile. That supports the idea of a mature but still expanding cash engine behind the current share price of $235.31.
The gap between this cash flow outlook and the trading price is described as broadly in line, so the market is already crediting Danaher with a steady recovery in free cash flow. Cepheid's recent FDA clearance for its hemorrhagic fever panel reinforces that expectation because it adds another high value test to installed GeneXpert systems without demanding heavy new hardware spending. For readers who want to see the full set of cash flow assumptions that sit behind this alignment, the detailed DCF output is available in the valuation section. Find out what Danaher could be worth using our Discounted Cash Flow (DCF) estimate.
The Danaher Narrative: What Would Justify Today's Price?
Narratives pick up where that Danaher valuation question leaves off. They outline which potential paths for Danaher's growth, profitability and earnings would need to occur for the stock to be worth materially more or less than it is today, and they appear on Simply Wall St's Community page. Each narrative connects its number to a clear view on how growth, margins and risk could change over time, providing something concrete to revisit as new information becomes available.
One of the top narratives on Danaher: 9% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that has to go right is that biologics and bioprocessing capacity investment, AI-linked life sciences demand, and advanced diagnostics growth translate into sustained core revenue expansion…"
Discover why this Narrative puts Danaher at 9% undervalued.
One more Danaher check that sits alongside the valuation work
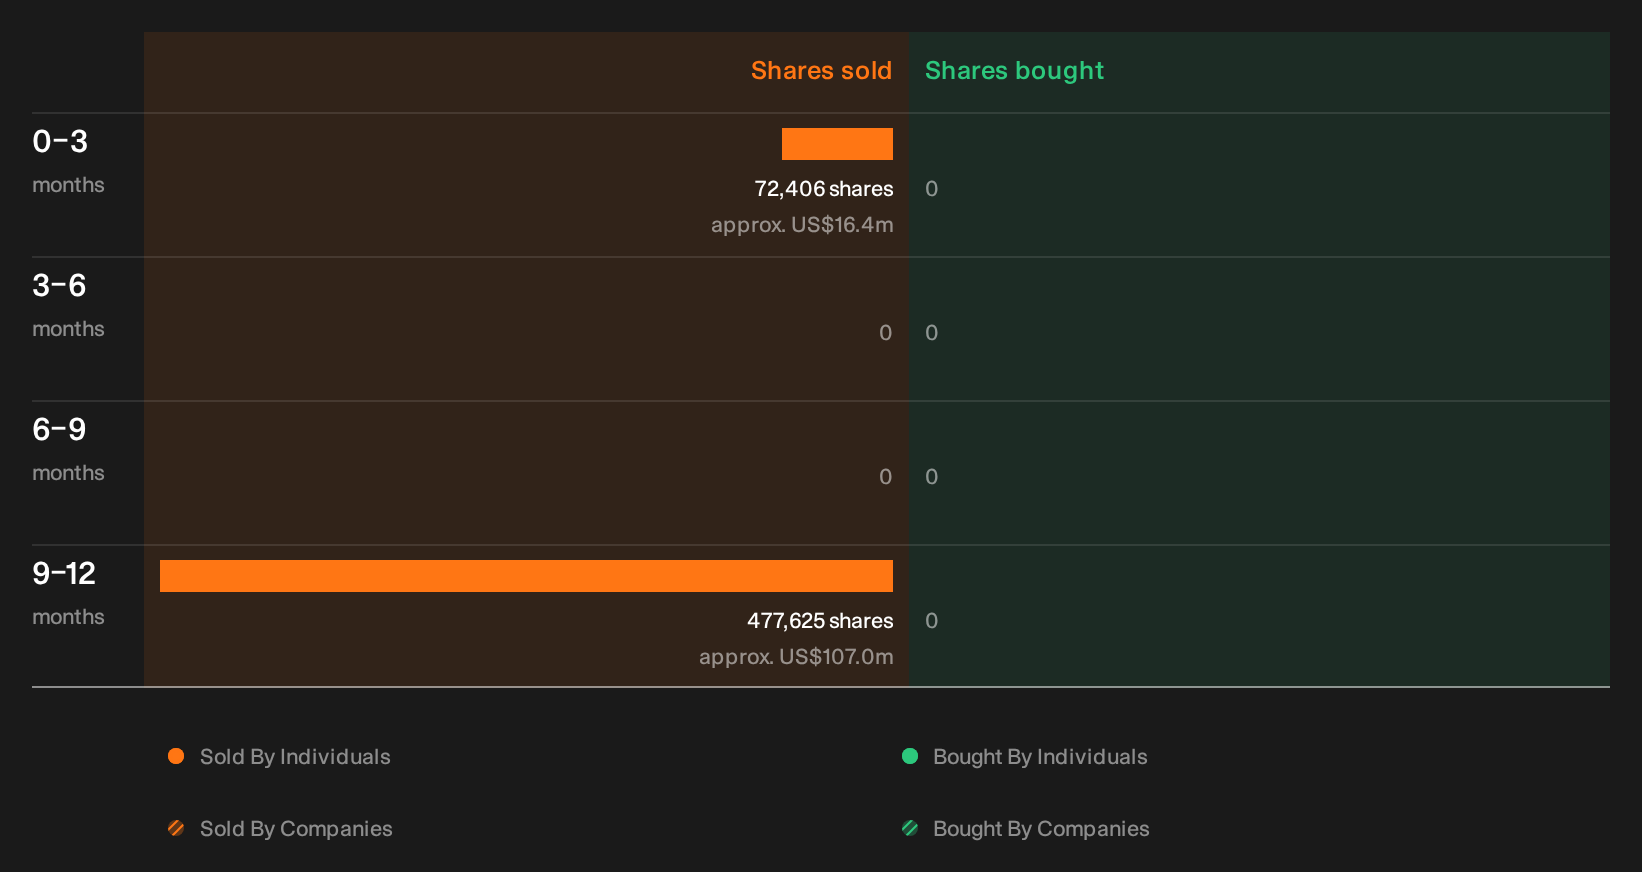
Price and cash flow tell only part of the Danaher story, because recent share sales by people inside the business also appear in our checks and the specific individuals, scale and possible read-through are waiting for you to review. See the recent insider selling flagged for Danaher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com