


HSBC Holdings (LSE:HSBA) just paired a 32% rise in third quarter profit before tax with plans for a new share buy-back of up to $1b, putting capital returns in clear focus for investors.
The share price of HSBC Holdings closed at £13.54, with a 7 day share price return of 3.56% offering a contrast to a 30 day decline of 5.37% and a 90 day drop of 11.38%, while the 1 year total shareholder return of 26.18% and a very large 5 year total shareholder return of around 3x indicate that long term holders have seen substantial gains. Recent price softness has come as the group juggles profit growth, the planned $1b buy-back, and fresh debt issuance and redemptions, which together shape how investors view both HSBC's growth potential and its risk profile.
Scan HSBC Holdings alongside a curated set of global banks with resilient balance sheets and consistent fundamentals using our list of solid balance sheet and fundamentals (9 results) to see how it stacks up on quality and stability.
Bulls point to HSBC Holdings pairing profit growth with a fresh buy-back, while bears focus on recent share price weakness and new debt. Which side do the current valuation numbers support?
Most Popular Narrative: 8% Undervalued
On the analyst consensus Narrative on Simply Wall St, HSBC Holdings is assessed with a fair value of about £14.74. This sits above the latest £13.54 close and frames the recent price slide as a discount rather than a premium.
Strong capital generation, a CET1 ratio around the 14% target range, a 40 to 50 basis point CET1 uplift expected from Basel 3.1 and resumed share buybacks together point to scope for continued capital returns alongside reinvestment. This can support per share earnings and distributions.
See why 176 investors see HSBC Holdings as 8% undervalued.
Result: Fair Value of £14.74 (UNDERVALUED)
Still, the bearish narrative gains traction if tougher deposit competition in Hong Kong and the UK squeezes net interest margins, or if planned business exits drag more heavily on revenue.
Find out about the key risks to this HSBC Holdings narrative.
Another View: What HSBC Holdings’ P/E Ratio Is Telling You
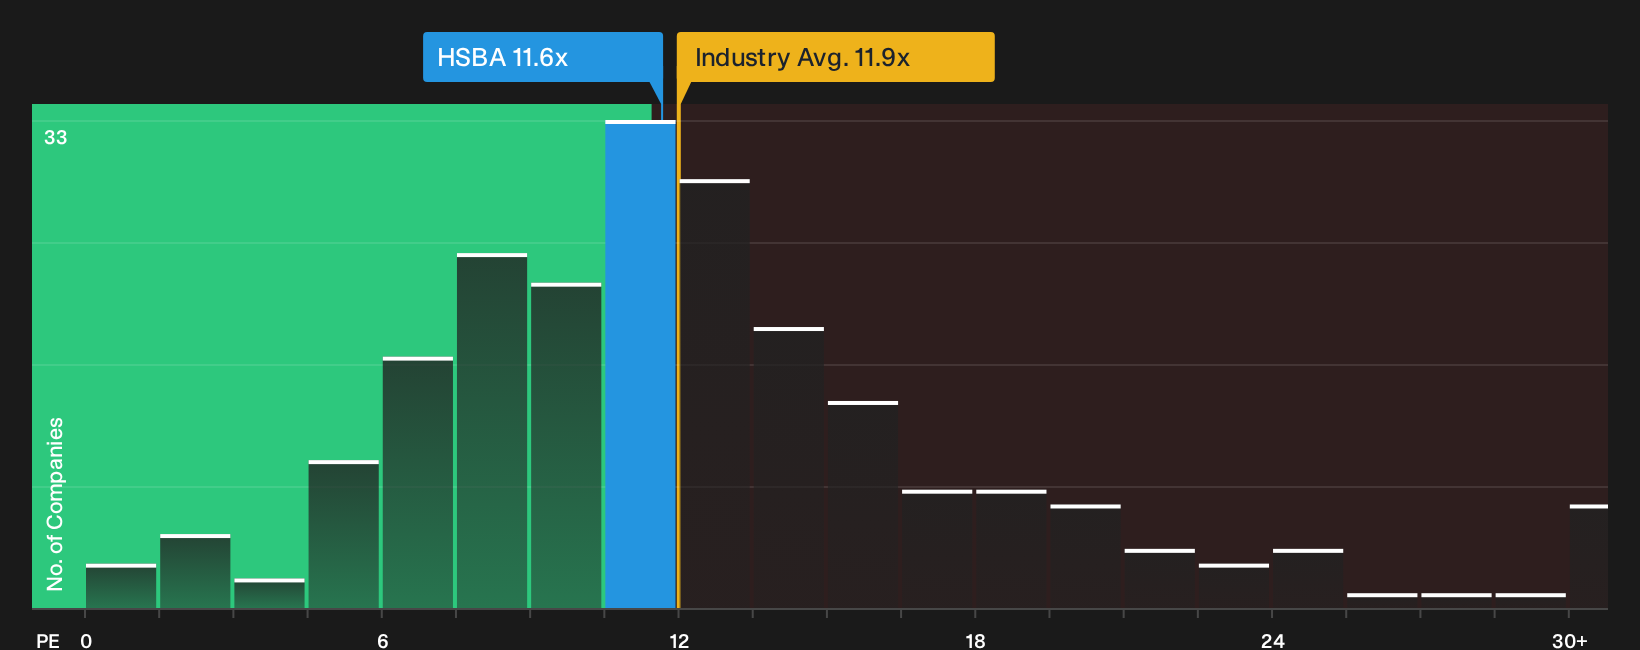
HSBC Holdings looks undervalued on that £14.74 fair value, yet the P/E of 11.6x paints a more cautious picture. It is richer than the peer average of 9.4x and also above its own fair ratio of 9x. That gap suggests less room for error if sentiment turns again.
Numbers can send mixed messages, and this P/E picture raises a simple question. Is the market already paying up for HSBC’s recent strength, or is this just the starting point before expectations reset toward that fair ratio? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on HSBC Holdings so far. If you want to move fast and reach your own judgement, start by weighing the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond HSBC Holdings?
If HSBC Holdings has your attention, do not stop here. Fresh opportunities often sit just outside your current watchlist, and skipping them can cost you.
- Target potential mispricings by scanning a curated 15 high quality undervalued stocks that blend solid fundamentals with room for sentiment to catch up.
- Strengthen your income stream by reviewing a focused 5 dividend fortresses that emphasise yield alongside balance sheet support.
- Dial down portfolio stress by filtering for a 5 resilient stocks with low risk scores where financial resilience and risk scores work in your favour.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com