


- IBM and Microsoft recently launched Imagine Enterprise, a joint platform that lets large organizations build, run, and govern AI agents tied to real-world processes, while IBM also reported extensive progress across its quantum hardware, software, and partner ecosystem.
- The combination of enterprise AI agents from Imagine Enterprise and IBM's Nighthawk quantum systems points to a tighter link between IBM's consulting, software, and advanced computing platforms in day to day client workloads.
- We will look at how IBM's existing hybrid cloud and AI investment narrative is reshaped by the Imagine Enterprise platform launch.
Compare how IBM's push into agentic AI and quantum stacks up against peers by scanning a curated list of 53 AI infrastructure stocks that are shaping the next wave of enterprise computing.
International Business Machines Investment Narrative Recap
To own International Business Machines, you need to believe the shift toward hybrid cloud, AI and now quantum can keep earnings and cash generation resilient while legacy infrastructure headwinds are managed. According to kapirey, an investor in the Simply Wall St Community, the appeal is a mix of recurring software, consulting demand and a reliable dividend of 2.72%.
The most immediate catalyst remains execution on enterprise AI and hybrid cloud deals that support mid single digit revenue growth and mid single digit earnings growth that are currently forecast. The biggest near term risk is heavy reliance on debt based funding alongside slower expected top line expansion than the wider US IT market, which limits room for missteps.
The IBM Quantum Nighthawk r3 announcement feels most relevant because it ties directly into the same “AI plus advanced compute” story as Imagine Enterprise. Nighthawk r2 is already supporting partners like E.ON, Algorithmiq and Q-CTRL on complex workloads, and r3 is designed to scale that architecture to 520 programmable qubits with 10,000 quantum operations.
For investors watching catalysts, this sets up a clearer operational bridge between IBM’s consulting and software franchises and its quantum hardware pipeline through the IBM Quantum Platform. Execution risk rises, since meaningful capital and talent are tied to quantum while overall revenue is still forecast to grow only about 4.2% a year, but successful deployments could deepen IBM’s role in high value workloads over time.
Using 6.0% annual revenue growth and a future profit margin of 18.0%, kapirey’s narrative for IBM arrives at a fair value estimate of US$256.08, tying that number to a mix of resilient cash generation, an expanding software weight in the mix, and ongoing hybrid cloud and AI repositioning.
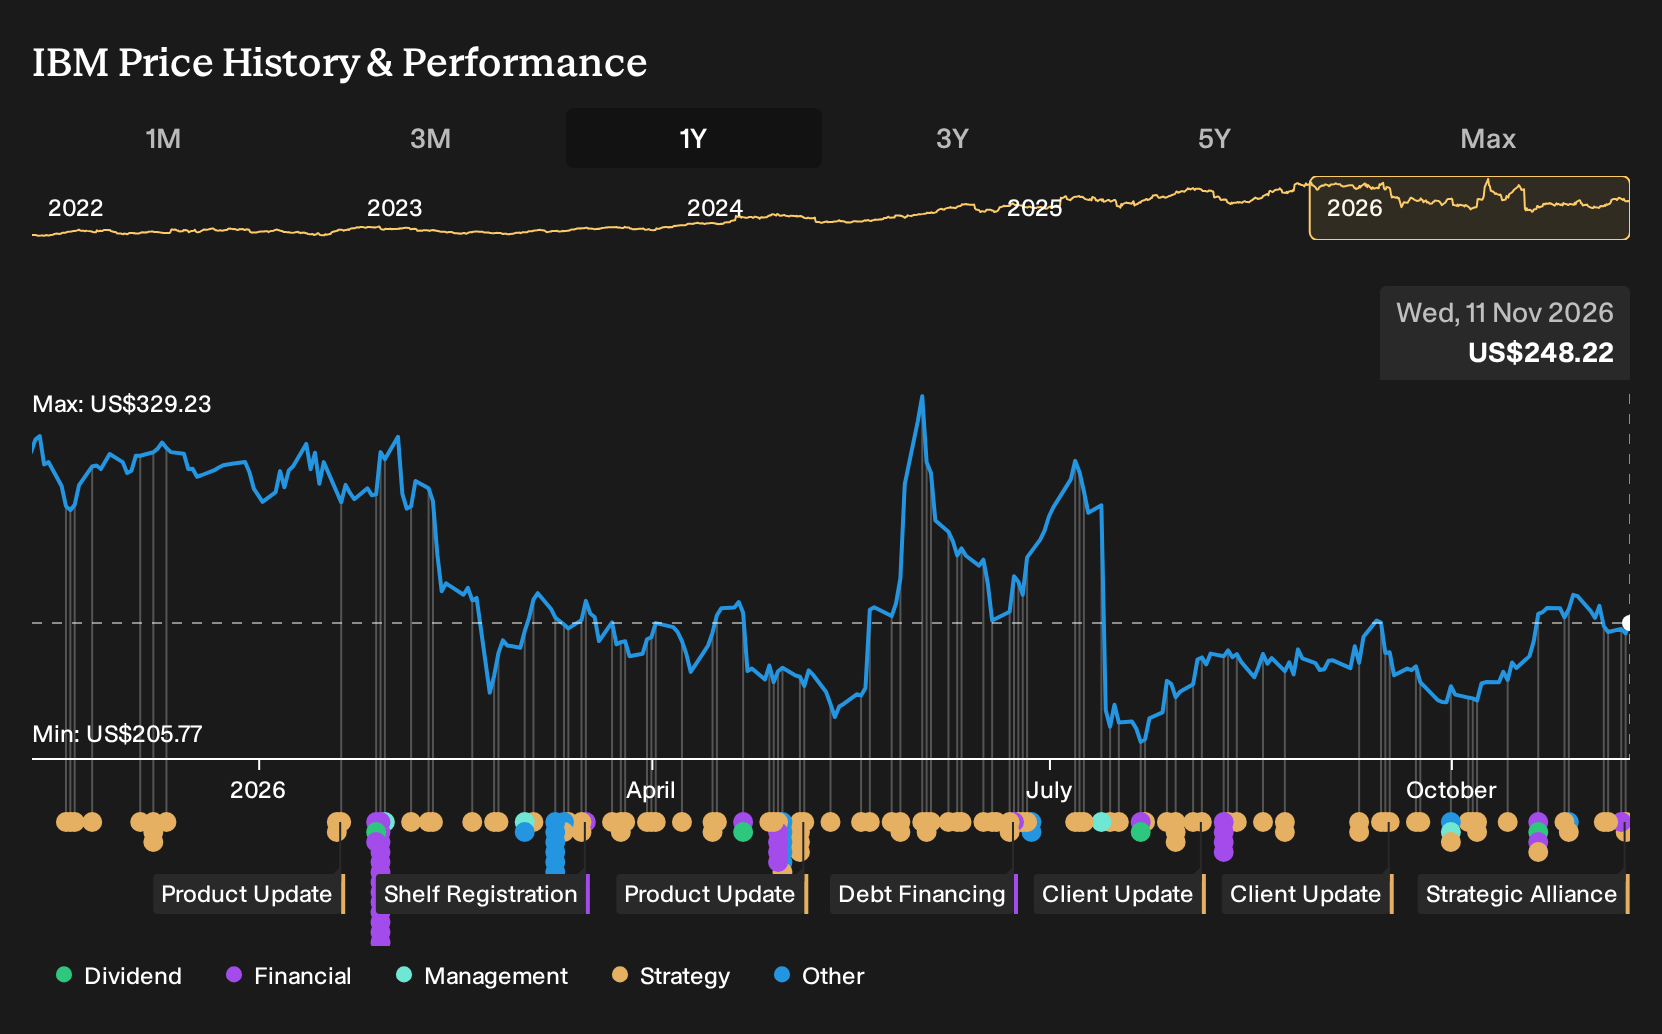
Uncover why International Business Machines' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Not every analyst shares kapirey’s confidence in IBM. The lowest forecasts before this Imagine Enterprise and Nighthawk r3 news assumed revenue would rise only about 3.6% a year and margins would compress toward 13.2%, with earnings slipping to roughly US$10.2b by 2029. That is a far more cautious story. Use it as a prompt to explore how sharply opinions can diverge, and how these fresh AI and quantum announcements might eventually shift those expectations.
Explore 7 other International Business Machines fair value estimates, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your International Business Machines research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for International Business Machines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate International Business Machines' overall financial health at a glance.
Looking for more investment ideas beyond International Business Machines?
If the IBM story has sharpened your thinking on AI, quantum and cash generation, use that same framework to scan for other businesses that fit your style. The Simply Wall St Screener can help you filter by balance sheet strength, income potential, or valuation quality in a structured way rather than relying on headlines.
- If resilience matters most to you, start with companies that score well on financial robustness and cash strength through the list of solid balance sheet and fundamentals (23 results).
- Income focused investors who care about durability as much as yield can review a hand picked pool of 6 dividend fortresses that aim to combine payout and balance sheet support.
- For those hunting for mispriced opportunities with quality fundamentals, scan a curated set of 32 high quality undervalued stocks that might fit a value oriented watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com