


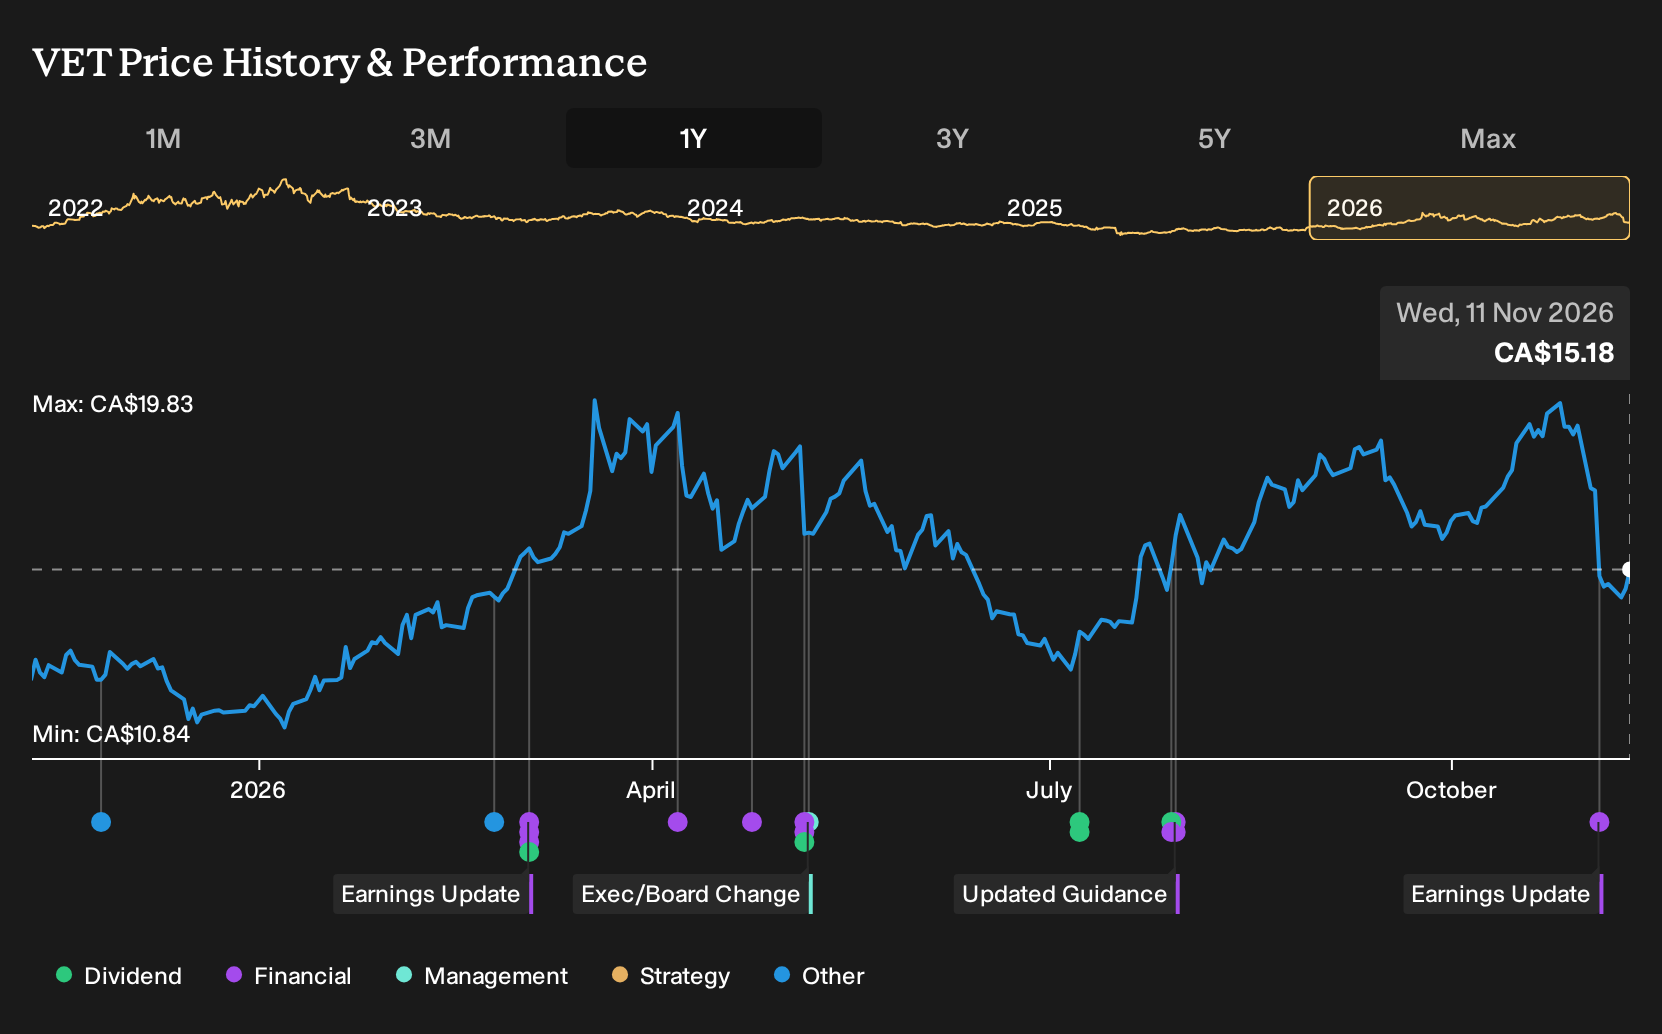
- Vermilion Energy reported third quarter 2026 revenue of C$565.82 million and a net loss of C$34.64 million, alongside ongoing share repurchases totaling 3.3 million shares across two buyback programs completed earlier in 2026.
- The mix of higher revenue with continued losses, combined with active buybacks and a raised dividend outlook for early 2027, highlights management attempting to balance capital returns with the pressure of weaker crude prices and operational costs.
- We will now look at how Vermilion Energy's latest loss making quarter could reshape the investment narrative around its gas focused repositioning.
Vermilion Energy Investment Narrative Recap
To own Vermilion Energy, you have to believe the company can turn its diversified oil and gas footprint and cost reductions into steady free cash flow despite choppy commodities. The analyst consensus Narrative on Simply Wall St relies on German deep gas, Montney projects and a leaner cost base to do that work. The latest third quarter loss of C$34.64 million keeps profitability in question but does not radically change that long term thesis.
The more immediate swing factor is cash generation versus debt and dividend commitments. Revenue of C$565.82 million for the quarter and C$1,572.55 million for the first nine months shows the asset base is productive. The near term risk is that weaker crude pricing or further downtime in places like Australia could strain funds from operations and limit how quickly Vermilion Energy can reduce leverage and support returns.
The clearest link between the recent result and the wider story is the active buyback. Vermilion Energy has completed repurchases of 2,800,000 shares for C$40.1 million under the 2025 program and another 500,000 shares for C$8.2 million under the 2026 plan, shrinking the share count while the business is still loss making. That is happening alongside a raised dividend outlook for early 2027 that was flagged with the third quarter update.
For investors, the question is whether ongoing buybacks and a higher future payout fit comfortably with the operational plan that underpins the analyst consensus Narrative on Simply Wall St, including European gas growth and Montney efficiency gains. If cash flow tracks that story, repurchases and dividends could amplify per share exposure to German deep gas and Montney volumes. If commodity prices or integration of the Westbrick assets disappoint, the combination of debt, dividends and buybacks could tighten financial flexibility and slow Vermilion Energy’s ability to respond to operational setbacks.
Vermilion Energy's current earnings are a loss of C$450.1 million, with analyst consensus pointing to earnings of C$446.7 million on revenue of C$2.3 billion by 2029. That outlook is based on forecast annual revenue growth of 7.9%, representing an earnings change of roughly C$897 million from earnings today to the 2029 estimate.
Uncover why Vermilion Energy's fair value indicates a 47% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
The sharpest contrast in the alternate view is around 2029 earnings power. While the consensus narrative circles C$446.7 million of earnings on C$2.3 billion of revenue, the lowest analysts were closer to C$352.9 million on C$2.5 billion. After this loss making quarter and active buybacks, that more cautious Vermilion Energy storyline may gain weight or be revised.
Explore 5 other Vermilion Energy fair value estimates, including one that suggests it could be worth just CA$19.00!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Vermilion Energy research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Vermilion Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vermilion Energy's overall financial health at a glance.
Looking for more Vermilion Energy sized investment ideas?
If Vermilion Energy has you thinking about position sizing, balance sheets and future cash generation, it can help to line it up against a broader watchlist built around clear rules.
- If capital protection sits high on your list, check out resilient companies with steadier risk profiles through the 9 resilient stocks with low risk scores.
- If you care most about quality businesses trading below what their fundamentals suggest, the 8 high quality undiscovered gems can surface lesser known opportunities that still have solid financial footing.
- If financial strength is your first filter before you even look at earnings estimates, start with the list of solid balance sheet and fundamentals (5 results) and build your next watchlist from there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com