


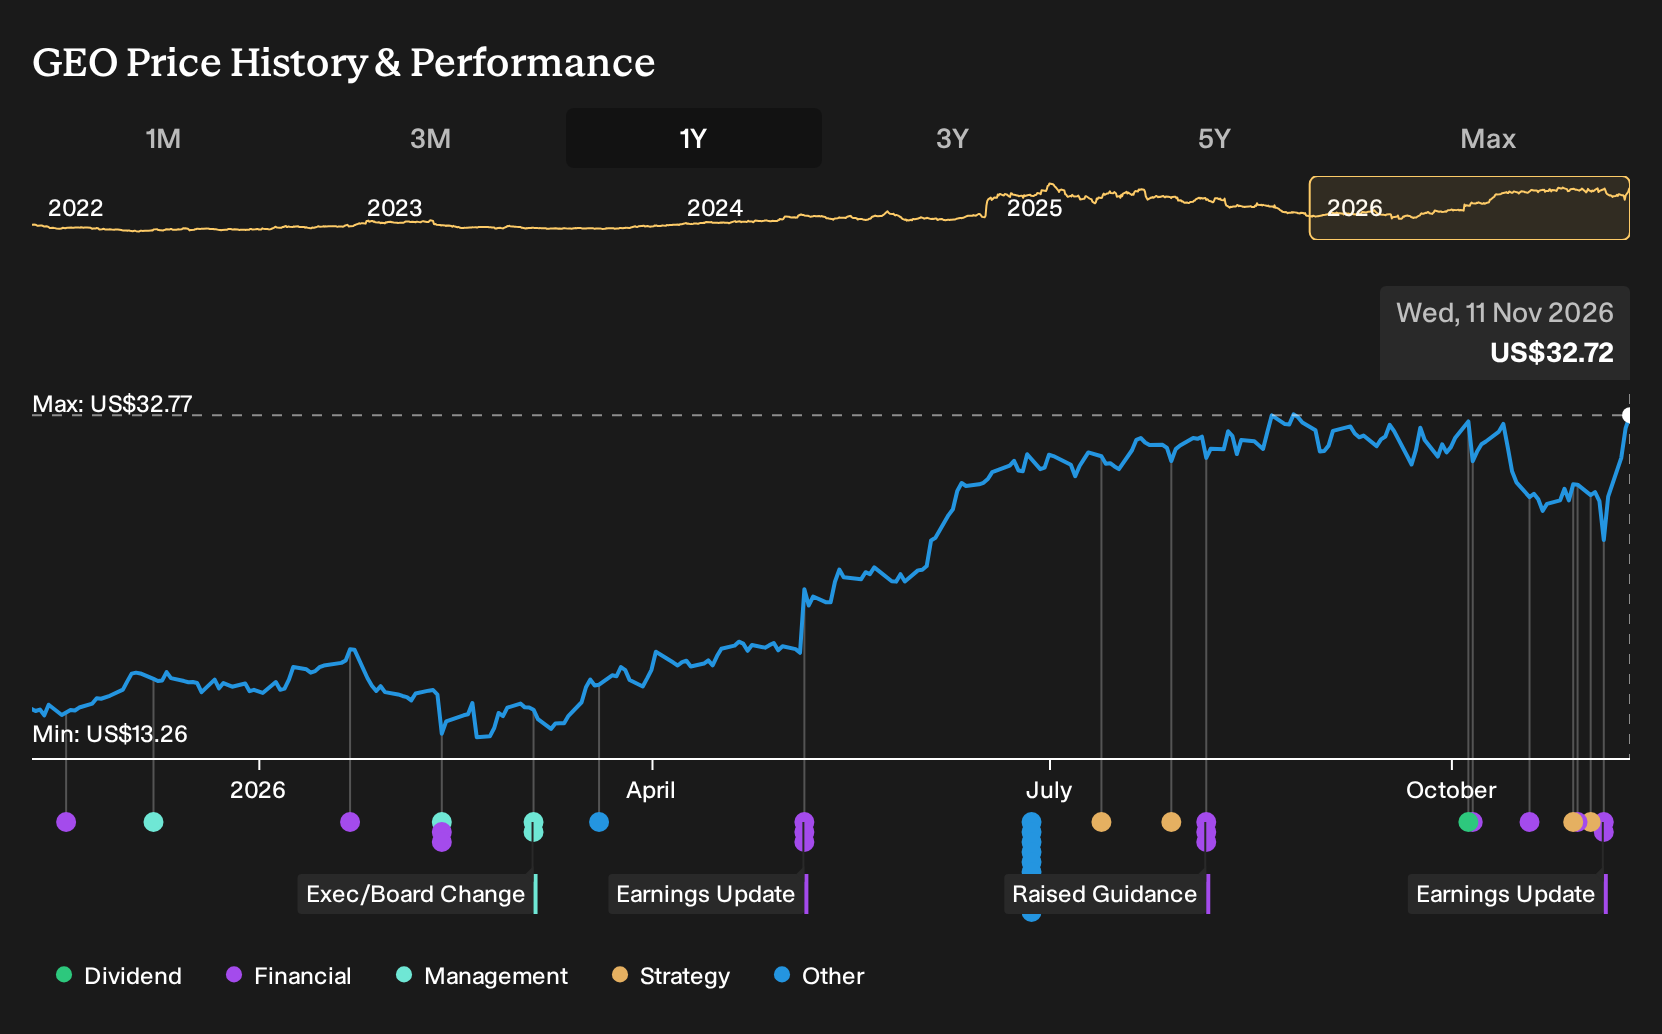
- GEO Group reported third quarter 2026 sales of US$761.06 million and net income of US$49.21 million, alongside new multi year ICE contracts in Texas and Washington that are expected to contribute roughly US$340 million in combined annual revenue once fully ramped.
- The earnings update, higher full year 2026 guidance that includes the planned Adelanto Complex sale, and an S&P credit upgrade to BB+ together highlight a business model that is leaning more on long duration federal revenue and a lighter balance sheet.
- The focus now turns to how GEO Group's upgraded credit rating could reshape the investment narrative readers are using to assess the company.
GEO Group Investment Narrative Recap
To own GEO Group, you need to believe the federal detention and monitoring machine keeps running at roughly today’s intensity and GEO continues to win and operate long term contracts efficiently. The recent quarter showed higher sales but lower net income compared with last year, so the near term story is more about contract visibility than earnings momentum.
Right now the key catalyst is how quickly new ICE facilities and service lines move from signed agreements to stable utilization and cash generation. The biggest risk remains policy and funding shifts that reduce detention demand or disrupt programs like ISAP and transportation, which would leave GEO’s expanded footprint underused.
The fresh 10 year ICE contracts for the Big Spring Complex in Texas and the Northwest ICE Processing Center in Washington are the clearest link between the latest news and GEO Group’s valuation premium. Together they are expected to generate about US$340 million in annual revenue once fully ramped, which directly supports the analyst consensus Narrative on Simply Wall St that GEO’s earnings mix is tilting toward longer duration federal work.
This type of long contract life can help shorten the gap between guidance and actual cash flow, which matters when GEO trades on a P/E above Commercial Services peers. The flip side is concentration risk. A heavier reliance on ICE and related federal appropriations means any contract renegotiation, utilization shortfall or budget decision could have a quicker impact on both earnings and how investors view that premium.
GEO Group's current analyst narrative points to revenues of US$4.0b and earnings of US$498.3 million by 2029. These projections are built on an assumed 11.4% yearly revenue growth rate and an earnings increase of about US$331.5 million from today’s US$166.8 million level.
Uncover how GEO Group's fair value indicates a 25% potential upside to its current price, which could narrow quickly if GEO Group continues to tighten its federal contract profile.
Exploring Other Perspectives
One alternate GEO Group narrative leans heavily on margin expansion rather than contract wins. The most optimistic analysts were already penciling in US$4.0b of revenue and about US$643.4 million of earnings by 2029 before this quarter’s guidance shift. You can treat this earnings upgrade as a fresh test of those more aggressive assumptions and explore how your own view lines up.
Explore 3 other GEO Group fair value estimates, including one that suggests potential upside of as much as 221% from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GEO Group research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking for more investment ideas beyond GEO Group?
Once you have formed a view on GEO Group, it can help to compare that thesis with other companies that share similar qualities or offer a very different risk profile. The Simply Wall St Screener is a quick way to pressure test your thinking across a broader watchlist.
- For investors who care most about balance sheet strength and durable fundamentals, start with the list of solid balance sheet and fundamentals (23 results) and see which businesses clear a higher bar for financial resilience.
- If you want potential mispricings where quality and value intersect, measure your GEO Group thesis against the 32 high quality undervalued stocks and see how other candidates stack up on valuation and fundamentals.
- When the goal is stability first, keep an eye on the 30 resilient stocks with low risk scores to find companies with lower risk scores that might complement a position in GEO Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com