


Recent weakness across the semiconductor sector has heightened investor concerns about the sustainability of AI-related capital expenditure, moderating demand expectations in the smartphone and PC markets, and broader macroeconomic uncertainty. These factors have triggered widespread selling across chip stocks. However, AMD’s (AMD) prospects remain solid, and the company is witnessing acceleration in growth.
AMD is benefiting from accelerating data center demand, expanded partnerships with hyperscale cloud providers, and the ramp-up of latest-generation processors and AI accelerators. These growth drivers position AMD to sustain solid revenue and earnings momentum. Although its valuation remains elevated, the premium appears justified given the acceleration in its top line and solid EPS growth prospects.
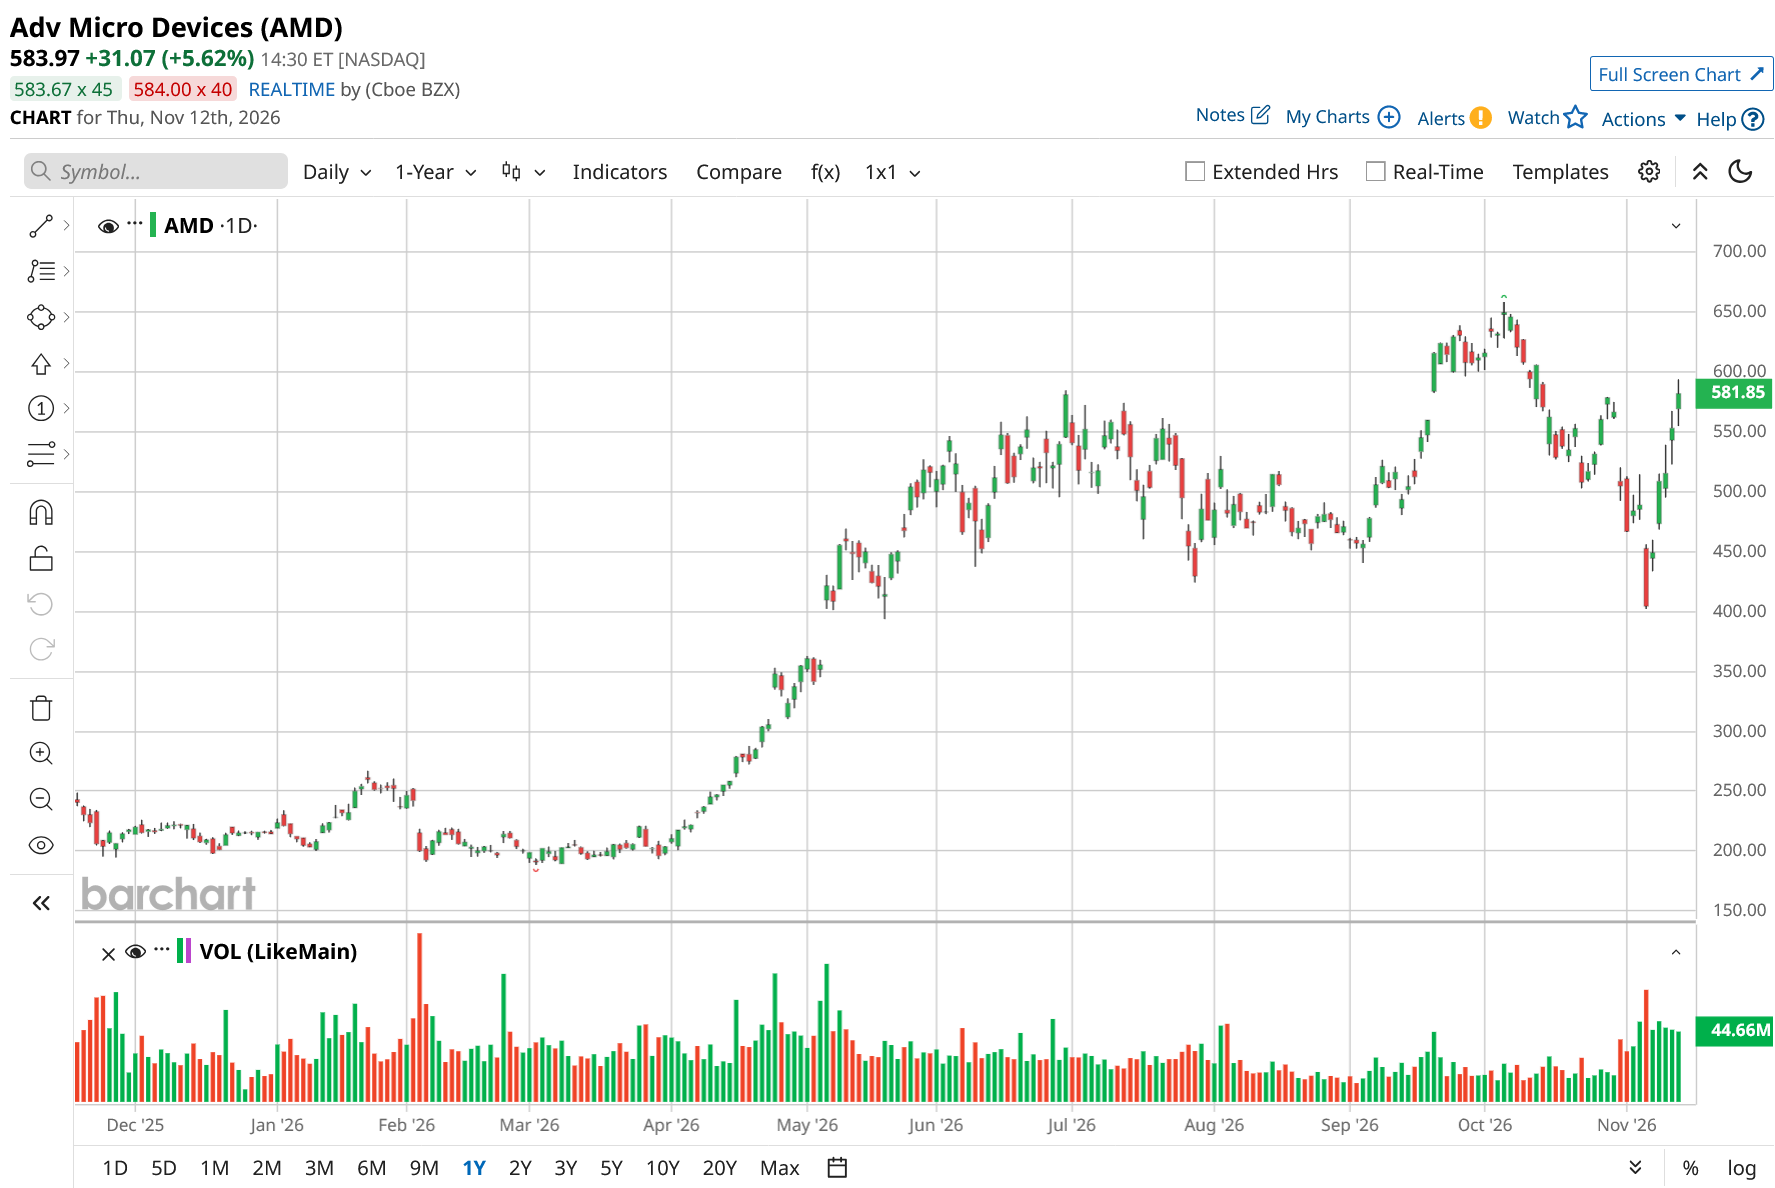
Growth to Accelerate
AMD delivered solid quarterly performance, reflecting accelerating demand for its next-generation data center technologies. Revenue rose 45% year-over-year (YoY) to $13.4 billion, supported by record sales of EPYC server processors and Instinct accelerators, along with continued growth in the Embedded segment. Earnings per share grew even faster, with its bottom line jumping 74% to $2.09.
The Data Center segment generated $8.5 billion in revenue, up 97% YoY. Demand for EPYC processors remained robust across hyperscalers and enterprise customers, especially as agentic AI and inference workloads increase the need for computing infrastructure.
AMD is also strengthening its position in the AI space through acquisitions. Its acquisitions of Taalas and World Labs aim to improve its capabilities in low-latency AI processing and spatial intelligence. These investments will broaden AMD’s technological portfolio and improve its competitive positioning in the evolving AI ecosystem.
Looking ahead, management expects growth to accelerate further as production of its Helios platform, MI450 accelerators, and next-generation EPYC processors increases. AMD has also raised its expectations for 2027, now projecting that server revenue will double YoY, with AI-related data center revenue growing at a solid pace.
Customer interest in the upcoming MI500 series is also encouraging, with several leading AI research organizations exploring large-scale deployments. This suggests that demand for advanced computing infrastructure could remain strong over the coming years.
Meanwhile, the Embedded segment continued its recovery, with revenue increasing 29% YoY to $1.1 billion. Growth was supported by demand from aerospace and defence, automotive, communications, and industrial markets. AMD also expects to secure more than $18 billion in design wins during 2026, marking another potential record year.
From a profitability perspective, continued expansion in the server CPU business will drive its earnings. As demand for EPYC processors increases and the addressable market for server CPUs expands, AMD has an opportunity to strengthen its revenue mix and sustain earnings growth.
Overall, an accelerating growth rate supported by strong customer demand, an expanding product portfolio, and improving revenue visibility provide a positive growth outlook for AMD.
AMD’s Growth Story Is Far From Over
Despite concerns over the sustainability of AI infrastructure expenditure weighing on broader investor sentiment, AMD remains well-positioned to sustain robust growth. Strong data center demand, accelerating adoption of AI accelerators, and expanding partnerships with hyperscalers provide a solid foundation for sustained revenue and earnings growth. Moreover, the expected ramp-up of its Helios platform, MI450 accelerators, and next-generation EPYC processors could further strengthen its competitive position in the AI infrastructure market.
Although AMD stock commands a premium valuation, its strong earnings growth outlook provides fundamental support for the elevated multiple. Its forward price-to-earnings (P/E) ratio of 73.4x appears reasonable given analysts’ expectations of a 131.5% increase in EPS to $16.04 in fiscal 2027.
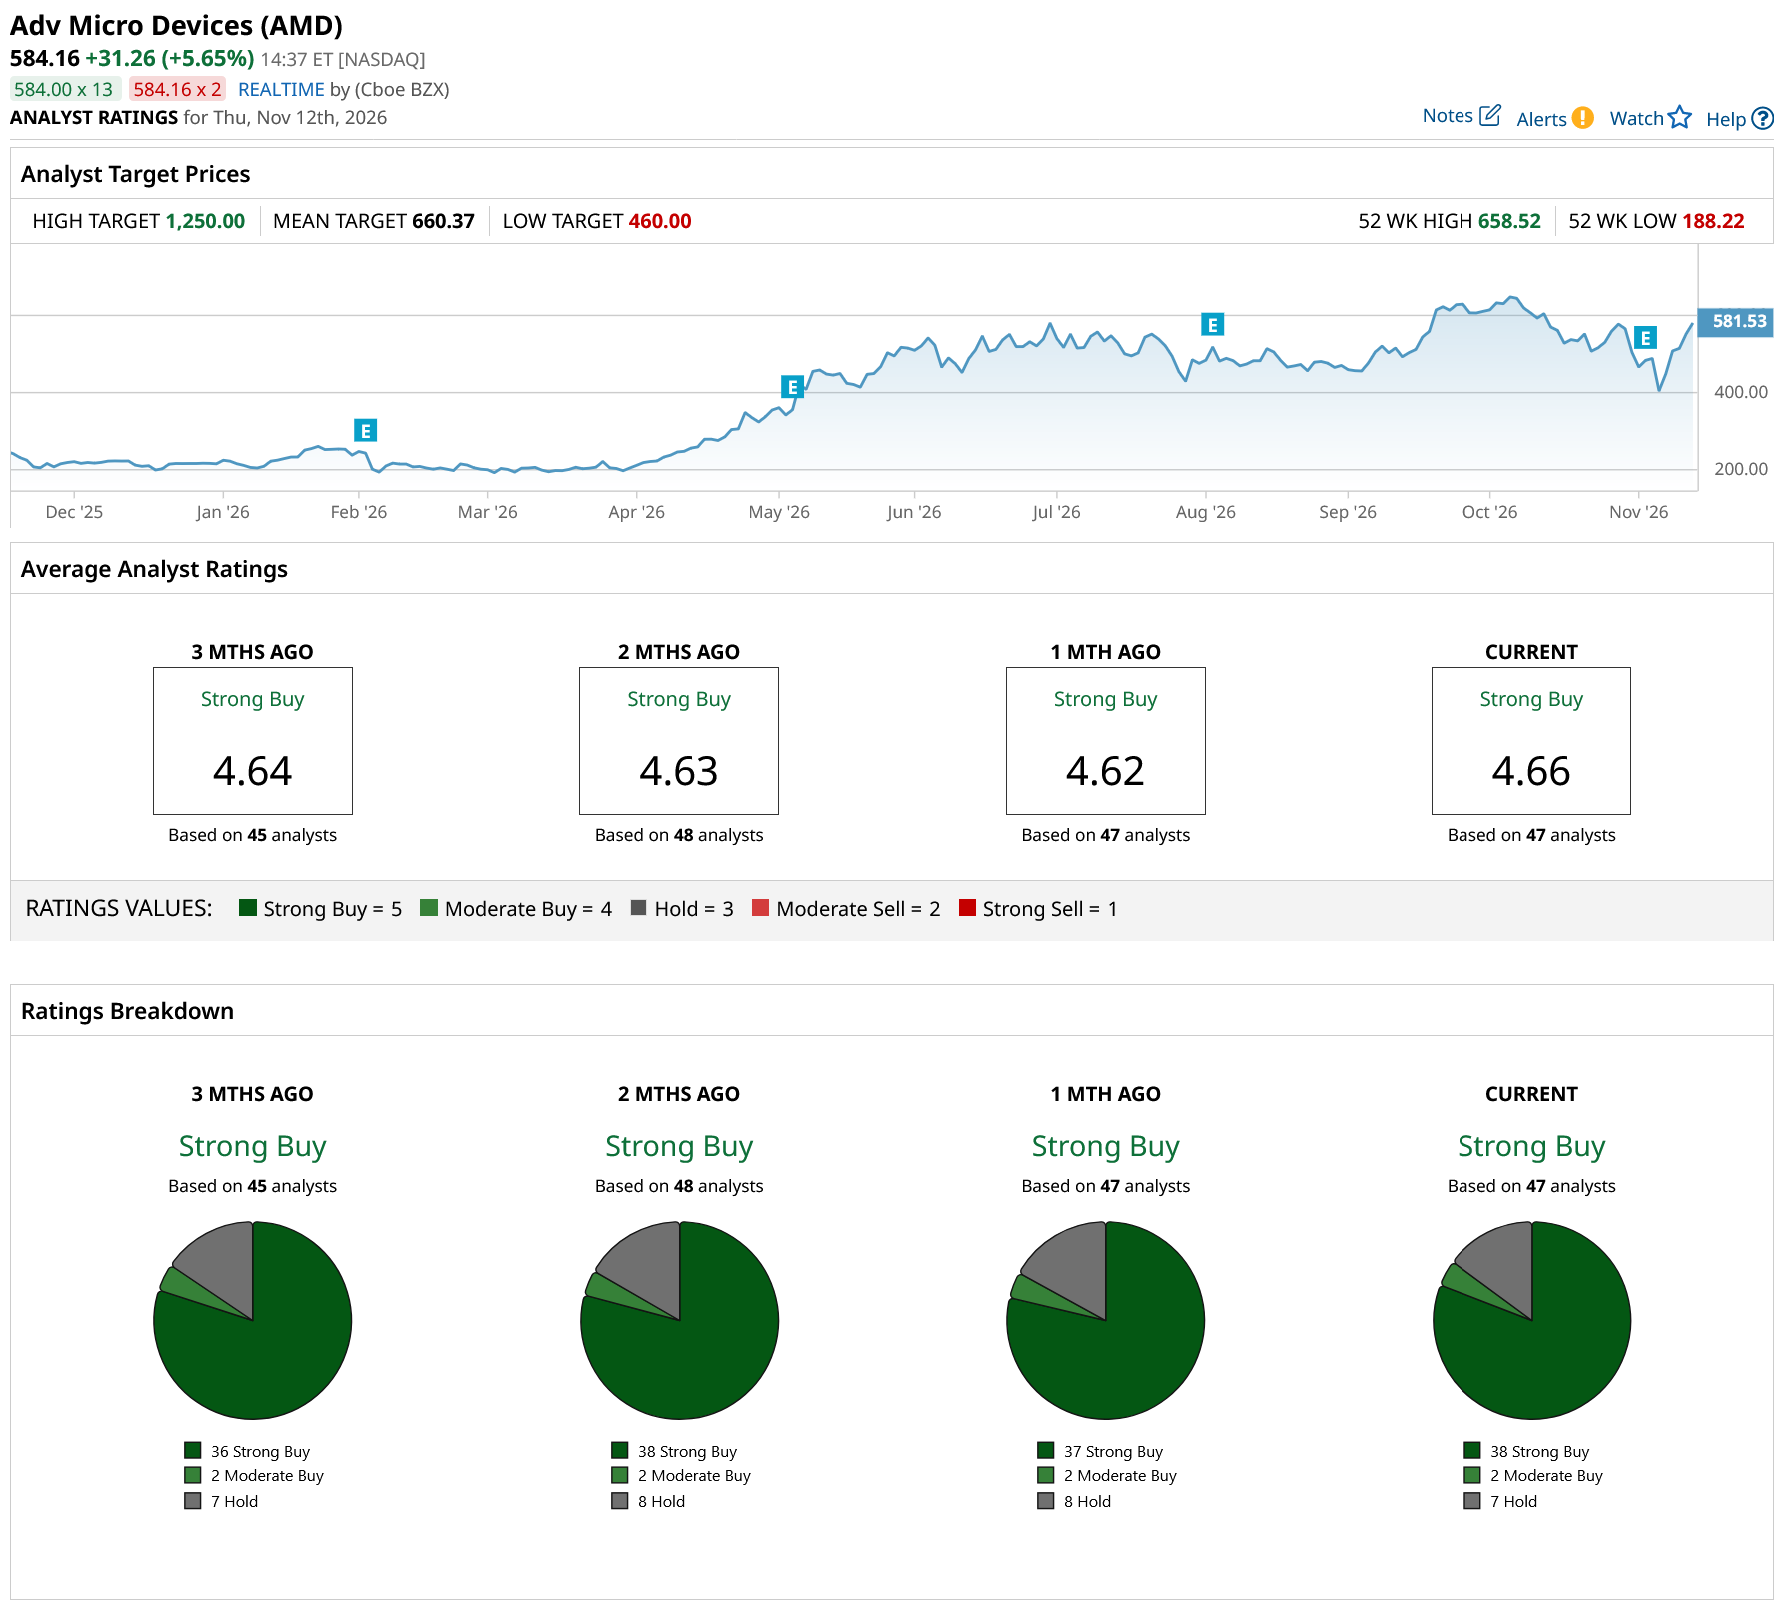
Wall Street’s outlook on AMD also remains constructive post its Q3 earnings announcement. AMD stock currently carries a “Strong Buy” consensus rating, indicating continued analyst confidence in its growth prospects and competitive position in the AI semiconductor market.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.