


Nebius (NBIS) shares tumbled on Thursday even after the artificial intelligence (AI) infrastructure company reported a nearly sixfold increase in Q3 revenue to $981 million.
Investors were nonetheless left disappointed as management offered cautious near-term guidance and signaled delays tied to data center capacity expansion.
Following the post-earnings decline, NBIS stock is trading at less than half its price in mid-August.
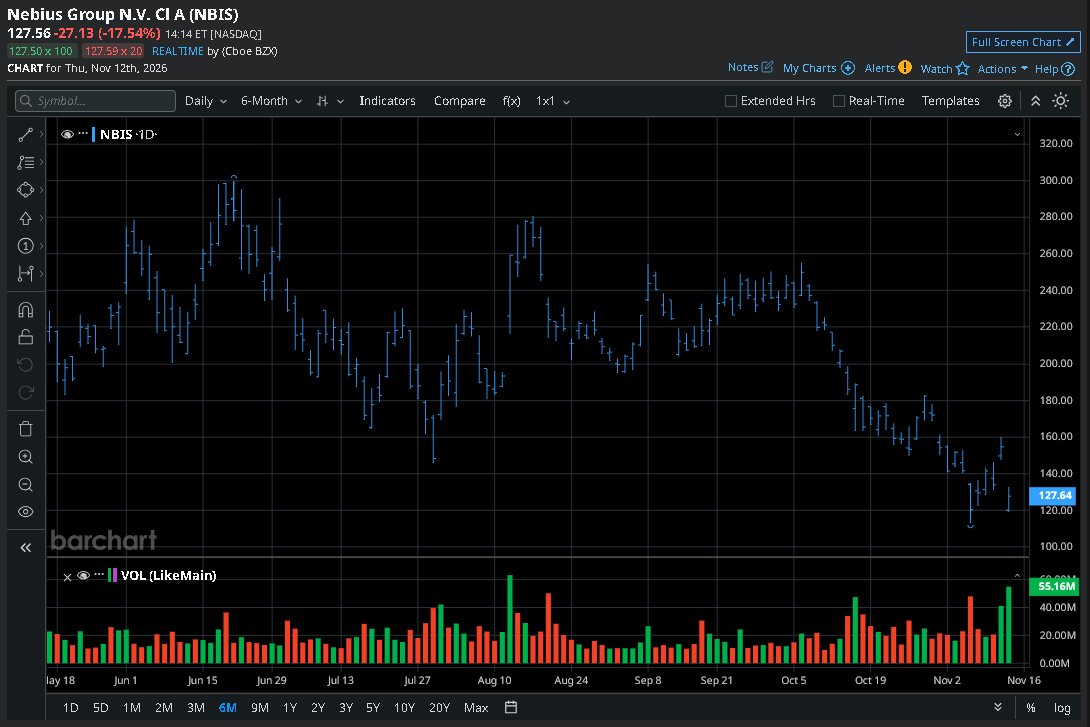
What Triggered a Selloff in Nebius Stock Today?
Nebius shares’ selloff was not centered on third-quarter results themselves.
By most conventional measures, the numbers were strong. NBIS beat revenue estimates, narrowed its loss, and highlighted continued momentum across its artificial intelligence cloud platform.
But investors zeroed in on what comes next.
Management said some third-party data center capacity expected to be available by the end of this year has been pushed into the first half of 2027.
As a result, Nebius now expects full-year 2026 revenue to land near the lower end of its previously stated $3.0 billion to $3.4 billion range.
Meanwhile, the company also raised outlook for capital expenditures, projecting about $27 billion in spending for 2026 and at least $40 billion for the coming year as it raced to build infrastructure.
Should You Load Up on NBIS Shares Today?
The key takeaway from Nebius’s latest earnings release is that customer demand remains intact.
Management repeatedly emphasized strong demand for AI computing capacity; existing contracts tied to delayed facilities remain in place rather than being canceled.
Simply put, revenue is being deferred, not necessarily lost.
The company said customer prepayments and financing arrangements linked to investment-grade clients should cover a large portion of planned expansion spending, providing additional visibility into future projects.
These reassurances make NBIS stock attractive to buy on the post-earnings dip today.
Wall Street Remains Bullish on Nebius Group
Wall Street analysts also remain convinced that Nebius shares are undervalued at their current price and are poised for meaningful gains in 2027.
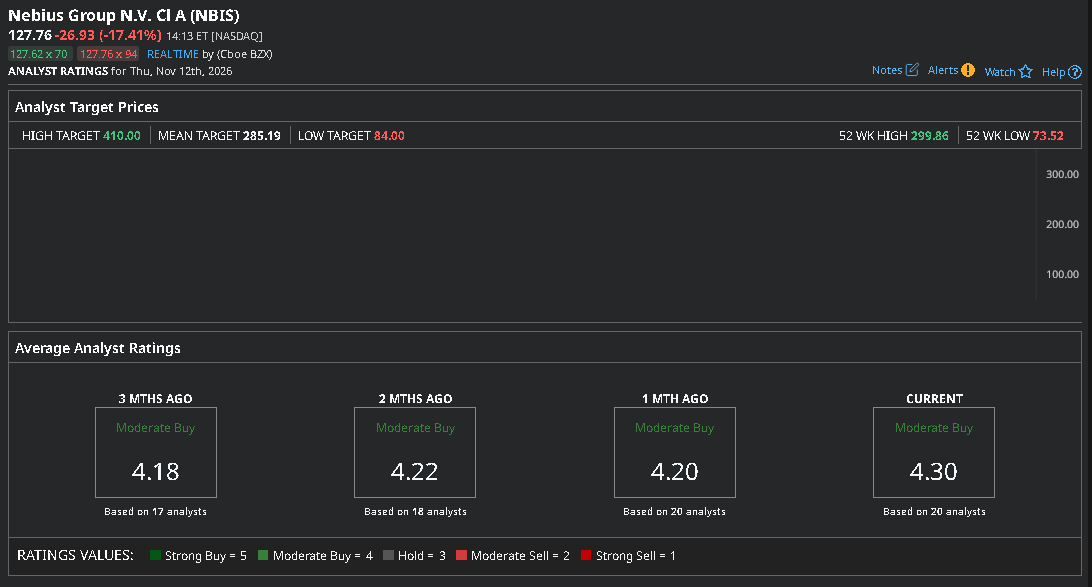
According to Barchart, the consensus rating on the AI infrastructure firm sits at “Moderate Buy” as of this writing, with the mean price target of about $285 indicating potential upside of more than 100% from here.
On the date of publication, Wajeeh Khan did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.