


HOCHTIEF (XTRA:HOT) has put fresh numbers on the table, with third quarter 2026 results showing higher sales, net income and earnings per share compared with the same period a year earlier.
At a share price of €383.0, HOCHTIEF has seen a 1-day share price return of 2.41% and a 7-day share price return of 10.57%. The latest earnings release is likely a key driver. However, the 90-day share price return is down 13.54%, while the 1-year total shareholder return of 36.58% and very large 5-year total shareholder return suggest momentum over the longer haul is still strong.
Scan other construction and infrastructure players showing similar earnings momentum by reviewing our hand picked list of solid balance sheet and fundamentals (199 results) alongside HOCHTIEF's latest results.
Bulls see HOCHTIEF's stronger earnings and long term returns as support for a higher price. Bears point to the recent 90 day slide. Which side does the valuation actually support?
Most Popular Narrative: 22% Undervalued
HOCHTIEF's analyst consensus Narrative on Simply Wall St points to a fair value of €487.93 versus the last close at €383. That gap reflects analysts' combined views on future projects, margins and risk, filtered through a 7.67% discount rate.
Surging demand for AI driven digital infrastructure, with HOCHTIEF reporting around €16.8 billion of data center orders in 2025 and data centers already at 21% of the backlog, provides multi year visibility that could support higher revenue and operational earnings if margins in this segment remain firm.
See why 23 investors see HOCHTIEF as 22% undervalued.
Result: Fair Value of €487.93 (UNDERVALUED)
Still, two things can quickly weaken the HOCHTIEF story: a prolonged drag from CIMIC's slower profit contribution and any disappointment from the Abertis stake.
Find out about the key risks to this HOCHTIEF narrative.
Another View: What Multiples Say About HOCHTIEF
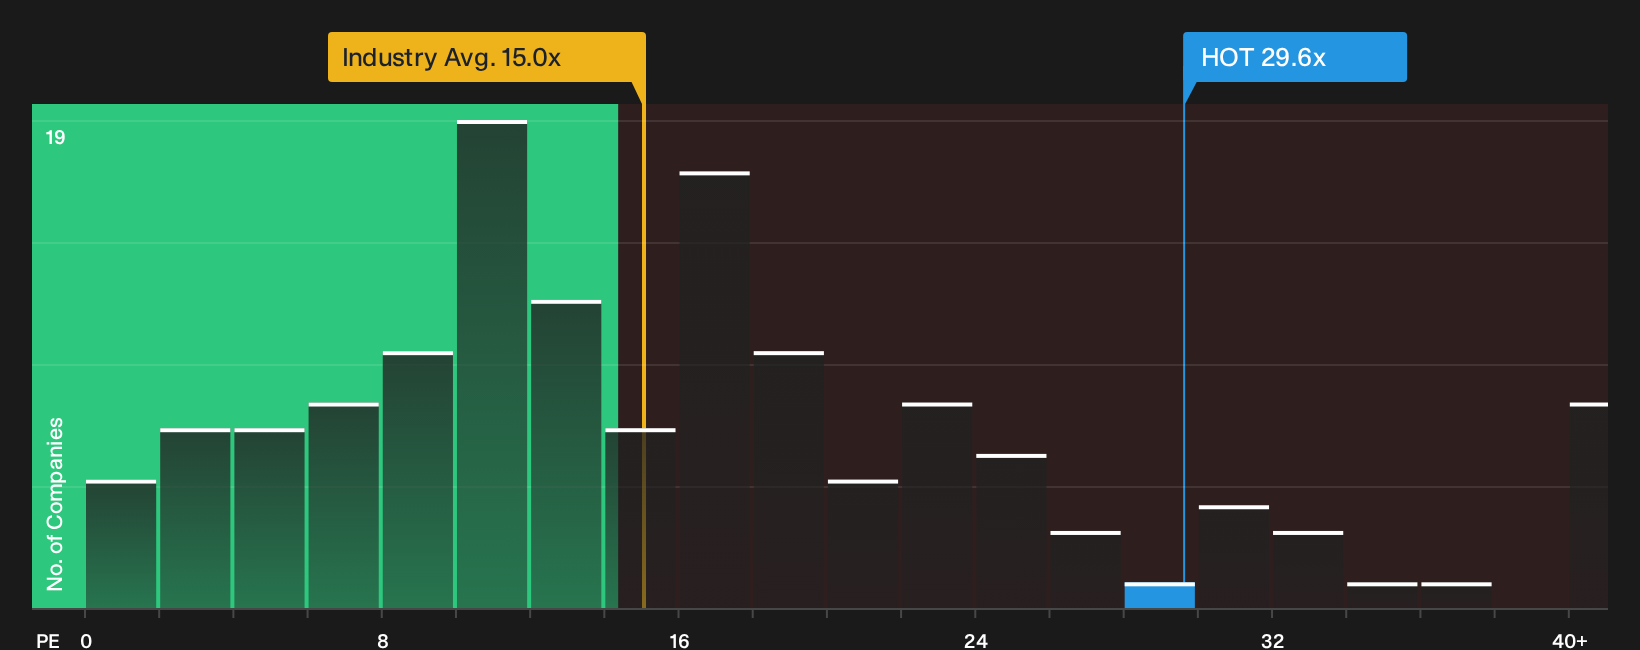
The cash flow work suggests HOCHTIEF is trading about 15% below an estimate of future cash flow value at €450.45. The P/E picture is less generous. The shares trade on 29.6x earnings compared with a European Construction average of 15x and a fair ratio of 28.6x, which points to less room for error if growth or margins fall short.
For a closer look at how that P/E gap could close over time, and what it might mean for valuation risk, see the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Plenty of optimism runs through this HOCHTIEF story, yet the risk section is not empty. Move quickly, review the underlying forecasts and stress test the assumptions for yourself, then weigh the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond HOCHTIEF?
If HOCHTIEF has sharpened your focus, do not stop here. Use this momentum to hunt for other quality opportunities that fit your style and risk tolerance.
- Target stronger balance sheets and steadier fundamentals by scanning a curated list of solid balance sheet and fundamentals (199 results) that highlights companies built to handle tougher conditions.
- Pursue better value by reviewing the 194 high quality undervalued stocks that screens for quality businesses trading below their assessed worth.
- Build a resilient income stream by checking out the 216 dividend fortresses focused on higher yielding stocks with an emphasis on staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com