


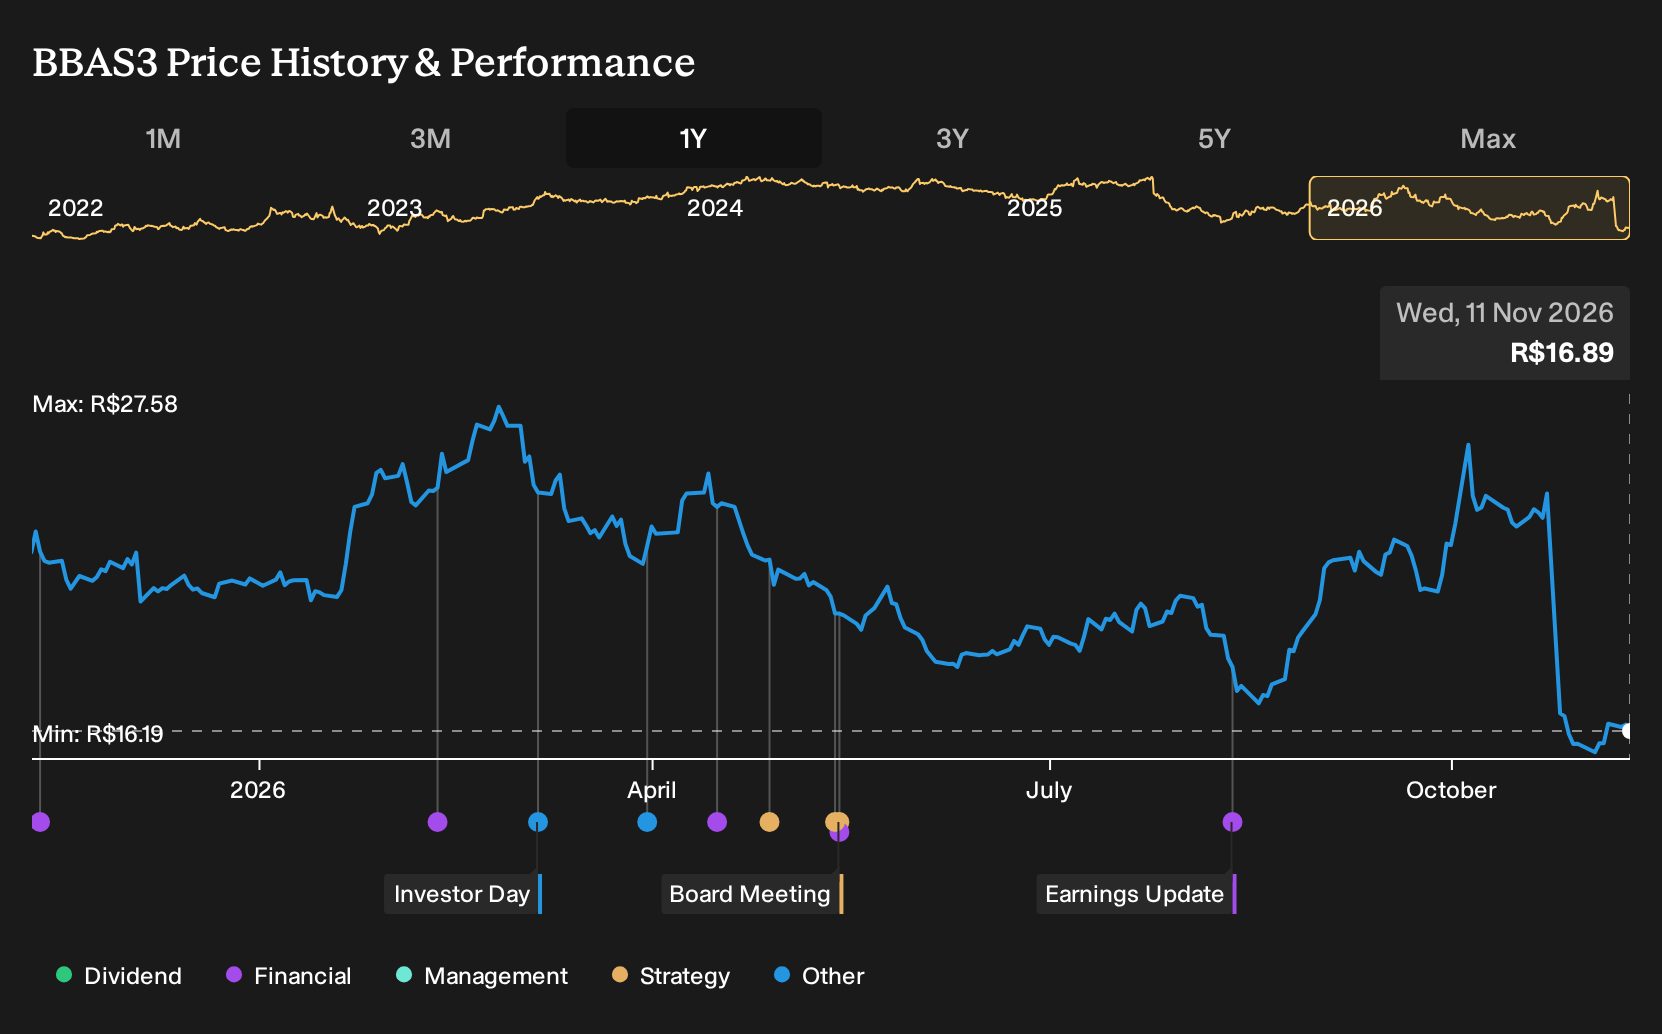
When Banco do Brasil reported Q2 2026 results showing revenue broadly flat but net income lower than a year earlier, it sharpened a question many holders had been living with for months. Holding Banco do Brasil over the past year would have meant a 23.7% loss, including dividends. If you had bought at the start of that period, how much of that setback was already hinted at in the earlier bullish and bearish arguments about digital execution, regulation, and agribusiness risk?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Banco do Brasil has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Banco do Brasil
The shares cost R$23.53 at the start of the period, and investors looking at Banco do Brasil had two very different stories on the table. Each one rested on specific assumptions about digital banking, regulation, and agribusiness risk.
The bullish narrative saw a Fair Value of R$39, or 66% above the start price. It leaned on rapid digital acceleration, including a plan to digitize 100% of strategic areas by 2025, as well as the use of an omnichannel CRM to lift conversion rates and improve cost to income.
The bearish view put Fair Value at R$20, or 15% below the start price. That case focused on digital disruption and fintech rivalry as a threat to competitiveness, along with ongoing political influence and exposure to volatile agribusiness lending that could keep credit losses and provisions elevated.
What The Banco do Brasil Results Put To The Test
The clearest new fact was Q2 2026 performance. Banco do Brasil reported revenue of R$21,915.374 million versus R$21,873.133 million a year earlier, while net income slipped to R$2,397.643 million and net margin went from 12.7% to 10.9%. That mix of steady top line and weaker profitability cut both ways for the bullish and bearish cases.
The hinge assumption here was earnings quality under digital and agribusiness risk. For a different bank, you would test that by tracking net margin and provision trends against any promised efficiency or risk control improvements.
What Today's Banco do Brasil Price Already Assumes
Banco do Brasil now trades at R$16.89, after a 23.7% loss over the past year from R$23.53. The analyst consensus Narrative on Simply Wall St views Fair Value as sitting above that level, based on how digital tools and the wider group might support earnings while credit costs stay elevated.
For that higher figure to make sense, a buyer today would need to believe agribusiness and retail credit clean up can keep cost of risk within the bank's intended range.
"The ongoing digital acceleration at Banco do Brasil, including the rapid build out of over 2,300 analytical AI models and widespread use of employee built AI agents that have freed up around 1.5 million working hours and lifted loan renegotiation conversion multiples, continues to support the view that cost efficiency and credit recovery productivity can feed into net margins and earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 32% below our estimate - operates a sizable ore portfolio converting long-life deposits into producing assets.
- Company 2 - 37% below our estimate - applies automation to freight workflows and regulatory tasks that support transaction throughput.
- Company 3 - 20% below our estimate - promotes targeted bone graft materials as surgeons reduce length of systemic therapies.
That is three of the list. See all 199 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com