


National Bank Holdings (NBHC) is back in focus after its latest quarterly update, which paired headline revenue growth of 21.8% with misses on net interest income and EPS, coinciding with a 4.4% share price drop.
That earnings miss landed on a share price that has already been under pressure, with a 90 day share price return down 14.53% and the current price sitting at $37.18, even though the 1 year total shareholder return is still positive at 3.48% and the 3 year total shareholder return is 20.05%. This points to fading short term momentum against a stronger longer run record.
Position your portfolio for the same kind of pressure National Bank Holdings is facing by scanning a curated 30 resilient stocks with low risk scores that focuses on balance sheet strength when sentiment turns.After that pullback, National Bank Holdings now trades at a clear gap to both analyst targets and intrinsic value estimates. So where does fair value actually sit in that spread, and how wide is it in practice?
Most Popular Narrative: 19% Undervalued
On the numbers, the analyst consensus Narrative on Simply Wall St pegs National Bank Holdings at a fair value of $46, which sits meaningfully above the last close at $37.18 and frames the recent pullback as a valuation gap that relies heavily on execution.
The main thing that has to go right is that National Bank Holdings converts its loan growth, Vista integration, and digital investments like 2UniFi into durable, high quality earnings without eroding its conservative credit profile or near 4% net interest margin.
See why 4 investors see National Bank Holdings as 19% undervalued.
Result: Fair Value of $46 (UNDERVALUED)
Still, concentration in sectors like trucking and commercial real estate, along with early stage 2UniFi economics, could both challenge the National Bank Holdings upside case.
Find out about the key risks to this National Bank Holdings narrative.
Another View: What National Bank Holdings' P/E Is Telling You
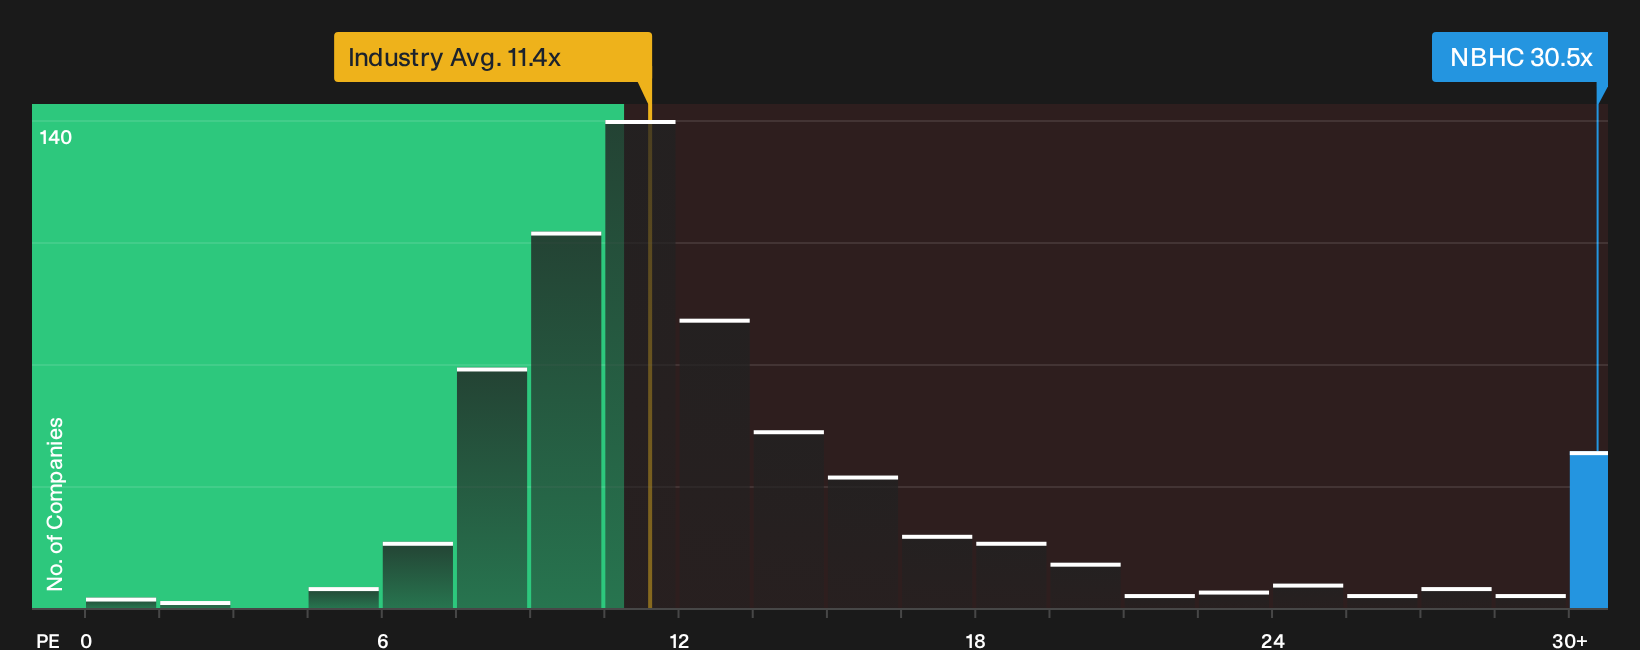
The cash flow work points to National Bank Holdings looking cheap against a $59.97 future cash flow value; however, the P/E picture pushes in the opposite direction. The share price implies a 30.5x multiple, which is well above the fair ratio of 23.6x, the US Banks sector at 11.3x, and peer averages at 12.3x. That kind of premium can limit upside if earnings forecasts fall short, so the key question is which signal you trust more: the discounted cash flow or the richer earnings multiple.
See what the numbers say about this price in more detail in the valuation breakdown, starting with our preferred earnings ratio view. Then compare it to other banks using the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around National Bank Holdings can either feel like noise or a timely prompt to check the underlying data yourself and act on evidence. To weigh both the upside potential and the issues investors are worried about, start with the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond National Bank Holdings?
If National Bank Holdings raised as many questions as answers for you, widen the lens and pressure test your portfolio ideas with a few focused stock shortlists.
- Target resilient balance sheets by running your filters through a curated list of solid balance sheet and fundamentals (23 results) that keeps financial strength front and center when conditions tighten.
- Sharpen your value hunt and compare National Bank Holdings with a broader pool of potential bargains using a focused 32 high quality undervalued stocks built around quality and price.
- Zero in on companies flying under most investors' radar and let a dedicated 20 high quality undiscovered gems surface lesser known ideas with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com