


Ondas has been through a volatile stretch, with a very large gain over the past three years and a weak run so far in 2026. This puts a spotlight on whether its current share price is supported by its earnings profile. With the stock last closing at US$5.73 and fresh headlines around new contracts and acquisitions, the question for you is how much of that story is already embedded in the valuation.
- Ondas has delivered a roughly 7x total return over the past three years, so any judgment on the stock now hinges on whether the underlying earnings can justify that kind of long run-up.
- Recent contract wins in aerial defense and expansion moves in aircraft and drone production may support expectations for stronger future profitability, but they can also raise questions about execution risk and the timing of any earnings improvement.
- The analysts covering Ondas have run their own numbers. See what analysts think Ondas's shares could be worth.
The issue now is whether the earnings that Ondas generates today, and what investors expect it to earn in future, make the current share price look sensible when lined up against its Fair Ratio benchmark.
If you want to test the same earnings question you are asking of Ondas across a wider set of drone and defense related plays, compare it to 86 robotics and automation stocks.
Has Ondas Run Too Far on Earnings?
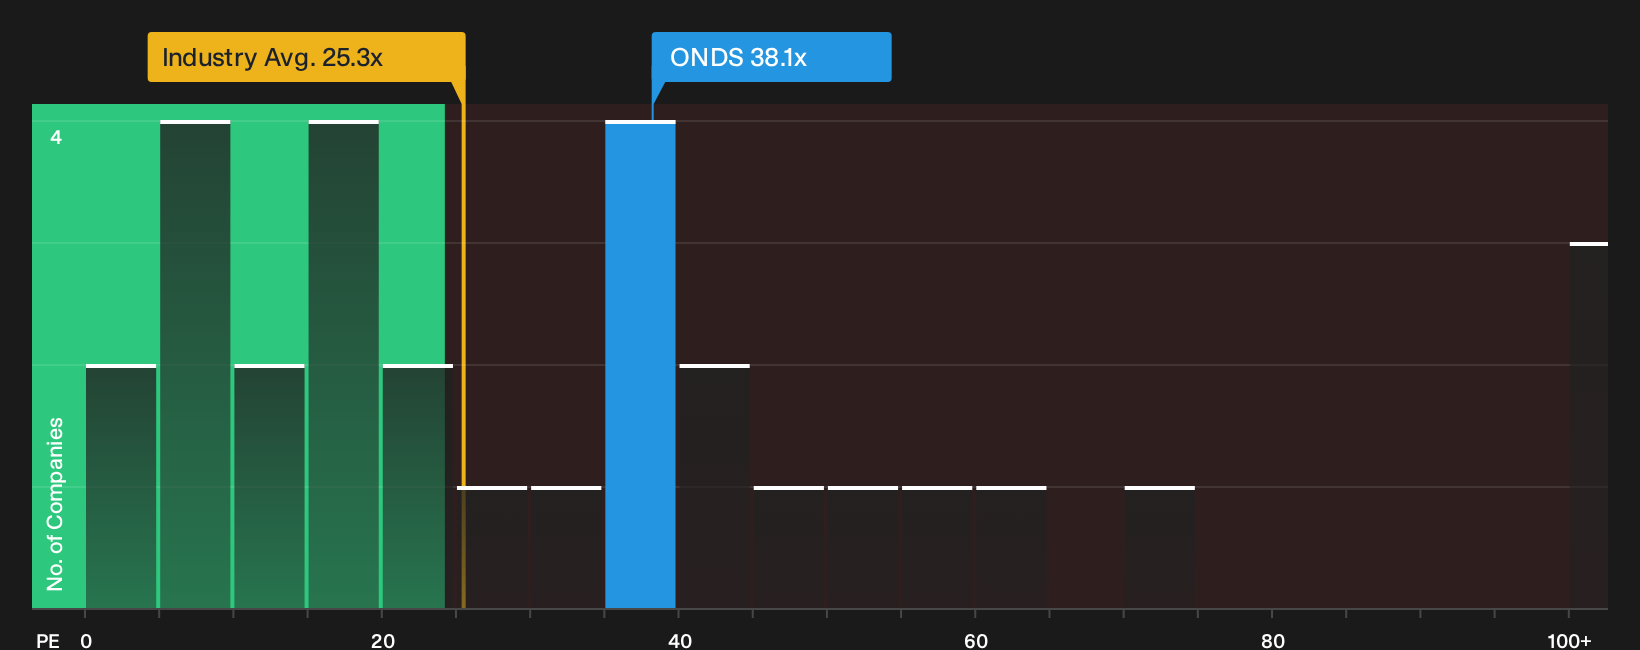
The P/E ratio is a useful yardstick for Ondas because investors are focused on what its current earnings already imply about the share price. At about 38.1x earnings, the stock trades above the wider communications sector, where the average is around 25.3x. This suggests that the market is willing to pay a premium for each dollar of profit.
Compared with more direct peers, where the average multiple is roughly 45.2x, Ondas changes hands at a lower earnings multiple, so the stock does not look stretched against that narrower group in pure P/E terms. Despite the share price reaction to record Q3 2026 revenue and the raised outlook, the current P/E still sits above the level suggested by a Fair Ratio that blends the company’s growth runway, profitability profile, size and risk, so the valuation screens as overvalued on this framework. Explore the numbers behind Ondas's P/E valuation.
The Ondas Narrative: What Would Justify Today's Price?
Ondas' valuation puzzle only really comes into focus once you spell out the future that would need to unfold for today’s P/E premium to look cheap or expensive. Simply Wall St Narratives on the Community page do that by turning the broad debate about growth, margins and earnings into specific paths that could leave the stock worth materially more or less than it is now. Rather than a single multiple or model output, each one lays out the assumptions behind its view of fair value so you can compare those expectations with the actual numbers as results come through.
One of the top community narratives on Ondas: 71% undervalued
According to AgentWilson, an investor in the Simply Wall St Community, Ondas is being reshaped by a layered defense model that targets the surveillance gap.
"By architecting what they call 'Layered ISR,' Ondas is effectively merging two worlds that used to operate in isolation, creating a vertical stack of security…"
Discover why this Narrative puts Ondas at 71% undervalued.
One more Ondas check that sits beyond the share price math
Price ratios tell you what the market thinks of Ondas today, but the people actually steering the business and how their rewards line up with your outcomes is a separate check that can shift the whole picture. See who runs Ondas and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com