


Rubrik (RBRK) is in focus after rolling out new cyber recovery tools across AWS, Azure DevOps, GitHub, and Google Cloud, tying threat detection, blast radius analysis, and surgical recovery into its broader data security platform.
These product rollouts come after a strong run in Rubrik’s shares this year. The year-to-date share price return is 44.77%, and the 1-year total shareholder return is 47.75%, indicating building momentum despite a recent 7-day share price decline of 8.18%.
Compare Rubrik’s momentum in cyber recovery with other security-focused software stocks by scanning the 30 resilient stocks with low risk scores, which couples resilient balance sheets with controlled risk profiles.
After a sharp run this year and a recent pullback, Rubrik now poses a simple question for investors: step in after the drop or wait for a cleaner entry once the valuation work is done next?
Most Popular Narrative: 3% Overvalued
Rubrik closed at $109.26, while the most followed narrative on Simply Wall St places fair value at $105.75, implying a small premium that keeps short term expectations front and center.
According to DanielOliveira, an investor in the Simply Wall St Community who wrote the narrative, this quarter is mainly about how tightly Rubrik set its guidance relative to its own subscription run rate and what that means for the usual upside surprise.
That is what changed. The last three guides sat at 92.4%, 94.2% and 96.7% of the starting run rate, while actual subscription revenue excluding material rights came in at 103.0%, 100.1% and 102.9%. Rubrik beat the guide midpoint by 5.8% to 10.4% in each of the last four quarters because the guides left that gap. This one leaves about two points.
See why 1 investors see Rubrik as 3% overvalued.
DanielOliveira applies an 8.54% discount rate to Rubrik and argues that because this view is a specific call on the upcoming quarter rather than a long term story, the fair value of $105.75 and the share price sitting slightly above that level leave limited implied upside in this framework for now.
Result: Fair Value of $105.75 (OVERVALUED)
Still, Rubrik’s narrative could be challenged if the tighter revenue guide leaves little room for upside or if net new subscription ARR tracks below recent expectations.
Find out about the key risks to this Rubrik narrative.
Another View: Rubrik Through A Cash Flow Lens
The first narrative pegs Rubrik at $105.75, slightly below the current $109.26 share price and tags the stock as 3% overvalued in that framework. A different lens tells a very different story.
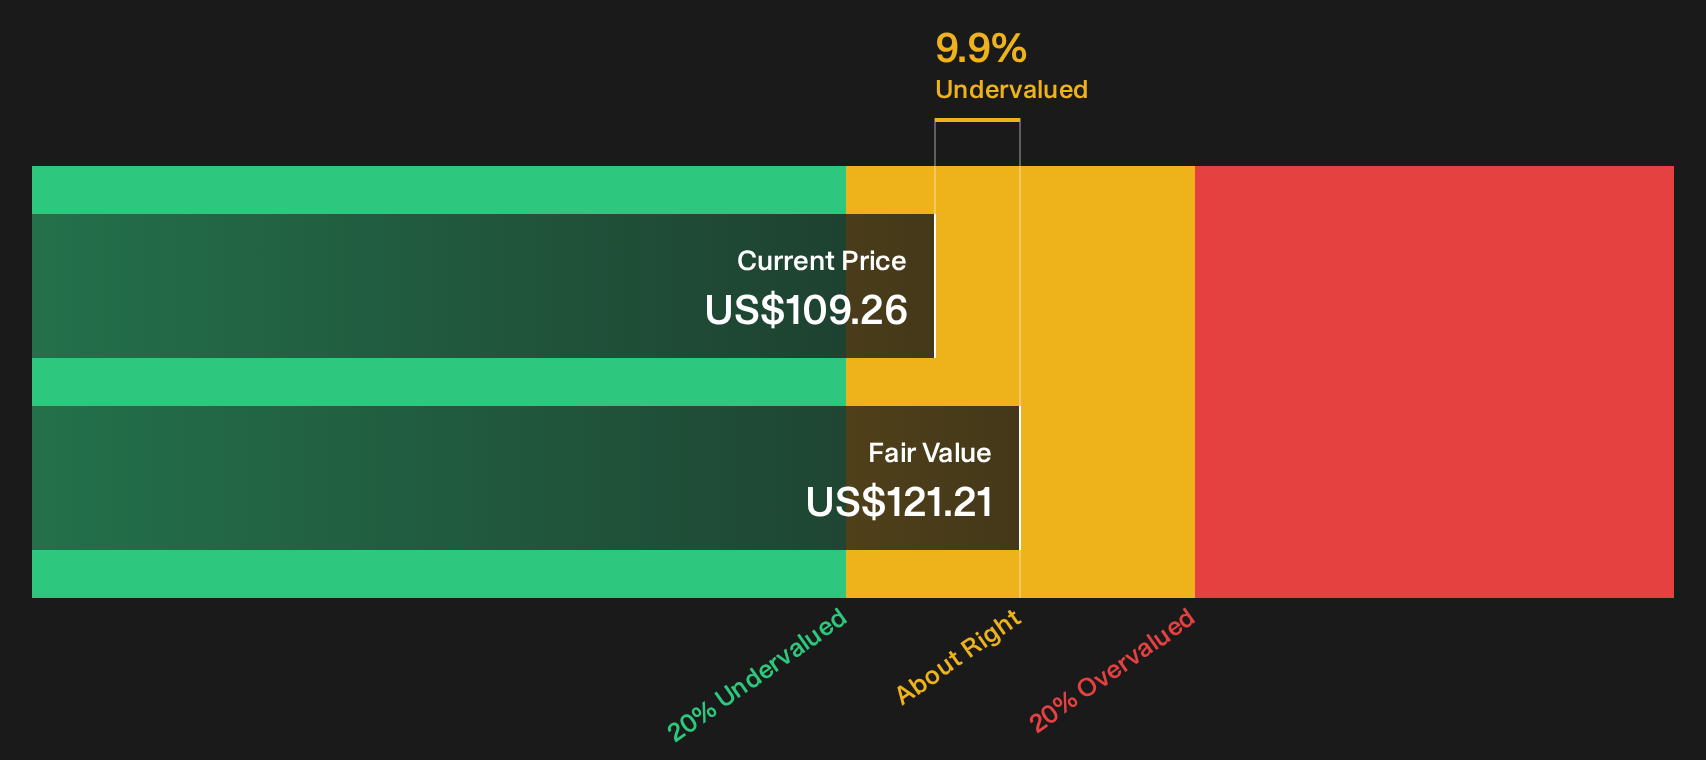
Simply Wall St's DCF model estimates Rubrik's future cash flow value at $121.21 per share, which is about 9.9% above the current price. That gap points to a model where the current quote leaves more room for long term value than the quarter focused narrative suggests. Which lens do you trust more when the next earnings print lands?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Rubrik for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether Rubrik tilts more toward opportunity or risk after this move and the mixed valuation signals? Act quickly, review the key data points, and weigh both sides of the argument by checking the 2 key rewards and 2 important warning signs.
Looking for more Rubrik-sized investment ideas?
If Rubrik has sharpened your focus on risk, reward, and timing, widen your watchlist now so you are not relying on a single story.
- Target more resilient opportunities by scanning the 30 resilient stocks with low risk scores that filters for companies with steadier profiles when markets turn choppy.
- Hunt for potential mispricings through the 32 high quality undervalued stocks to see which businesses combine quality fundamentals with prices that still lag their underlying strength.
- Build a cash flow stream using the 6 dividend fortresses and see which higher yielding companies still pair payouts with balance sheet support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com