


Talanx (XTRA:TLX) just posted higher net income for the third quarter of 2026 and for the first nine months, a material earnings update that puts fresh focus on the insurer’s recent share performance.
Talanx shares trade at €132.8 after a 1 day share price gain of 1.45%, capping a 30 day share price return of 8.14% and an 18.25% year to date move. The 1 year total shareholder return of 20.42% and 5 year total shareholder return of 288% point to momentum that investors are now reassessing in light of the stronger net income figures.
Capitalize on the renewed interest in Talanx by comparing it with a curated 194 high quality undervalued stocks that pairs solid fundamentals with potential mispricing in the market.Talanx just delivered higher net income and a strong run in the share price. The business looks solid. The next step is to see whether that recent enthusiasm still leaves room on valuation.
Most Popular Narrative: 1.6% Overvalued
The analyst consensus Narrative on Simply Wall St puts Talanx's fair value at €130.71, a touch below the latest close at €132.8. This frames the current discussion around whether investors are paying a modest premium for its strengths.
The strengthened balance sheet, with claims reserves booked significantly above best estimate by about €5.9b and a solvency ratio in the mid 240s %, gives Talanx more capacity to absorb large losses while still funding dividends and supporting earnings stability.
See why 38 investors see Talanx as 2% overvalued.
The Narrative applies a 5.41% discount rate to analysts' revenue and earnings forecasts and arrives at a fair value that is close to where Talanx trades today. With the market price only slightly above that €130.71 estimate, the current tag reflects a view that cost efficiency, reserve strength and diversified P&C earnings are already largely embedded into expectations.
Result: Fair Value of €130.71 (OVERVALUED)
Still, the Talanx story could be challenged if large loss claims move back above long term assumptions, or if softer Corporate & Specialty pricing drags on revenue.
Find out about the key risks to this Talanx narrative.
Another View: Talanx Through The Cash Flow Lens
The market price of Talanx looks only 1.6% above the €130.71 fair value implied by analyst targets. Our DCF model presents a different picture, with a future cash flow value of €327.81 per share, which frames the current €132.8 level as trading well below that estimate. Which story do you trust more?
Look into how the SWS DCF model arrives at its fair value.
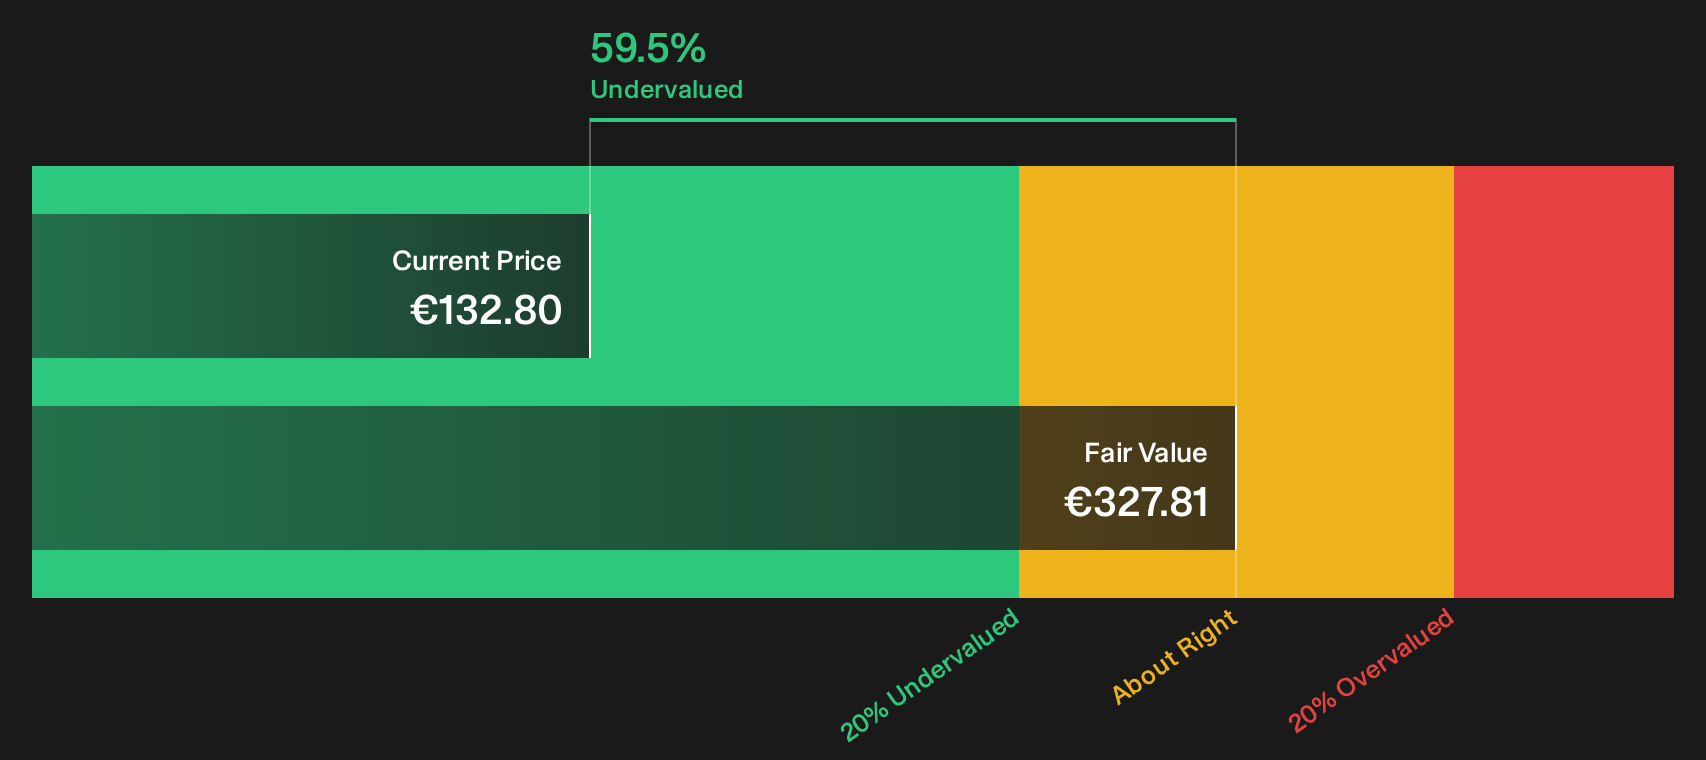
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Talanx for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Fresh net income and a long run of positive returns can make Talanx look straightforward, yet the full picture always lives in the details you review yourself. To see what optimism in the data looks like in practice, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond Talanx?
Fresh results at Talanx are useful, but your edge often comes from comparing it with other solid opportunities that the wider market may be overlooking.
- Target quality at a discount by scanning companies that pair resilient earnings power with possible pricing gaps through the 194 high quality undervalued stocks.
- Prioritise staying power over excitement and focus on sturdier finances with the list of solid balance sheet and fundamentals (199 results).
- Hunt for tomorrow's leaders before they hit the headlines by working through the 564 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com